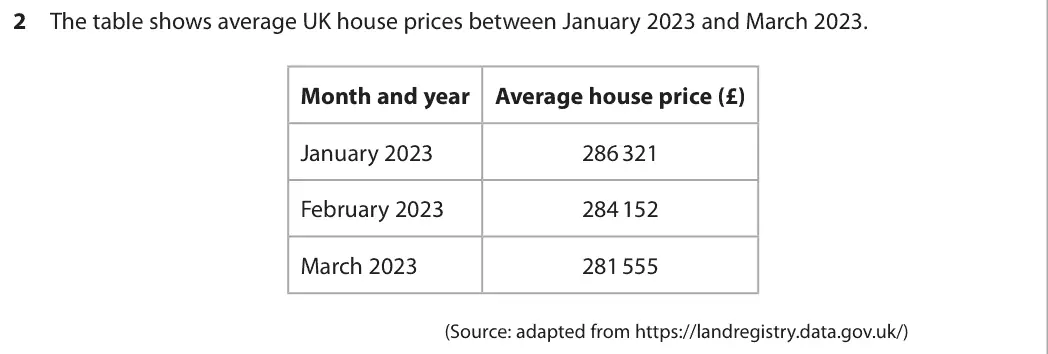The hardest Edexcel Economics questions

Pearson Edexcel's examiner reports occasionally give the proportion of marks scored nationally on a question. These are the 39 parts on current content where it was under 35%, with the examiner's comment on where answers fell short.

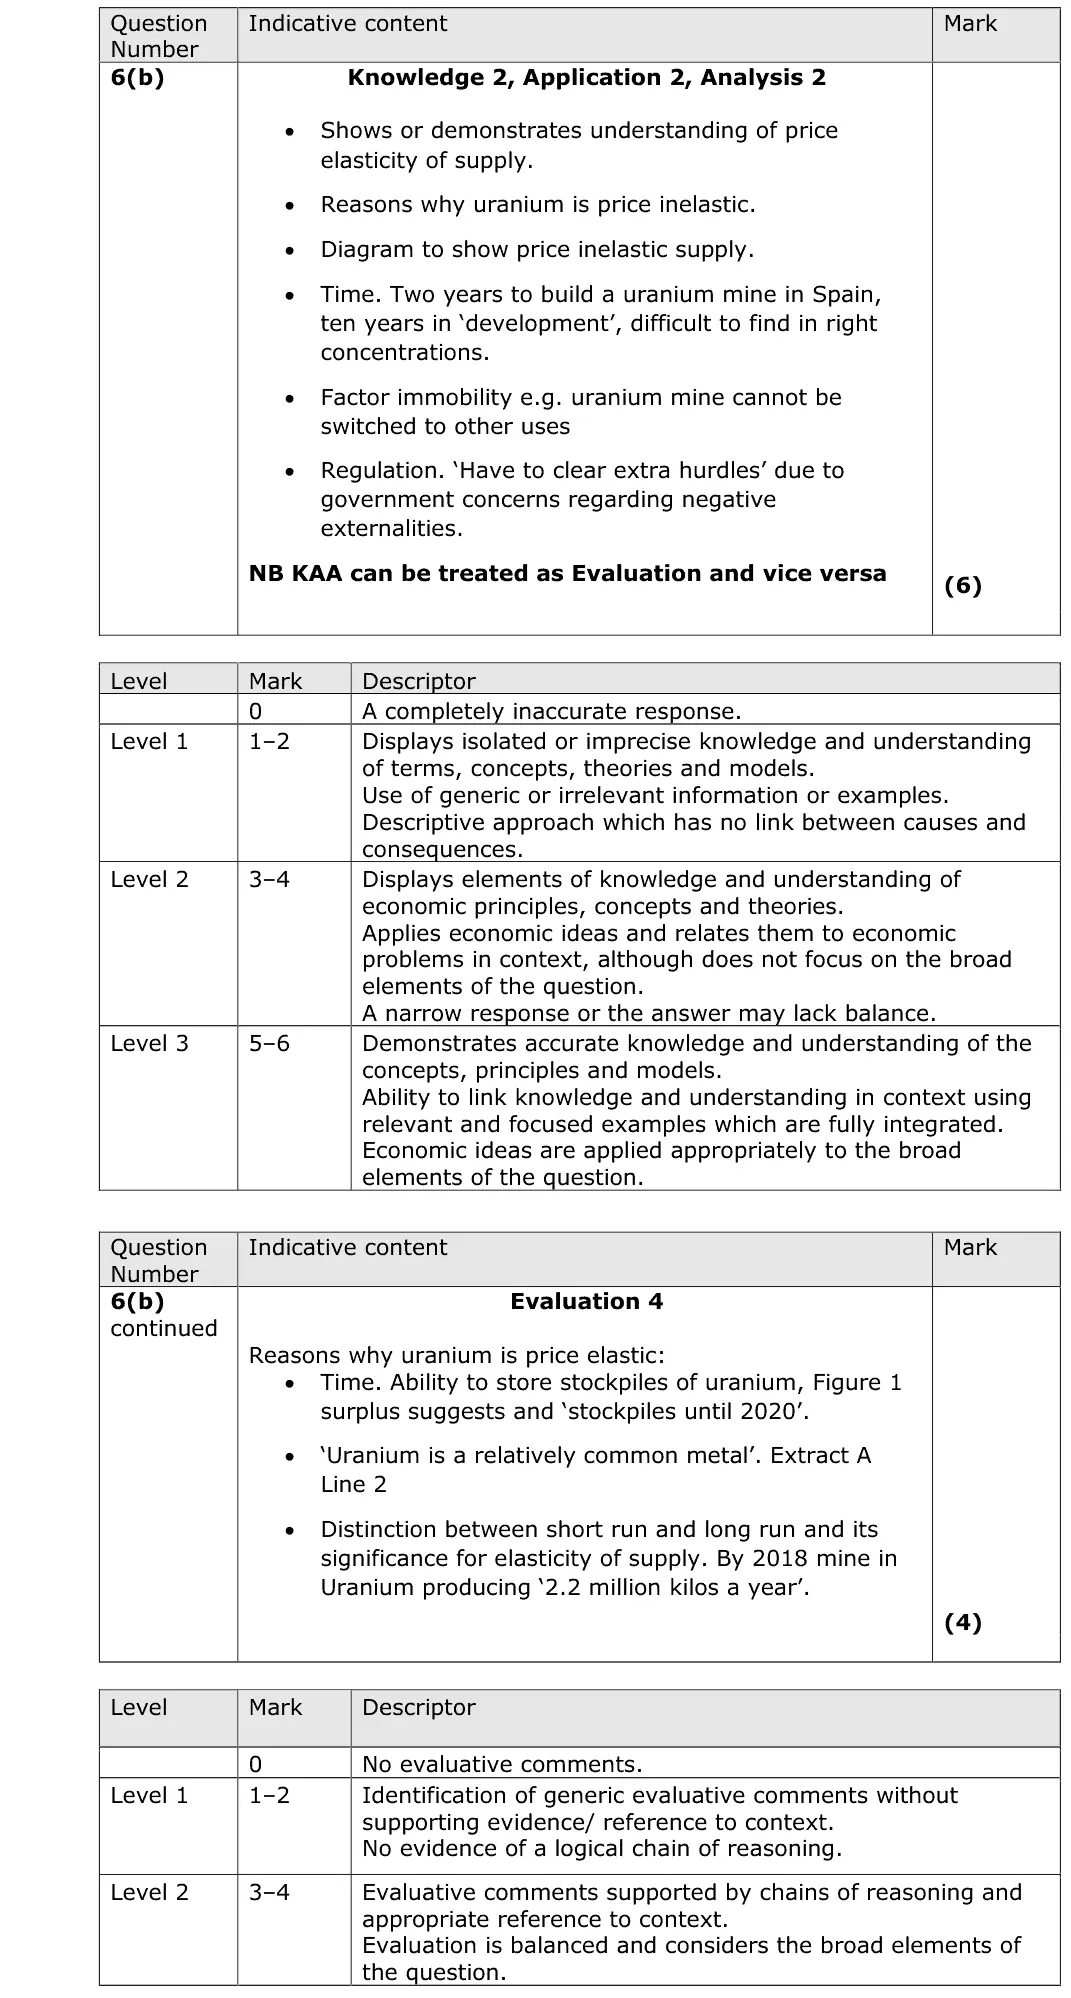
June 2018 · AS Paper 1 · Q6(b) 10 marks AO1=2, AO2=2, AO3=2, AO4=4 10-mark response Hard elasticity of supply
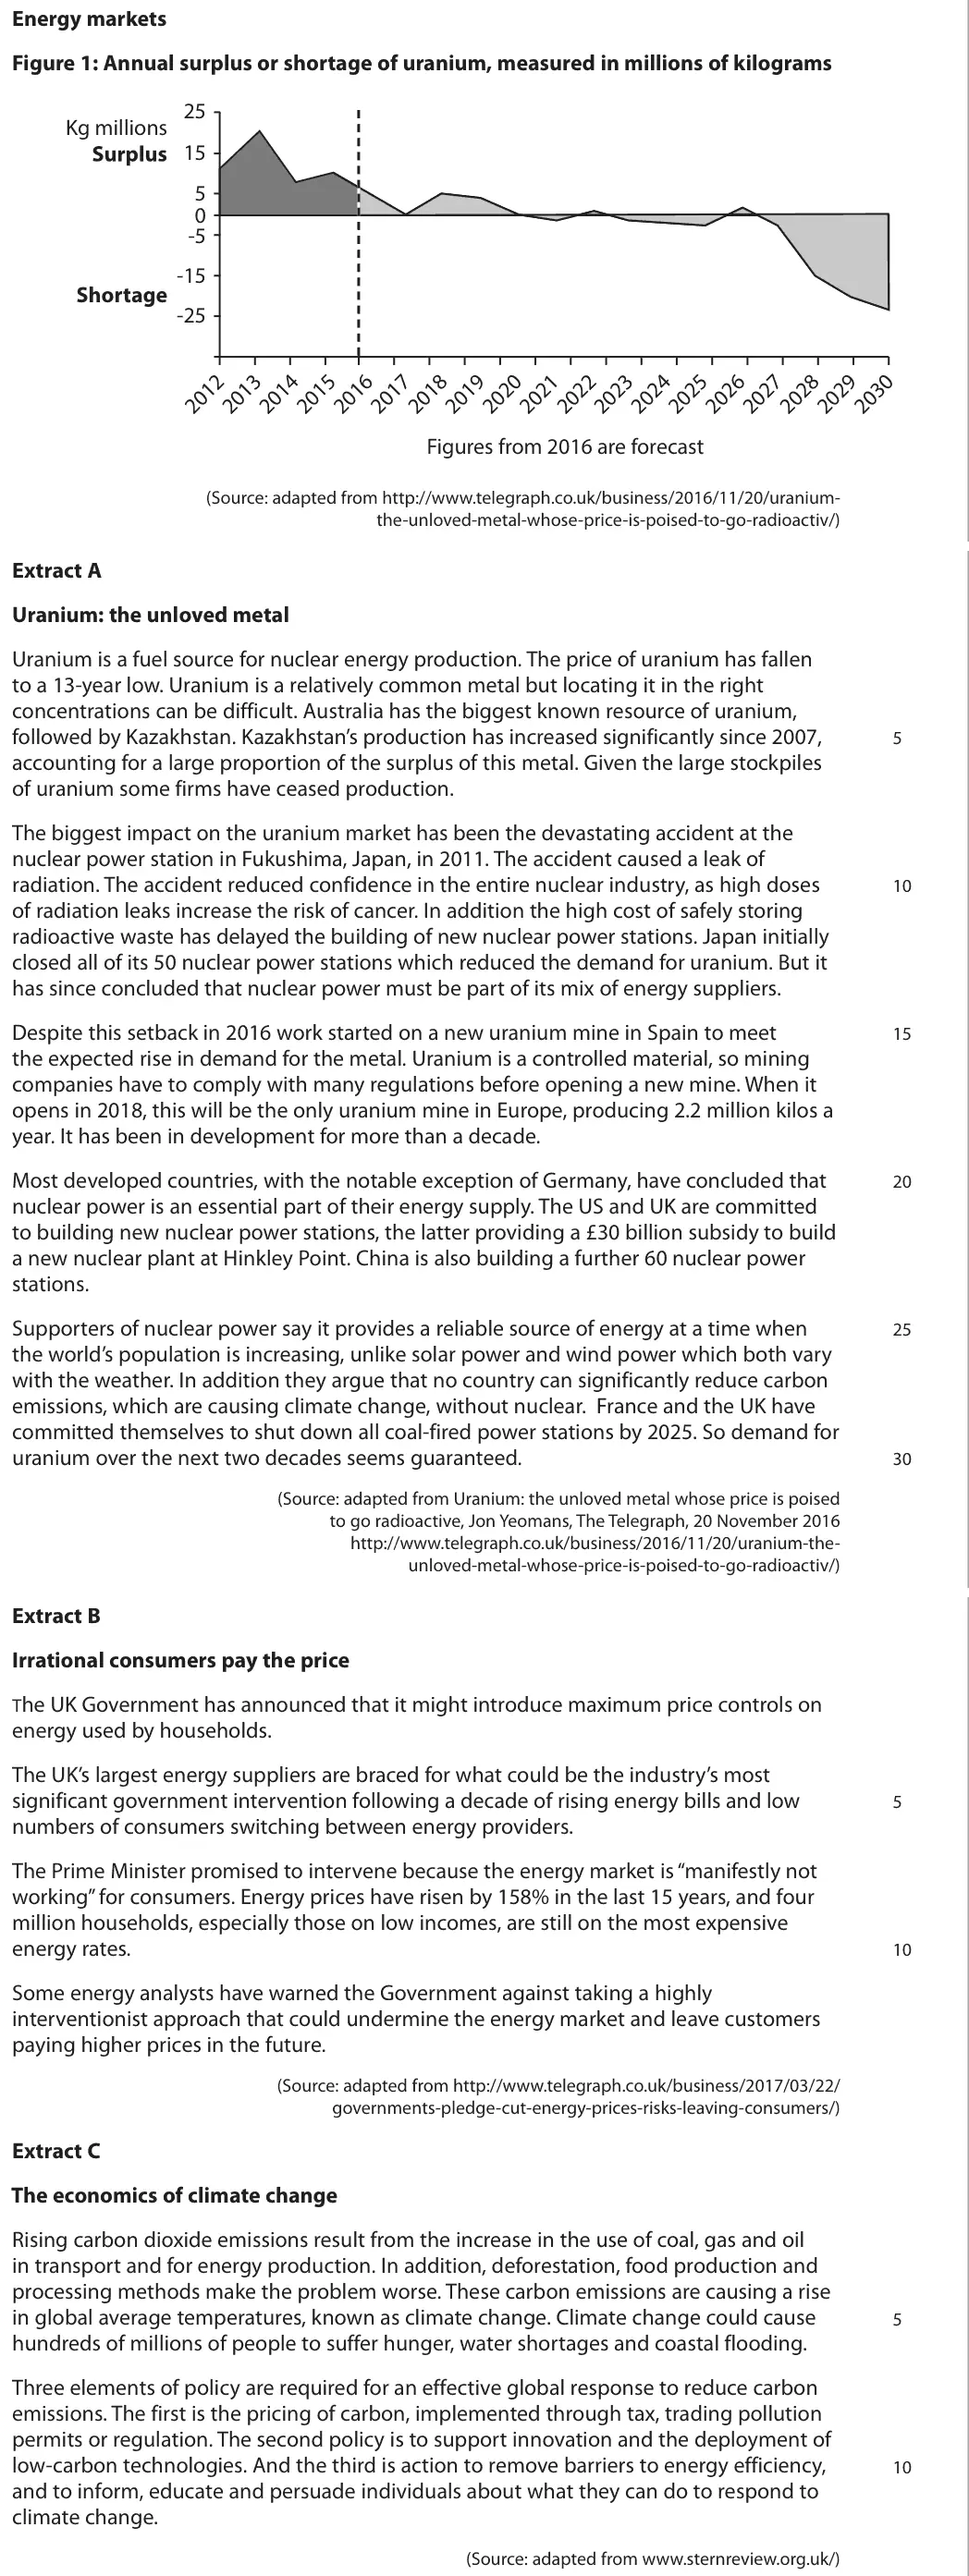
Data and extracts for question 6Energy markets Figure 1: Annual surplus or shortage of uranium, measured in millions of kilograms 25 Kg millions 15 5 0 -5 -15 -25 Figures from 2016 are forecast (Source: adapted from http://www.telegraph.co.uk/business/2016/11/20/uranium- the-unloved-metal-whose-price-is-poised-to-go-radioactiv/) Extract A Uranium: the unloved metal Uranium is a fuel source for nuclear energy production. The price of uranium has fallen to a 13-year low. Uranium is a relatively common metal but locating it in the right concentrations can be difficult. Australia has the biggest known resource of uranium, followed by Kazakhstan. Kazakhstan’s production has increased significantly since 2007, 5 accounting for a large proportion of the surplus of this metal. Given the large stockpiles of uranium some firms have ceased production. The biggest impact on the uranium market has been the devastating accident at the nuclear power station in Fukushima, Japan, in 2011. The accident caused a leak of radiation. The accident reduced confidence in the entire nuclear industry, as high doses 10 of radiation leaks increase the risk of cancer. In addition the high cost of safely storing radioactive waste has delayed the building of new nuclear power stations. Japan initially closed all of its 50 nuclear power stations which reduced the demand for uranium. But it has since concluded that nuclear power must be part of its mix of energy suppliers. Despite this setback in 2016 work started on a new uranium mine in Spain to meet 15 the expected rise in demand for the metal. Uranium is a controlled material, so mining companies have to comply with many regulations before opening a new mine. When it opens in 2018, this will be the only uranium mine in Europe, producing 2.2 million kilos a year. It has been in development for more than a decade. Most developed countries, with the notable exception of Germany, have concluded that 20 nuclear power is an essential part of their energy supply. The US and UK are committed to building new nuclear power stations, the latter providing a £30 billion subsidy to build a new nuclear plant at Hinkley Point. China is also building a further 60 nuclear power stations. Supporters of nuclear power say it provides a reliable source of energy at a time when 25 the world’s population is increasing, unlike solar power and wind power which both vary with the weather. In addition they argue that no country can significantly reduce carbon emissions, which are causing climate change, without nuclear. France and the UK have committed themselves to shut down all coal-fired power stations by 2025. So demand for uranium over the next two decades seems guaranteed. 30 (Source: adapted from Uranium: the unloved metal whose price is poised to go radioactive, Jon Yeomans, The Telegraph, 20 November 2016 http://www.telegraph.co.uk/business/2016/11/20/uranium-the- unloved-metal-whose-price-is-poised-to-go-radioactiv/) Extract B Irrational consumers pay the price The UK Government has announced that it might introduce maximum price controls on energy used by households. The UK’s largest energy suppliers are braced for what could be the industry’s most significant government intervention following a decade of rising energy bills and low 5 numbers of consumers switching between energy providers. The Prime Minister promised to intervene because the energy market is “manifestly not working” for consumers. Energy prices have risen by 158% in the last 15 years, and four million households, especially those on low incomes, are still on the most expensive energy rates. 10 Some energy analysts have warned the Government against taking a highly interventionist approach that could undermine the energy market and leave customers paying higher prices in the future. (Source: adapted from http://www.telegraph.co.uk/business/2017/03/22/ governments-pledge-cut-energy-prices-risks-leaving-consumers/) Extract C The economics of climate change Rising carbon dioxide emissions result from the increase in the use of coal, gas and oil in transport and for energy production. In addition, deforestation, food production and processing methods make the problem worse. These carbon emissions are causing a rise in global average temperatures, known as climate change. Climate change could cause 5 hundreds of millions of people to suffer hunger, water shortages and coastal flooding. Three elements of policy are required for an effective global response to reduce carbon emissions. The first is the pricing of carbon, implemented through tax, trading pollution permits or regulation. The second policy is to support innovation and the deployment of low-carbon technologies. And the third is action to remove barriers to energy efficiency, 10 and to inform, educate and persuade individuals about what they can do to respond to climate change. (Source: adapted from www.sternreview.org.uk/)
(b) With reference to Extract A and your own knowledge, assess whether the supply of uranium is likely to be price elastic or price inelastic. (10)
June 2018 · AS Paper 1 · Q6(f) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard externalities
Data and extracts for question 6Energy markets Figure 1: Annual surplus or shortage of uranium, measured in millions of kilograms 25 Kg millions 15 5 0 -5 -15 -25 Figures from 2016 are forecast (Source: adapted from http://www.telegraph.co.uk/business/2016/11/20/uranium- the-unloved-metal-whose-price-is-poised-to-go-radioactiv/) Extract A Uranium: the unloved metal Uranium is a fuel source for nuclear energy production. The price of uranium has fallen to a 13-year low. Uranium is a relatively common metal but locating it in the right concentrations can be difficult. Australia has the biggest known resource of uranium, followed by Kazakhstan. Kazakhstan’s production has increased significantly since 2007, 5 accounting for a large proportion of the surplus of this metal. Given the large stockpiles of uranium some firms have ceased production. The biggest impact on the uranium market has been the devastating accident at the nuclear power station in Fukushima, Japan, in 2011. The accident caused a leak of radiation. The accident reduced confidence in the entire nuclear industry, as high doses 10 of radiation leaks increase the risk of cancer. In addition the high cost of safely storing radioactive waste has delayed the building of new nuclear power stations. Japan initially closed all of its 50 nuclear power stations which reduced the demand for uranium. But it has since concluded that nuclear power must be part of its mix of energy suppliers. Despite this setback in 2016 work started on a new uranium mine in Spain to meet 15 the expected rise in demand for the metal. Uranium is a controlled material, so mining companies have to comply with many regulations before opening a new mine. When it opens in 2018, this will be the only uranium mine in Europe, producing 2.2 million kilos a year. It has been in development for more than a decade. Most developed countries, with the notable exception of Germany, have concluded that 20 nuclear power is an essential part of their energy supply. The US and UK are committed to building new nuclear power stations, the latter providing a £30 billion subsidy to build a new nuclear plant at Hinkley Point. China is also building a further 60 nuclear power stations. Supporters of nuclear power say it provides a reliable source of energy at a time when 25 the world’s population is increasing, unlike solar power and wind power which both vary with the weather. In addition they argue that no country can significantly reduce carbon emissions, which are causing climate change, without nuclear. France and the UK have committed themselves to shut down all coal-fired power stations by 2025. So demand for uranium over the next two decades seems guaranteed. 30 (Source: adapted from Uranium: the unloved metal whose price is poised to go radioactive, Jon Yeomans, The Telegraph, 20 November 2016 http://www.telegraph.co.uk/business/2016/11/20/uranium-the- unloved-metal-whose-price-is-poised-to-go-radioactiv/) Extract B Irrational consumers pay the price The UK Government has announced that it might introduce maximum price controls on energy used by households. The UK’s largest energy suppliers are braced for what could be the industry’s most significant government intervention following a decade of rising energy bills and low 5 numbers of consumers switching between energy providers. The Prime Minister promised to intervene because the energy market is “manifestly not working” for consumers. Energy prices have risen by 158% in the last 15 years, and four million households, especially those on low incomes, are still on the most expensive energy rates. 10 Some energy analysts have warned the Government against taking a highly interventionist approach that could undermine the energy market and leave customers paying higher prices in the future. (Source: adapted from http://www.telegraph.co.uk/business/2017/03/22/ governments-pledge-cut-energy-prices-risks-leaving-consumers/) Extract C The economics of climate change Rising carbon dioxide emissions result from the increase in the use of coal, gas and oil in transport and for energy production. In addition, deforestation, food production and processing methods make the problem worse. These carbon emissions are causing a rise in global average temperatures, known as climate change. Climate change could cause 5 hundreds of millions of people to suffer hunger, water shortages and coastal flooding. Three elements of policy are required for an effective global response to reduce carbon emissions. The first is the pricing of carbon, implemented through tax, trading pollution permits or regulation. The second policy is to support innovation and the deployment of low-carbon technologies. And the third is action to remove barriers to energy efficiency, 10 and to inform, educate and persuade individuals about what they can do to respond to climate change. (Source: adapted from www.sternreview.org.uk/)
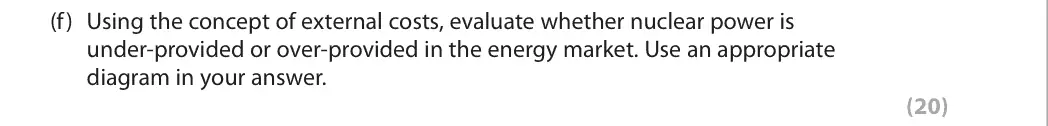
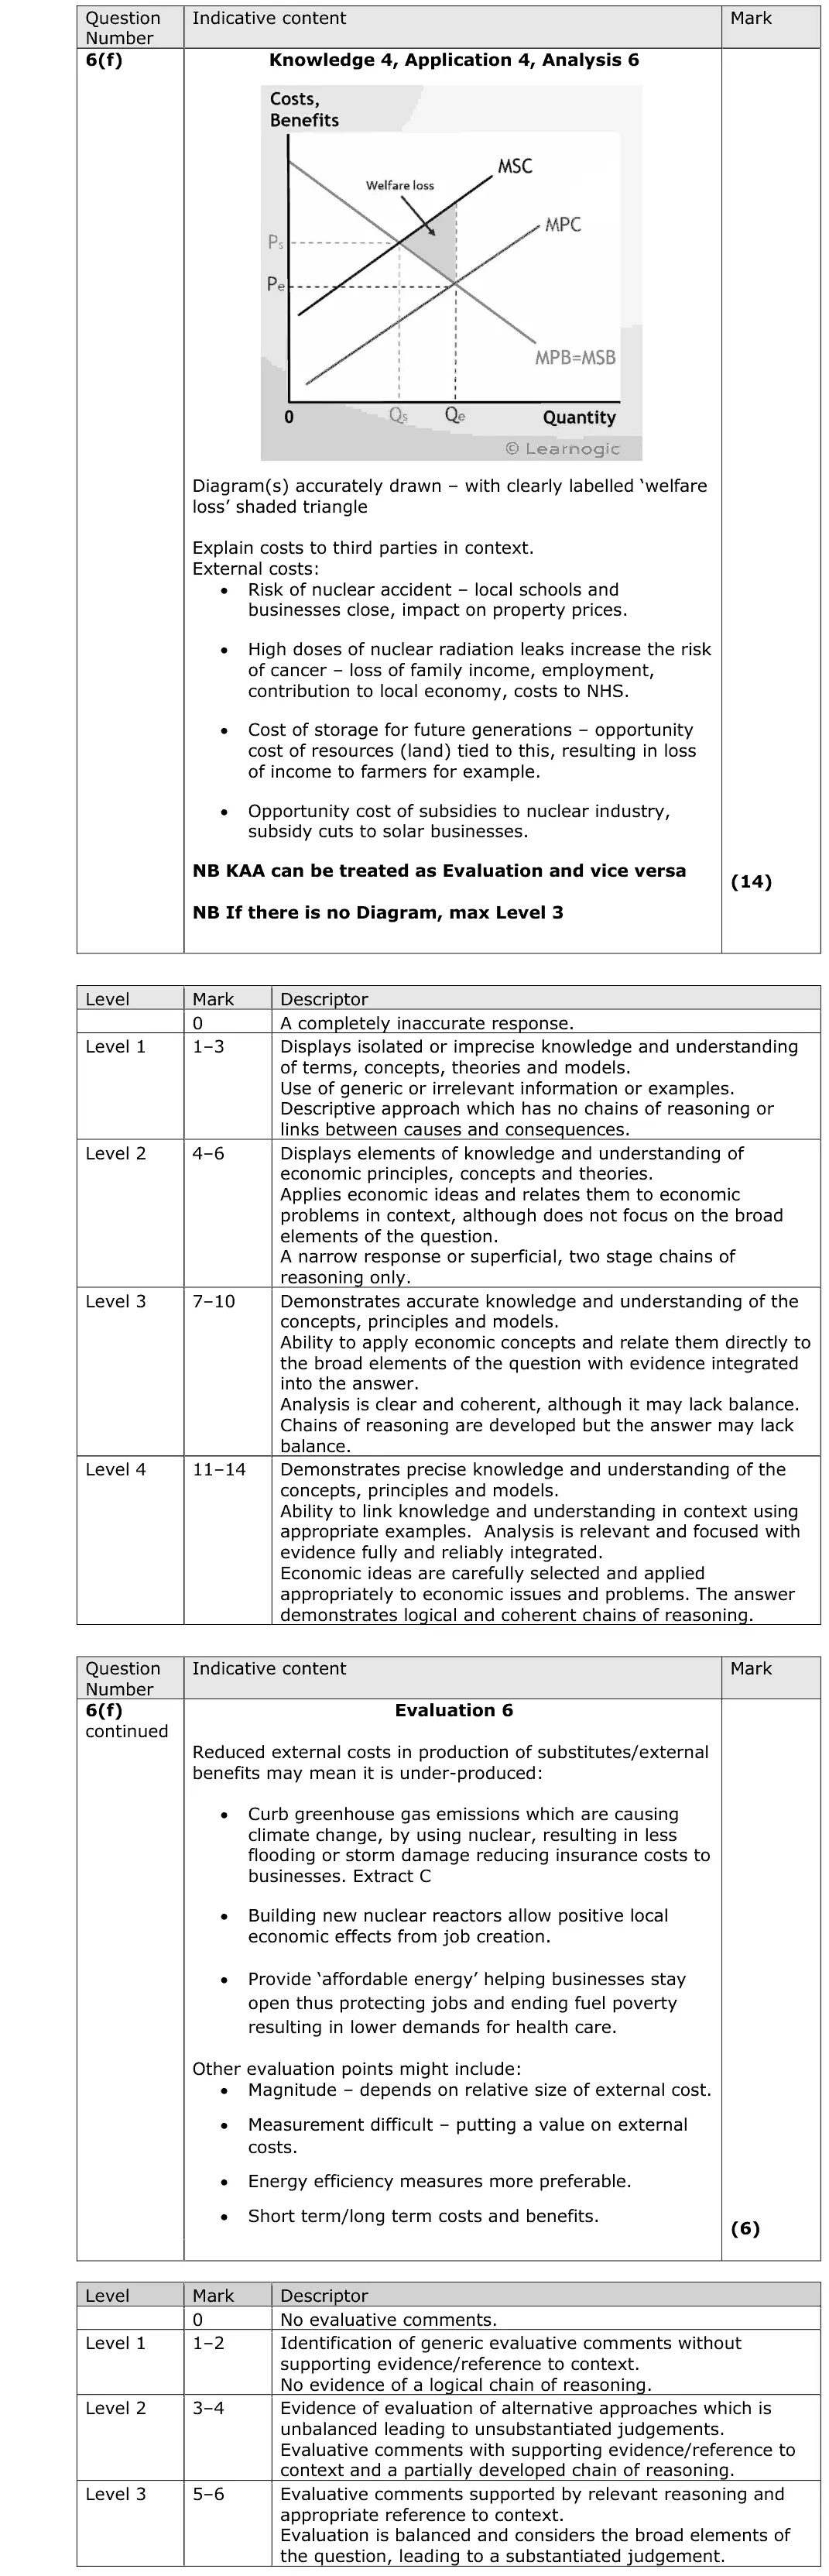
(f) Using the concept of external costs, evaluate whether nuclear power is under-provided or over-provided in the energy market. Use an appropriate diagram in your answer. (20)
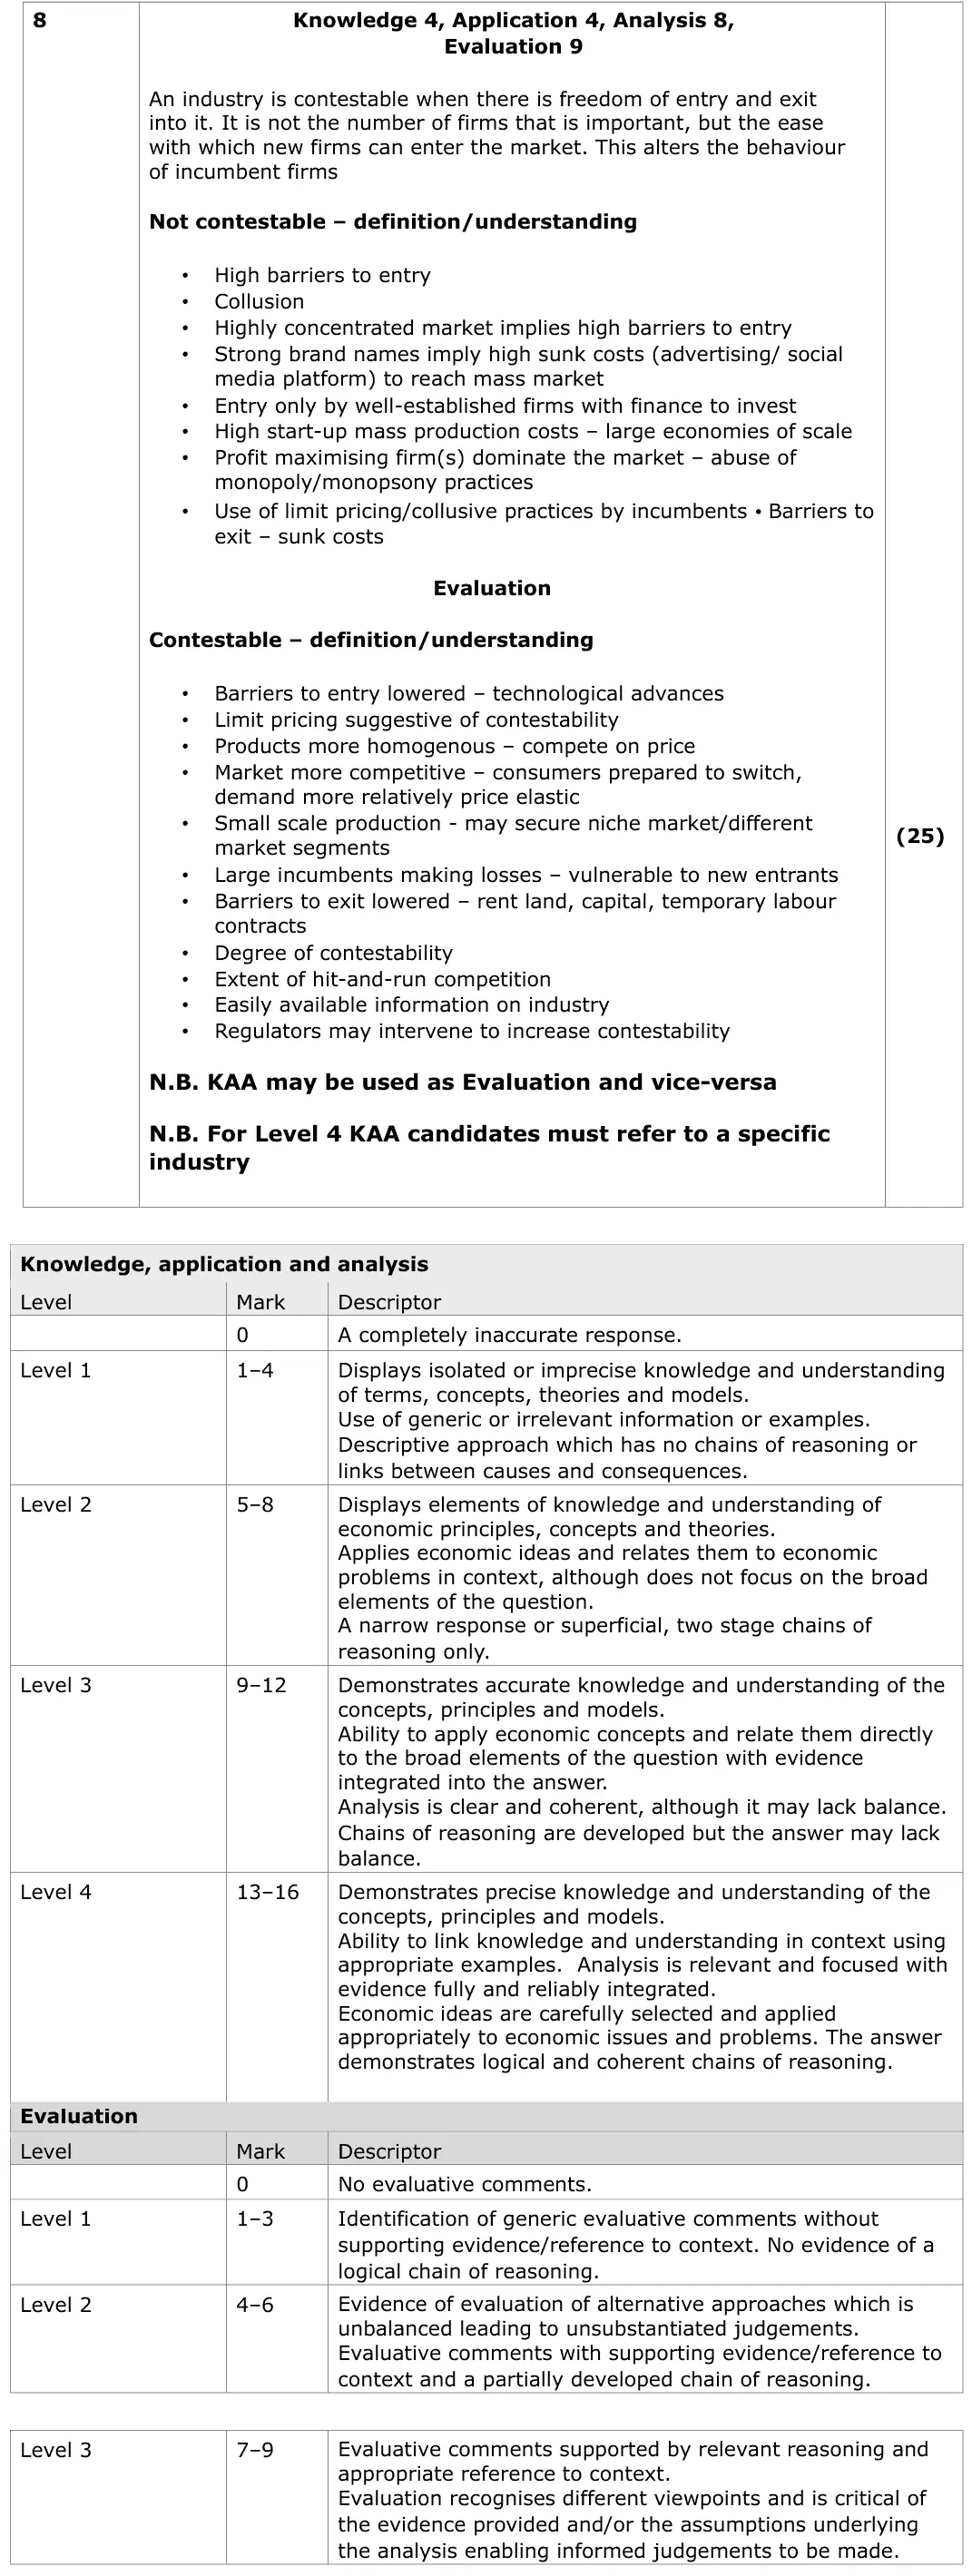
June 2022 · AS Paper 1 · Q6(f) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard externalities
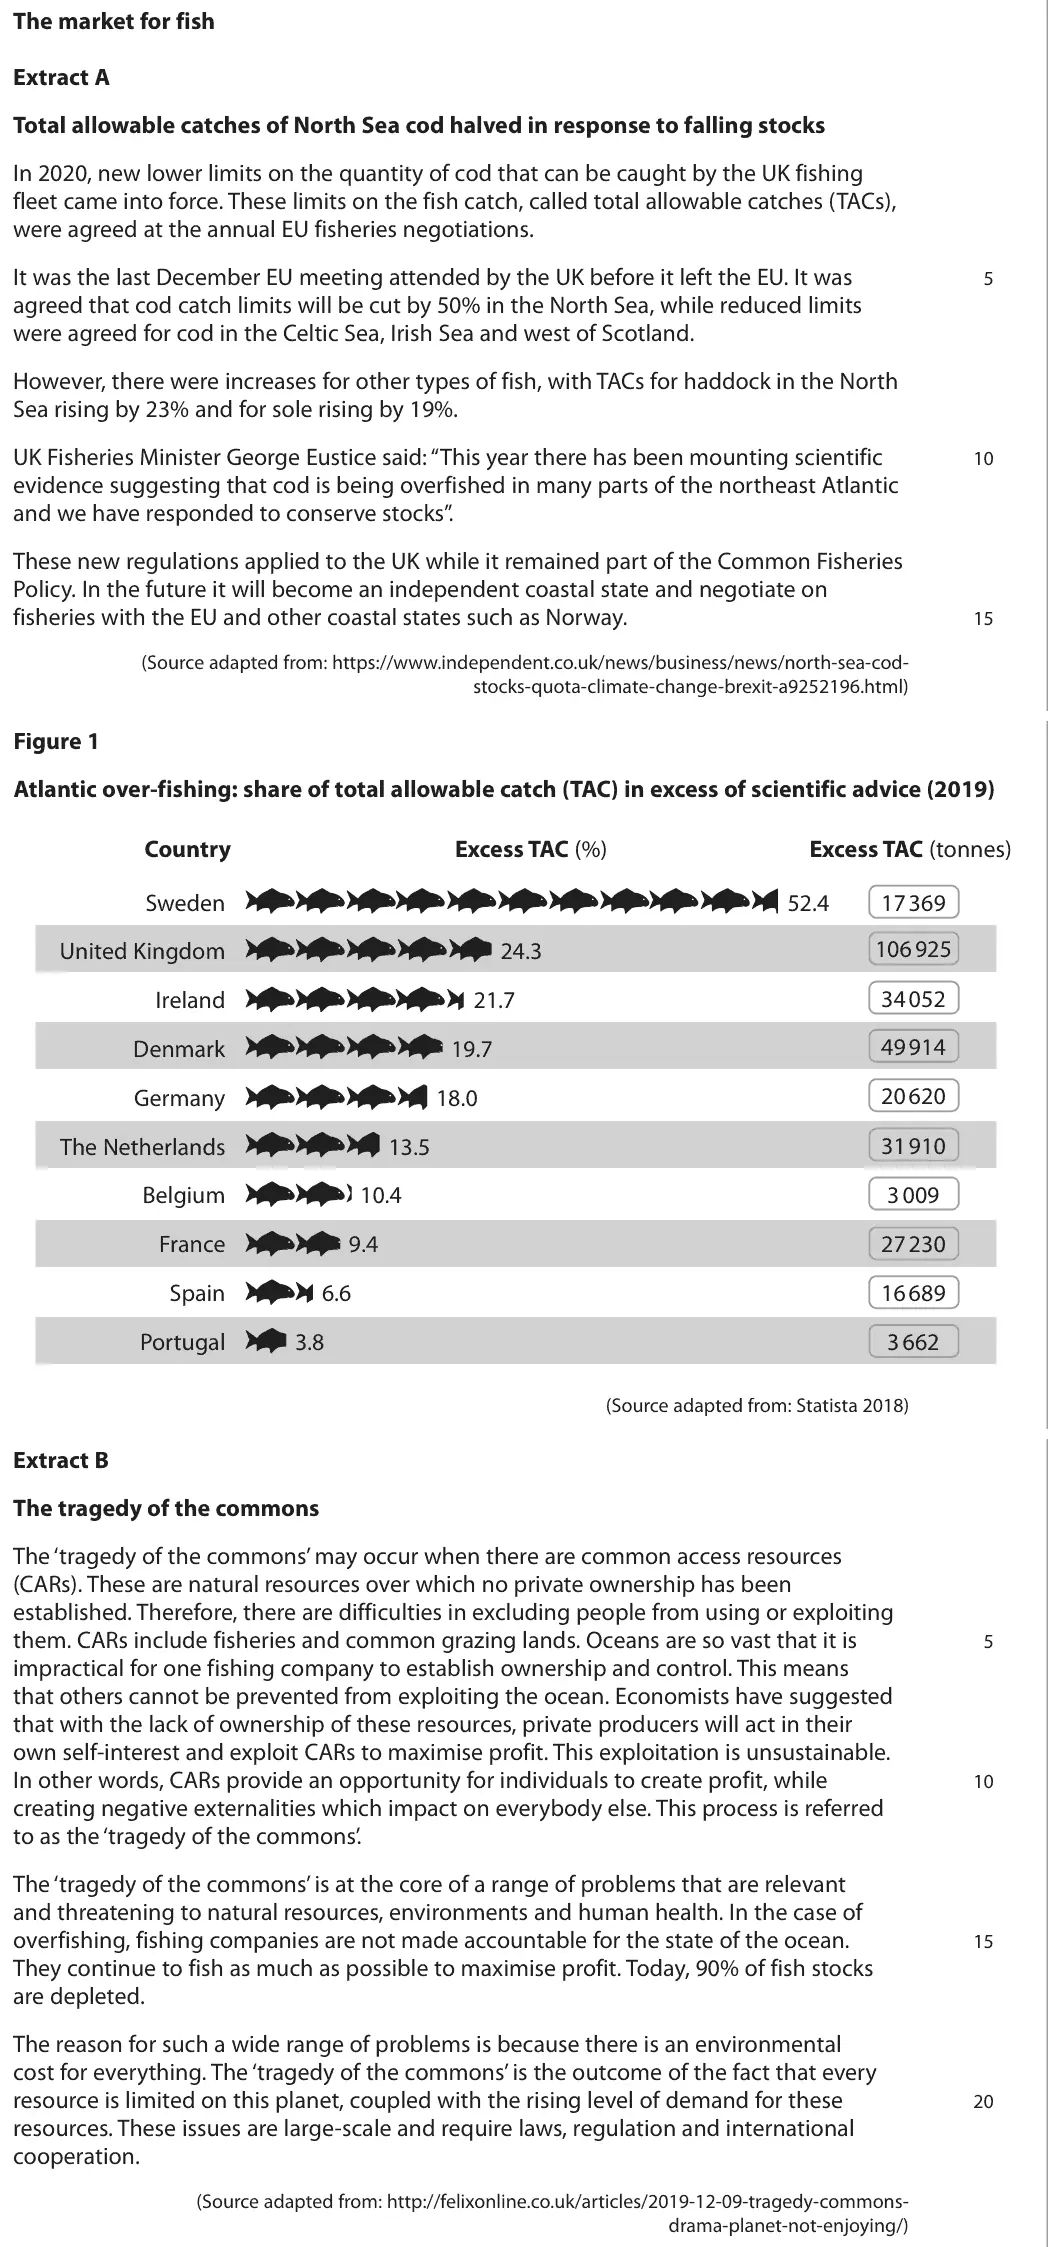
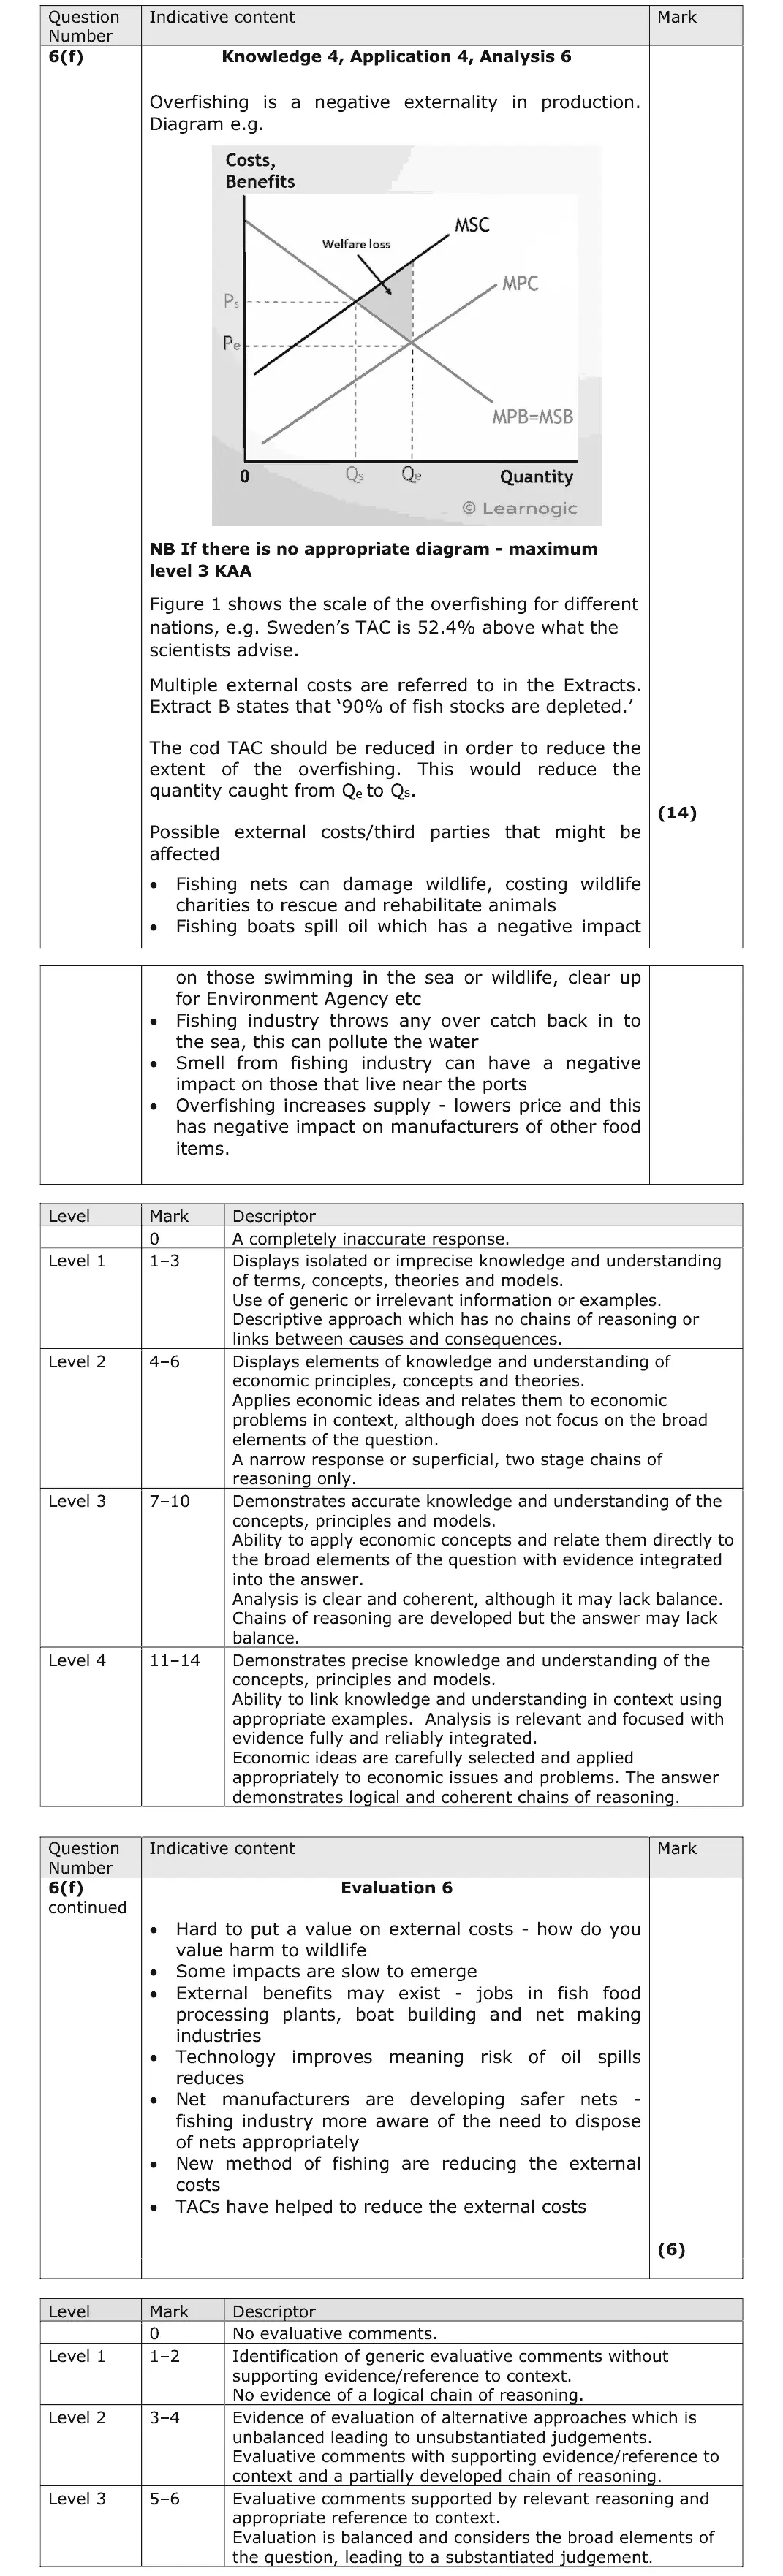
Data and extracts for question 6The market for fish Extract A Total allowable catches of North Sea cod halved in response to falling stocks In 2020, new lower limits on the quantity of cod that can be caught by the UK fishing fleet came into force. These limits on the fish catch, called total allowable catches (TACs), were agreed at the annual EU fisheries negotiations. It was the last December EU meeting attended by the UK before it left the EU. It was 5 agreed that cod catch limits will be cut by 50% in the North Sea, while reduced limits were agreed for cod in the Celtic Sea, Irish Sea and west of Scotland. However, there were increases for other types of fish, with TACs for haddock in the North Sea rising by 23% and for sole rising by 19%. UK Fisheries Minister George Eustice said: “This year there has been mounting scientific 10 evidence suggesting that cod is being overfished in many parts of the northeast Atlantic and we have responded to conserve stocks”. These new regulations applied to the UK while it remained part of the Common Fisheries Policy. In the future it will become an independent coastal state and negotiate on fisheries with the EU and other coastal states such as Norway. 15 (Source adapted from: https://www.independent.co.uk/news/business/news/north-sea-cod- stocks-quota-climate-change-brexit-a9252196.html) Figure 1 Atlantic over-fishing: share of total allowable catch (TAC) in excess of scientific advice (2019) Country Excess TAC (%) Excess TAC (tonnes) Sweden 52.4 17 369 106 925 United Kingdom 24.3 34 052 Ireland 21.7 49 914 Denmark 19.7 20 620 Germany 18.0 The Netherlands 13.5 31 910 3 009 Belgium 10.4 France 9.4 27 230 Spain 6.6 16 689 Portugal 3.8 3 662 (Source adapted from: Statista 2018) Extract B The tragedy of the commons The ‘tragedy of the commons’ may occur when there are common access resources (CARs). These are natural resources over which no private ownership has been established. Therefore, there are difficulties in excluding people from using or exploiting them. CARs include fisheries and common grazing lands. Oceans are so vast that it is 5 impractical for one fishing company to establish ownership and control. This means that others cannot be prevented from exploiting the ocean. Economists have suggested that with the lack of ownership of these resources, private producers will act in their own self-interest and exploit CARs to maximise profit. This exploitation is unsustainable. In other words, CARs provide an opportunity for individuals to create profit, while 10 creating negative externalities which impact on everybody else. This process is referred to as the ‘tragedy of the commons’. The ‘tragedy of the commons’ is at the core of a range of problems that are relevant and threatening to natural resources, environments and human health. In the case of overfishing, fishing companies are not made accountable for the state of the ocean. 15 They continue to fish as much as possible to maximise profit. Today, 90% of fish stocks are depleted. The reason for such a wide range of problems is because there is an environmental cost for everything. The ‘tragedy of the commons’ is the outcome of the fact that every resource is limited on this planet, coupled with the rising level of demand for these 20 resources. These issues are large-scale and require laws, regulation and international cooperation. (Source adapted from: http://felixonline.co.uk/articles/2019-12-09-tragedy-commons- drama-planet-not-enjoying/)
(f) Some economists suggest that the market price of cod does not result in the socially optimum level of output. Evaluate the likely external costs from the over-fishing of cod. Use an appropriate diagram in your answer. (20)
June 2024 · AS Paper 1 · Q6(f) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard government intervention in marketsindirect taxes and subsidies
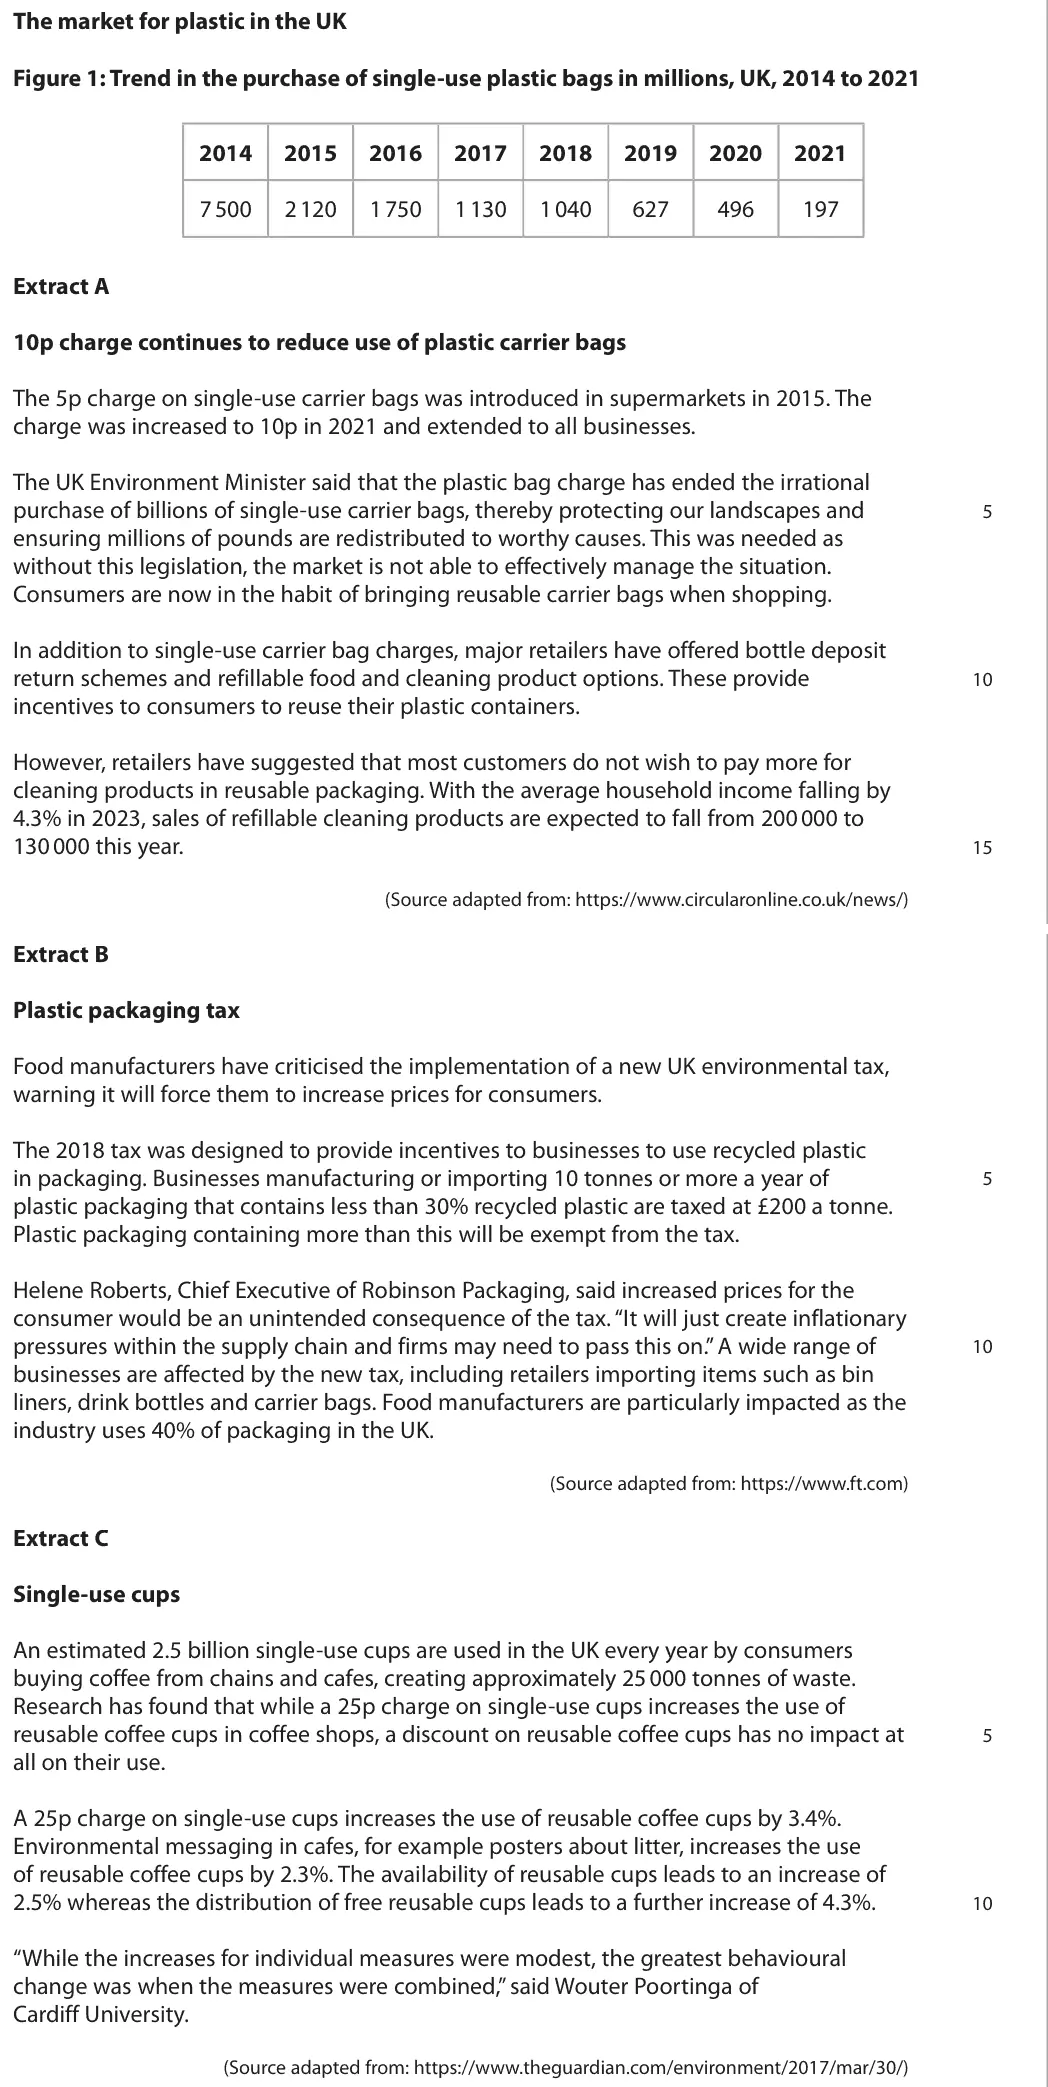
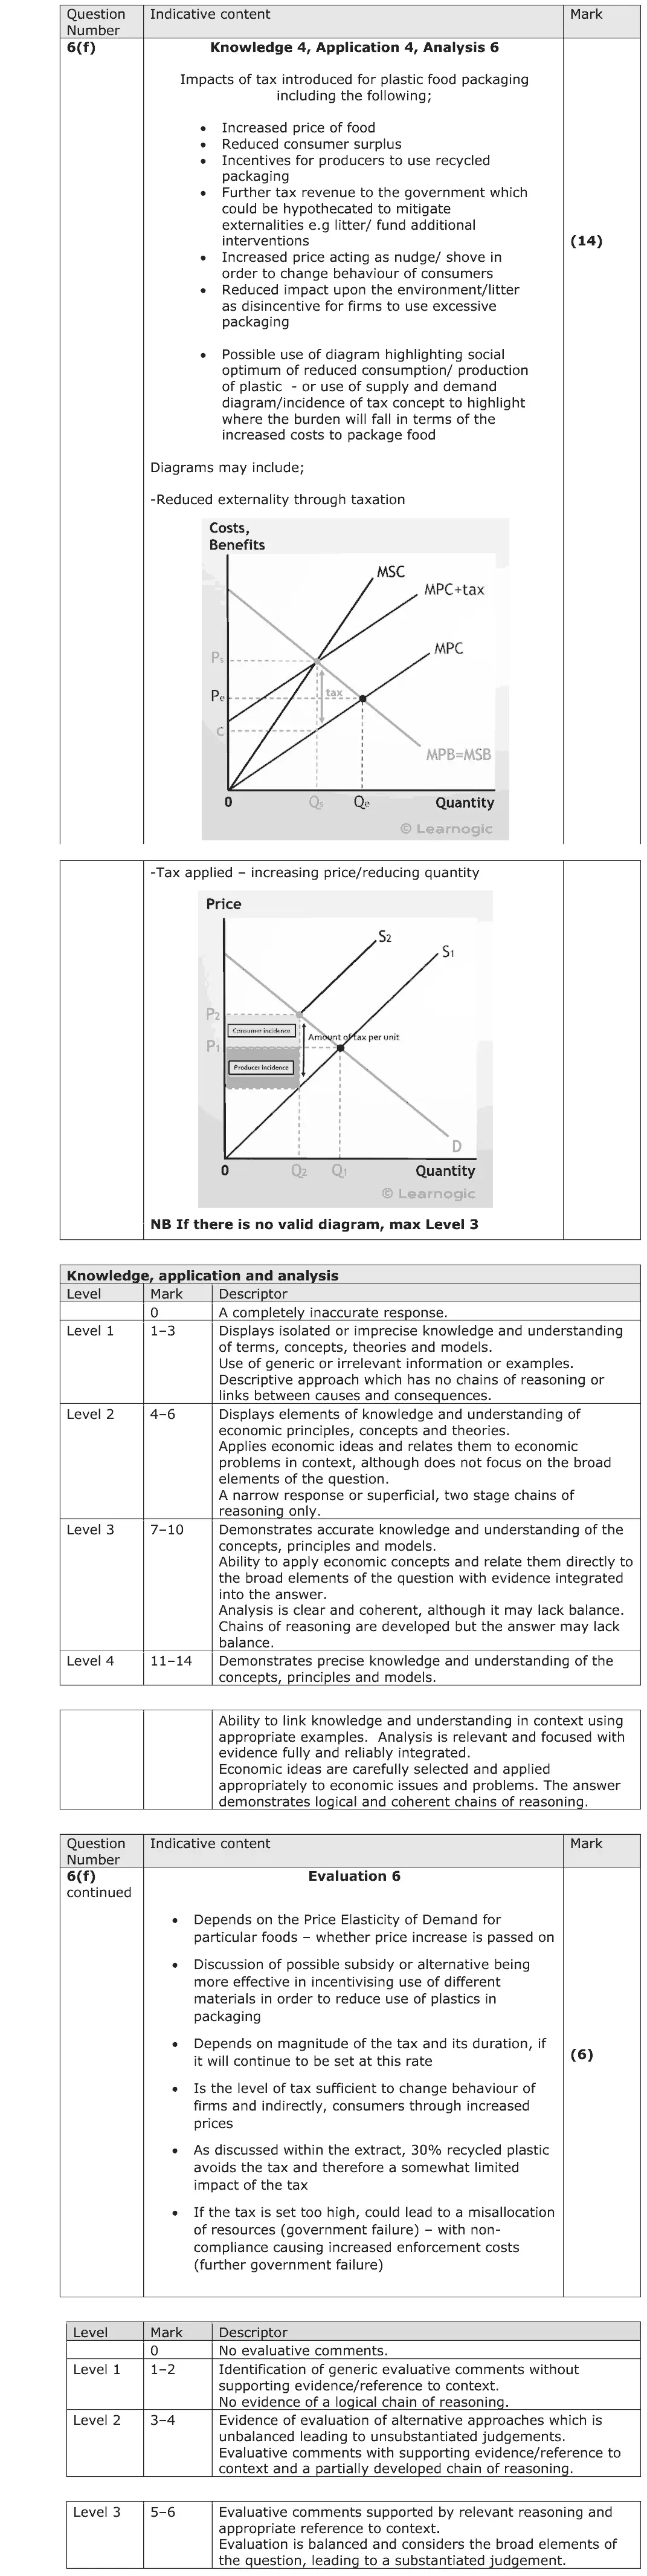
Data and extracts for question 6The market for plastic in the UK Figure 1: Trend in the purchase of single‑use plastic bags in millions, UK, 2014 to 2021 2014 2015 2016 2017 2018 2019 2020 2021 7 500 2 120 1 750 1 130 1 040 627 496 197 Extract A 10p charge continues to reduce use of plastic carrier bags The 5p charge on single‑use carrier bags was introduced in supermarkets in 2015. The charge was increased to 10p in 2021 and extended to all businesses. The UK Environment Minister said that the plastic bag charge has ended the irrational purchase of billions of single‑use carrier bags, thereby protecting our landscapes and 5 ensuring millions of pounds are redistributed to worthy causes. This was needed as without this legislation, the market is not able to effectively manage the situation. Consumers are now in the habit of bringing reusable carrier bags when shopping. In addition to single‑use carrier bag charges, major retailers have offered bottle deposit return schemes and refillable food and cleaning product options. These provide 10 incentives to consumers to reuse their plastic containers. However, retailers have suggested that most customers do not wish to pay more for cleaning products in reusable packaging. With the average household income falling by 4.3% in 2023, sales of refillable cleaning products are expected to fall from 200 000 to 130 000 this year. 15 (Source adapted from: https://www.circularonline.co.uk/news/) Extract B Plastic packaging tax Food manufacturers have criticised the implementation of a new UK environmental tax, warning it will force them to increase prices for consumers. The 2018 tax was designed to provide incentives to businesses to use recycled plastic in packaging. Businesses manufacturing or importing 10 tonnes or more a year of 5 plastic packaging that contains less than 30% recycled plastic are taxed at £200 a tonne. Plastic packaging containing more than this will be exempt from the tax. Helene Roberts, Chief Executive of Robinson Packaging, said increased prices for the consumer would be an unintended consequence of the tax. “It will just create inflationary pressures within the supply chain and firms may need to pass this on.” A wide range of 10 businesses are affected by the new tax, including retailers importing items such as bin liners, drink bottles and carrier bags. Food manufacturers are particularly impacted as the industry uses 40% of packaging in the UK. (Source adapted from: https://www.ft.com) Extract C Single‑use cups An estimated 2.5 billion single‑use cups are used in the UK every year by consumers buying coffee from chains and cafes, creating approximately 25 000 tonnes of waste. Research has found that while a 25p charge on single‑use cups increases the use of reusable coffee cups in coffee shops, a discount on reusable coffee cups has no impact at 5 all on their use. A 25p charge on single‑use cups increases the use of reusable coffee cups by 3.4%. Environmental messaging in cafes, for example posters about litter, increases the use of reusable coffee cups by 2.3%. The availability of reusable cups leads to an increase of 2.5% whereas the distribution of free reusable cups leads to a further increase of 4.3%. 10 “While the increases for individual measures were modest, the greatest behavioural change was when the measures were combined,” said Wouter Poortinga of Cardiff University. (Source adapted from: https://www.theguardian.com/environment/2017/mar/30/)
(f) Evaluate the likely impact of a tax on plastic food-packaging. Use a diagram to support your answer. (20)
June 2025 · AS Paper 1 · Q6(c) 6 marks Short answer Hard elasticity of supply
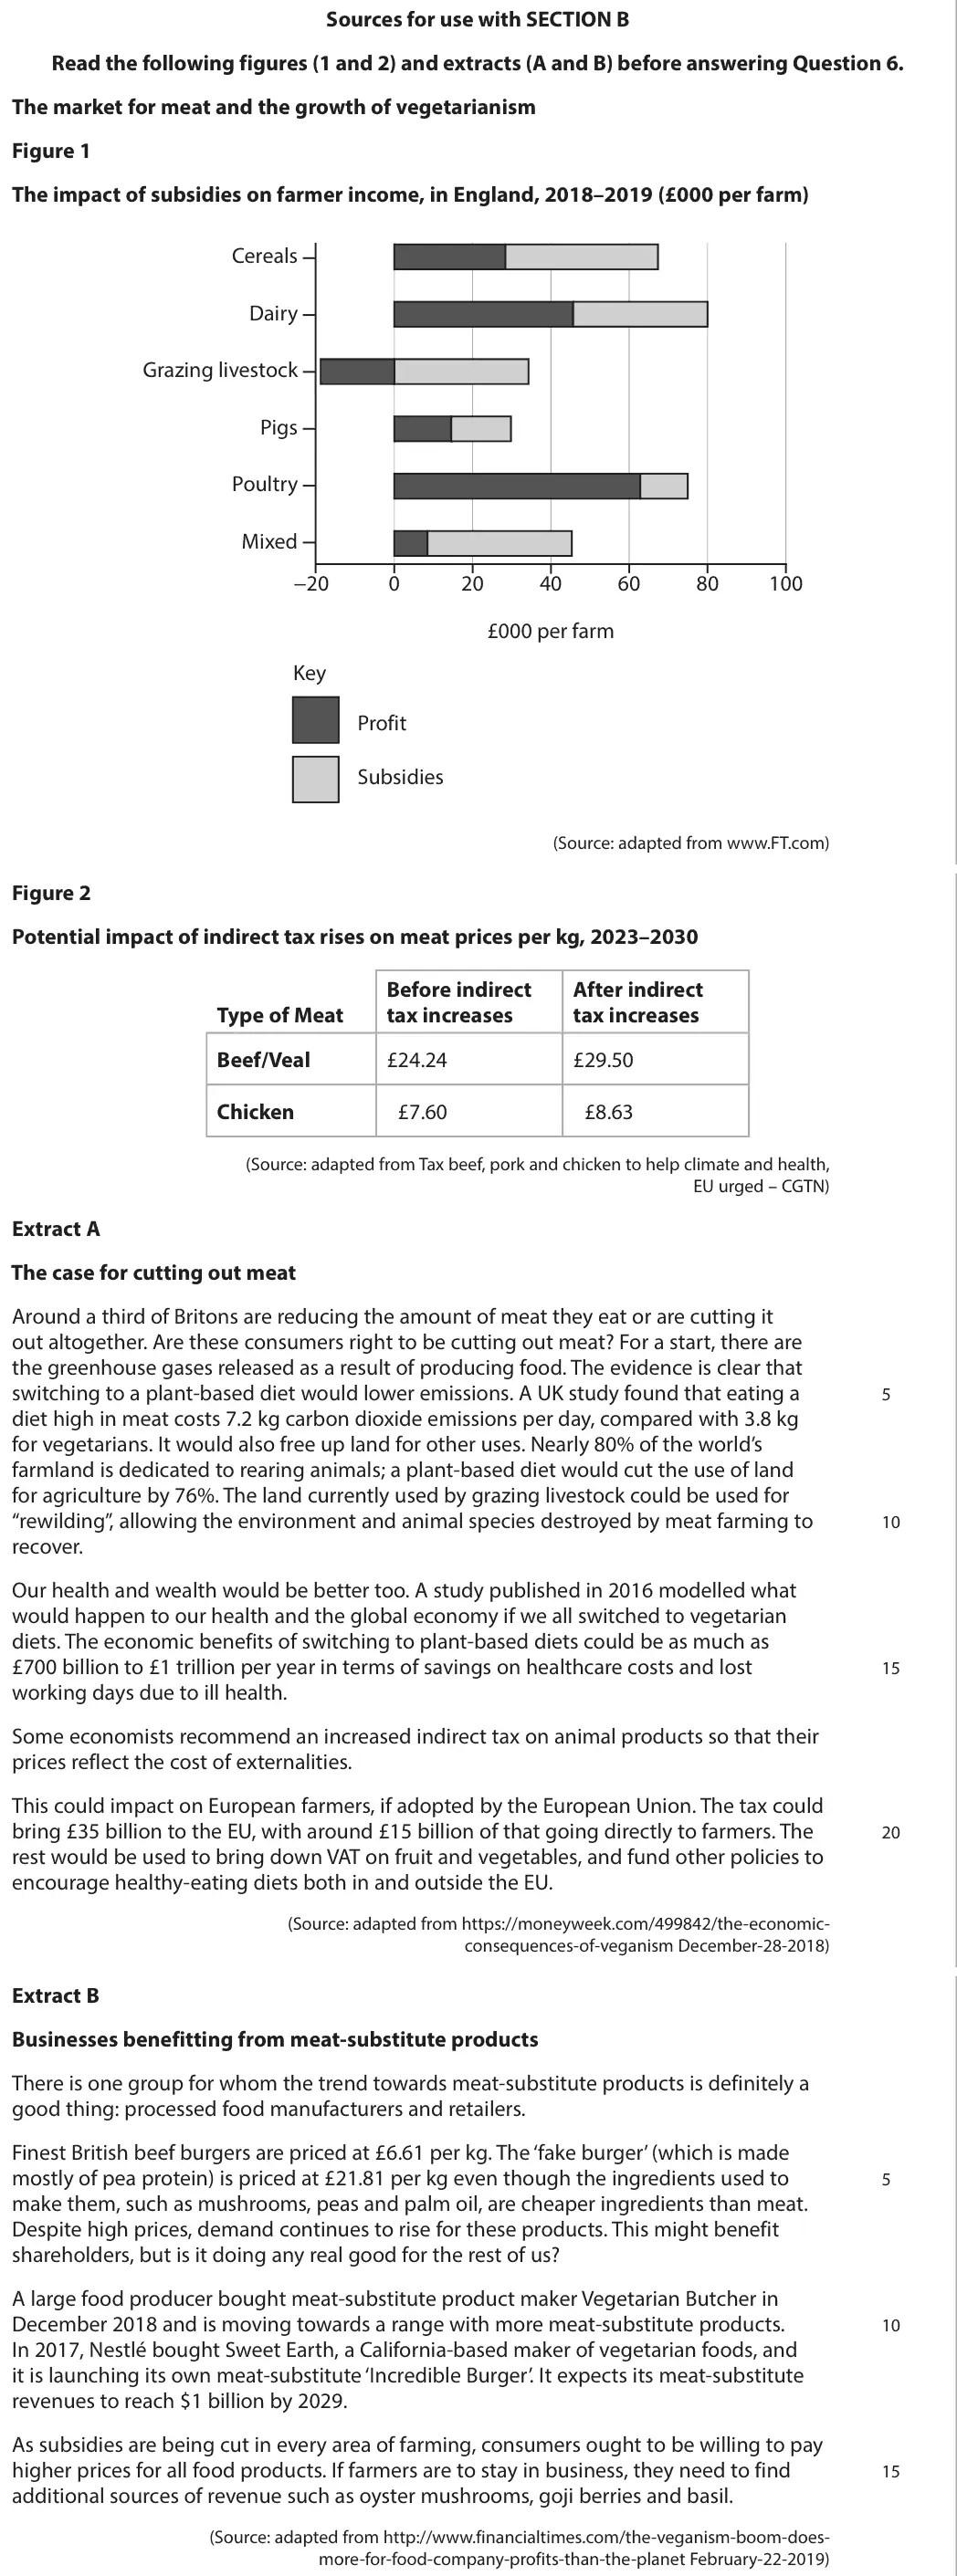
Data and extracts for question 6Sources for use with SECTION B Read the following figures (1 and 2) and extracts (A and B) before answering Question 6. The market for meat and the growth of vegetarianism Figure 1 The impact of subsidies on farmer income, in England, 2018–2019 (£000 per farm) Cereals Dairy Grazing livestock Pigs Poultry Mixed -20 0 20 40 60 80 100 £000 per farm Key Profit Subsidies (Source: adapted from www.FT.com) Figure 2 Potential impact of indirect tax rises on meat prices per kg, 2023–2030 Before indirect After indirect Type of Meat tax increases tax increases Beef/Veal £24.24 £29.50 Chicken £7.60 £8.63 (Source: adapted from Tax beef, pork and chicken to help climate and health, EU urged – CGTN) Extract A The case for cutting out meat Around a third of Britons are reducing the amount of meat they eat or are cutting it out altogether. Are these consumers right to be cutting out meat? For a start, there are the greenhouse gases released as a result of producing food. The evidence is clear that switching to a plant-based diet would lower emissions. A UK study found that eating a 5 diet high in meat costs 7.2 kg carbon dioxide emissions per day, compared with 3.8 kg for vegetarians. It would also free up land for other uses. Nearly 80% of the world’s farmland is dedicated to rearing animals; a plant-based diet would cut the use of land for agriculture by 76%. The land currently used by grazing livestock could be used for “rewilding”, allowing the environment and animal species destroyed by meat farming to 10 recover. Our health and wealth would be better too. A study published in 2016 modelled what would happen to our health and the global economy if we all switched to vegetarian diets. The economic benefits of switching to plant-based diets could be as much as £700 billion to £1 trillion per year in terms of savings on healthcare costs and lost 15 working days due to ill health. Some economists recommend an increased indirect tax on animal products so that their prices reflect the cost of externalities. This could impact on European farmers, if adopted by the European Union. The tax could bring £35 billion to the EU, with around £15 billion of that going directly to farmers. The 20 rest would be used to bring down VAT on fruit and vegetables, and fund other policies to encourage healthy-eating diets both in and outside the EU. (Source: adapted from https://moneyweek.com/499842/the-economic- consequences-of-veganism December-28-2018) Extract B Businesses benefitting from meat-substitute products There is one group for whom the trend towards meat-substitute products is definitely a good thing: processed food manufacturers and retailers. Finest British beef burgers are priced at £6.61 per kg. The ‘fake burger’ (which is made mostly of pea protein) is priced at £21.81 per kg even though the ingredients used to 5 make them, such as mushrooms, peas and palm oil, are cheaper ingredients than meat. Despite high prices, demand continues to rise for these products. This might benefit shareholders, but is it doing any real good for the rest of us? A large food producer bought meat-substitute product maker Vegetarian Butcher in December 2018 and is moving towards a range with more meat-substitute products. 10 In 2017, Nestlé bought Sweet Earth, a California-based maker of vegetarian foods, and it is launching its own meat-substitute ‘Incredible Burger’. It expects its meat-substitute revenues to reach $1 billion by 2029. As subsidies are being cut in every area of farming, consumers ought to be willing to pay higher prices for all food products. If farmers are to stay in business, they need to find 15 additional sources of revenue such as oyster mushrooms, goji berries and basil. (Source: adapted from http://www.financialtimes.com/the-veganism-boom-does- more-for-food-company-profits-than-the-planet February-22-2019)
(c) With reference to the last paragraph of Extract B, explain two factors which are likely to influence price elasticity of supply. (6)
June 2025 · AS Paper 1 · Q6(f) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard government intervention in marketsindirect taxes and subsidies
Data and extracts for question 6Sources for use with SECTION B Read the following figures (1 and 2) and extracts (A and B) before answering Question 6. The market for meat and the growth of vegetarianism Figure 1 The impact of subsidies on farmer income, in England, 2018–2019 (£000 per farm) Cereals Dairy Grazing livestock Pigs Poultry Mixed -20 0 20 40 60 80 100 £000 per farm Key Profit Subsidies (Source: adapted from www.FT.com) Figure 2 Potential impact of indirect tax rises on meat prices per kg, 2023–2030 Before indirect After indirect Type of Meat tax increases tax increases Beef/Veal £24.24 £29.50 Chicken £7.60 £8.63 (Source: adapted from Tax beef, pork and chicken to help climate and health, EU urged – CGTN) Extract A The case for cutting out meat Around a third of Britons are reducing the amount of meat they eat or are cutting it out altogether. Are these consumers right to be cutting out meat? For a start, there are the greenhouse gases released as a result of producing food. The evidence is clear that switching to a plant-based diet would lower emissions. A UK study found that eating a 5 diet high in meat costs 7.2 kg carbon dioxide emissions per day, compared with 3.8 kg for vegetarians. It would also free up land for other uses. Nearly 80% of the world’s farmland is dedicated to rearing animals; a plant-based diet would cut the use of land for agriculture by 76%. The land currently used by grazing livestock could be used for “rewilding”, allowing the environment and animal species destroyed by meat farming to 10 recover. Our health and wealth would be better too. A study published in 2016 modelled what would happen to our health and the global economy if we all switched to vegetarian diets. The economic benefits of switching to plant-based diets could be as much as £700 billion to £1 trillion per year in terms of savings on healthcare costs and lost 15 working days due to ill health. Some economists recommend an increased indirect tax on animal products so that their prices reflect the cost of externalities. This could impact on European farmers, if adopted by the European Union. The tax could bring £35 billion to the EU, with around £15 billion of that going directly to farmers. The 20 rest would be used to bring down VAT on fruit and vegetables, and fund other policies to encourage healthy-eating diets both in and outside the EU. (Source: adapted from https://moneyweek.com/499842/the-economic- consequences-of-veganism December-28-2018) Extract B Businesses benefitting from meat-substitute products There is one group for whom the trend towards meat-substitute products is definitely a good thing: processed food manufacturers and retailers. Finest British beef burgers are priced at £6.61 per kg. The ‘fake burger’ (which is made mostly of pea protein) is priced at £21.81 per kg even though the ingredients used to 5 make them, such as mushrooms, peas and palm oil, are cheaper ingredients than meat. Despite high prices, demand continues to rise for these products. This might benefit shareholders, but is it doing any real good for the rest of us? A large food producer bought meat-substitute product maker Vegetarian Butcher in December 2018 and is moving towards a range with more meat-substitute products. 10 In 2017, Nestlé bought Sweet Earth, a California-based maker of vegetarian foods, and it is launching its own meat-substitute ‘Incredible Burger’. It expects its meat-substitute revenues to reach $1 billion by 2029. As subsidies are being cut in every area of farming, consumers ought to be willing to pay higher prices for all food products. If farmers are to stay in business, they need to find 15 additional sources of revenue such as oyster mushrooms, goji berries and basil. (Source: adapted from http://www.financialtimes.com/the-veganism-boom-does- more-for-food-company-profits-than-the-planet February-22-2019)
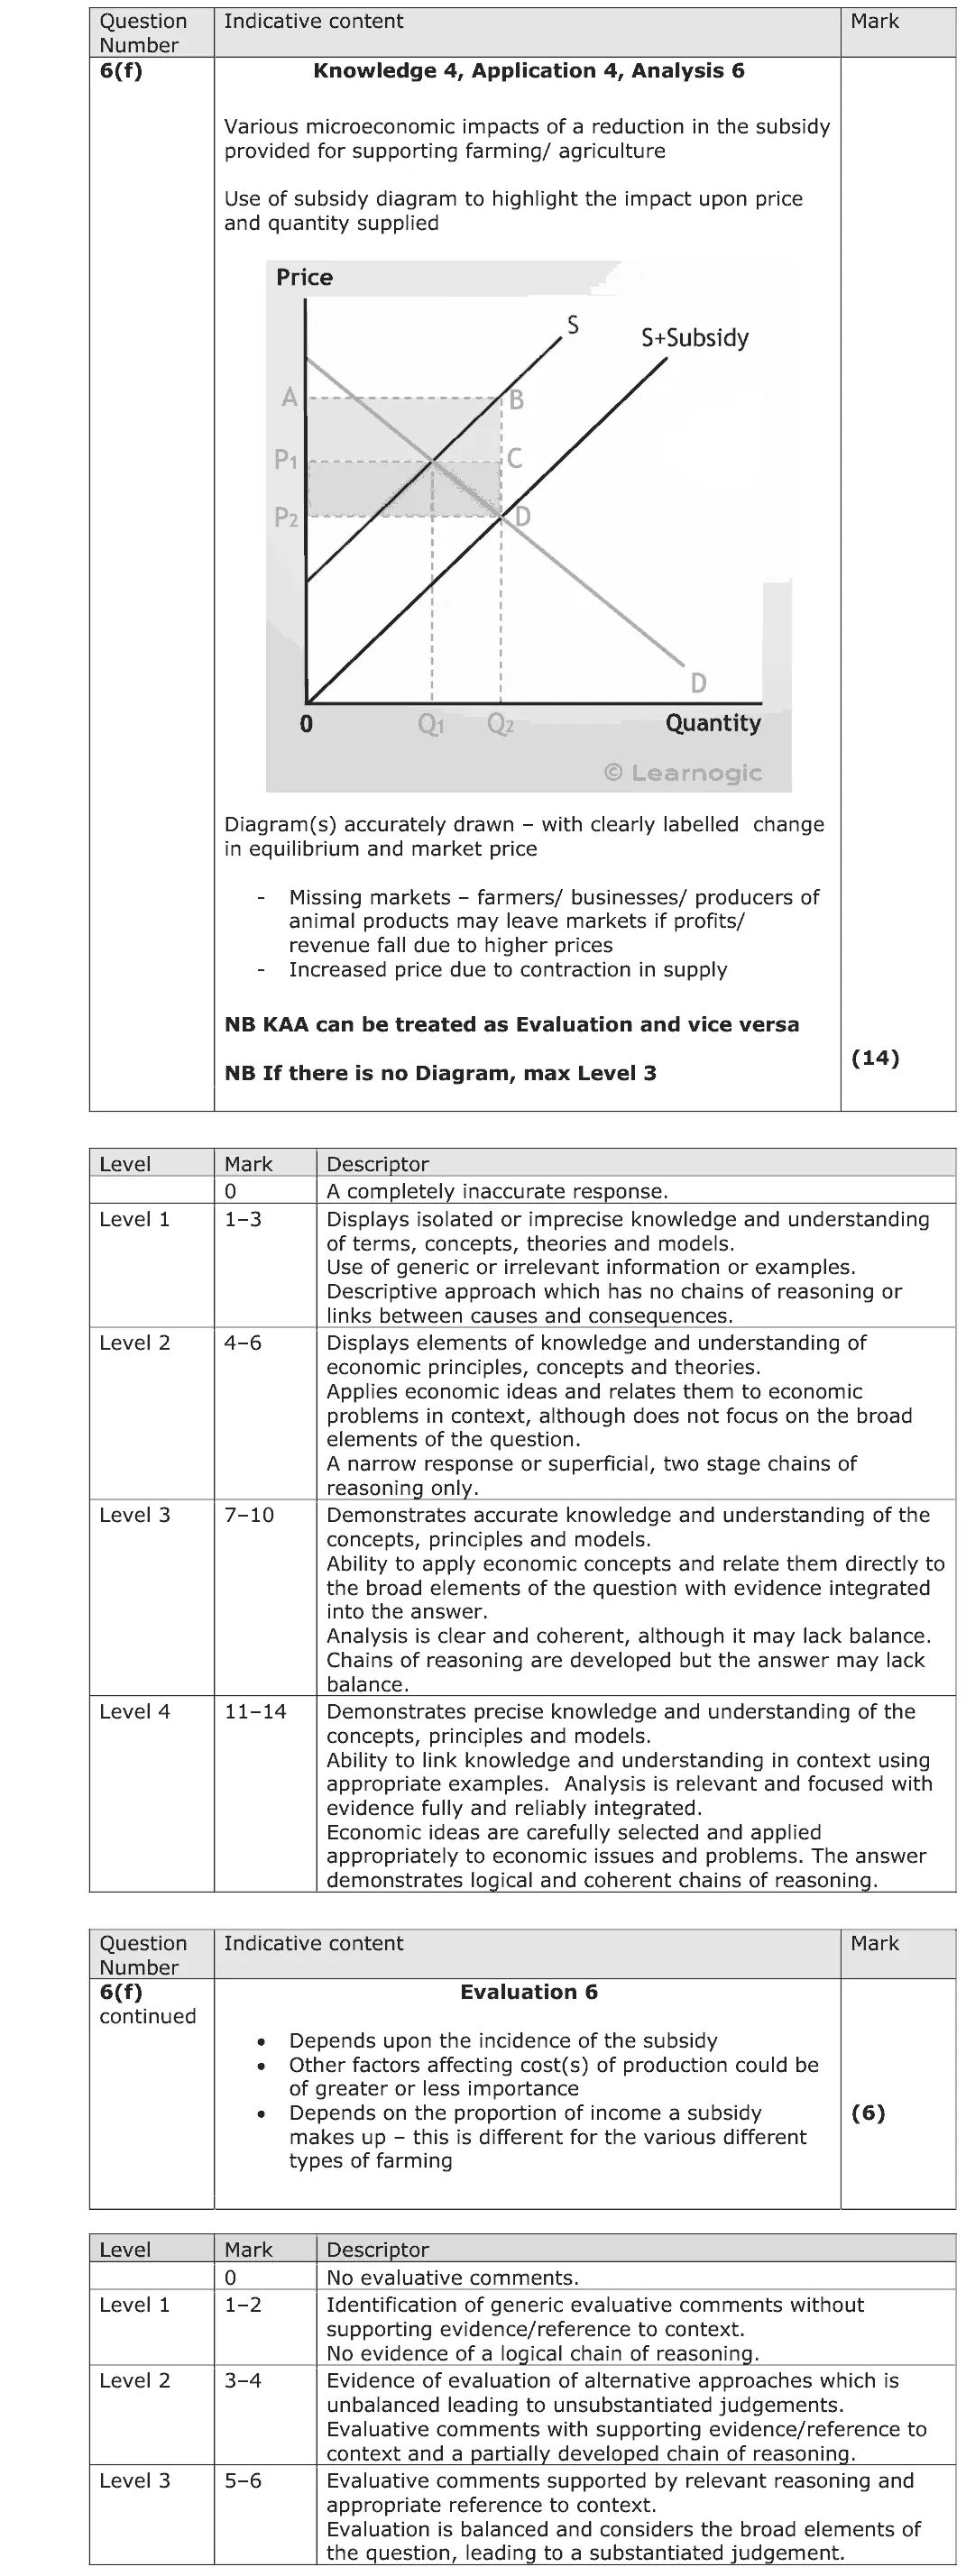
(f) Evaluate the likely microeconomic effects of a reduction in subsidies to farmers of animal products (Figure 1 and Extract B, line 14). Use a relevant diagram to support your answer. (20)
June 2016 · AS Paper 2 · Q2(a) 2 marks AO1=2 Definition Hard measuring economic growth
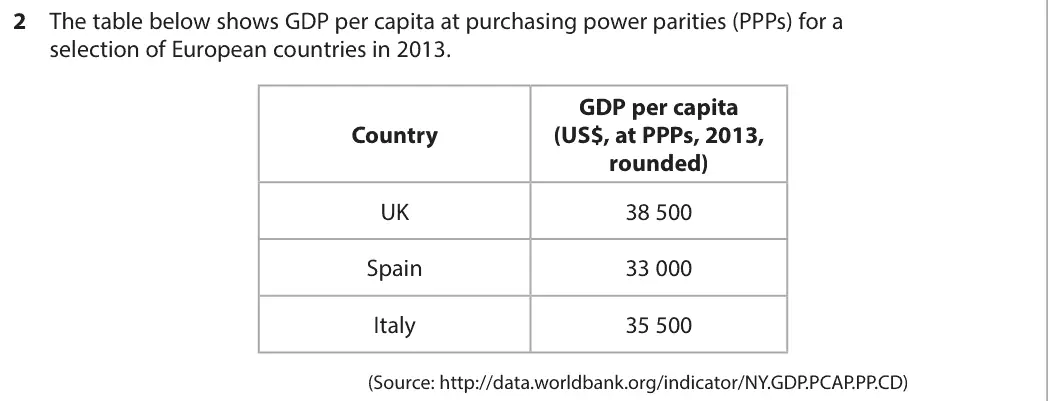
Data and extracts for question 22 The table below shows GDP per capita at purchasing power parities (PPPs) for a selection of European countries in 2013. GDP per capita Country (US$, at PPPs, 2013, rounded) UK 38 500 Spain 33 000 Italy 35 500 (Source: http://data.worldbank.org/indicator/NY.GDP.PCAP.PP.CD)
(a) Define the term ‘purchasing power parities’. (2)
June 2018 · AS Paper 2 · Q4(a) 1 mark AO1=1 Definition Hard aggregate demand
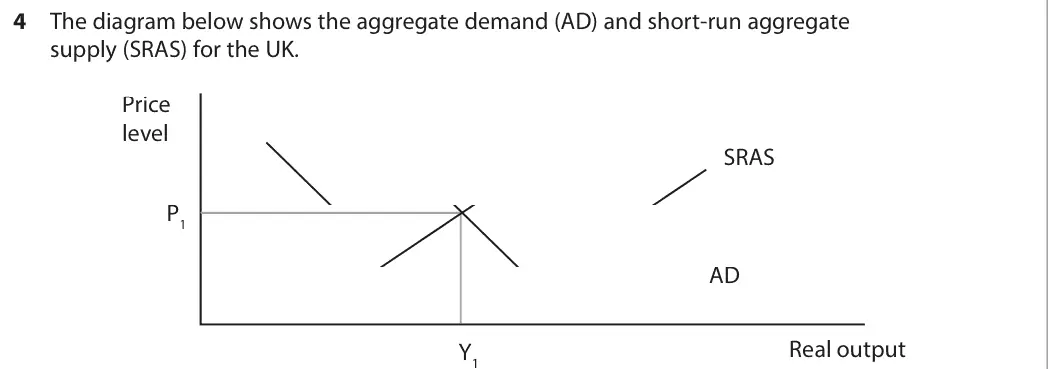
Data and extracts for question 44 The diagram below shows the aggregate demand (AD) and short-run aggregate supply (SRAS) for the UK. Price level SRAS P1 AD Real output Y1
(a) Define the term ‘aggregate demand’. (1)
June 2018 · AS Paper 2 · Q6(g) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard inflationmacroeconomic objectives
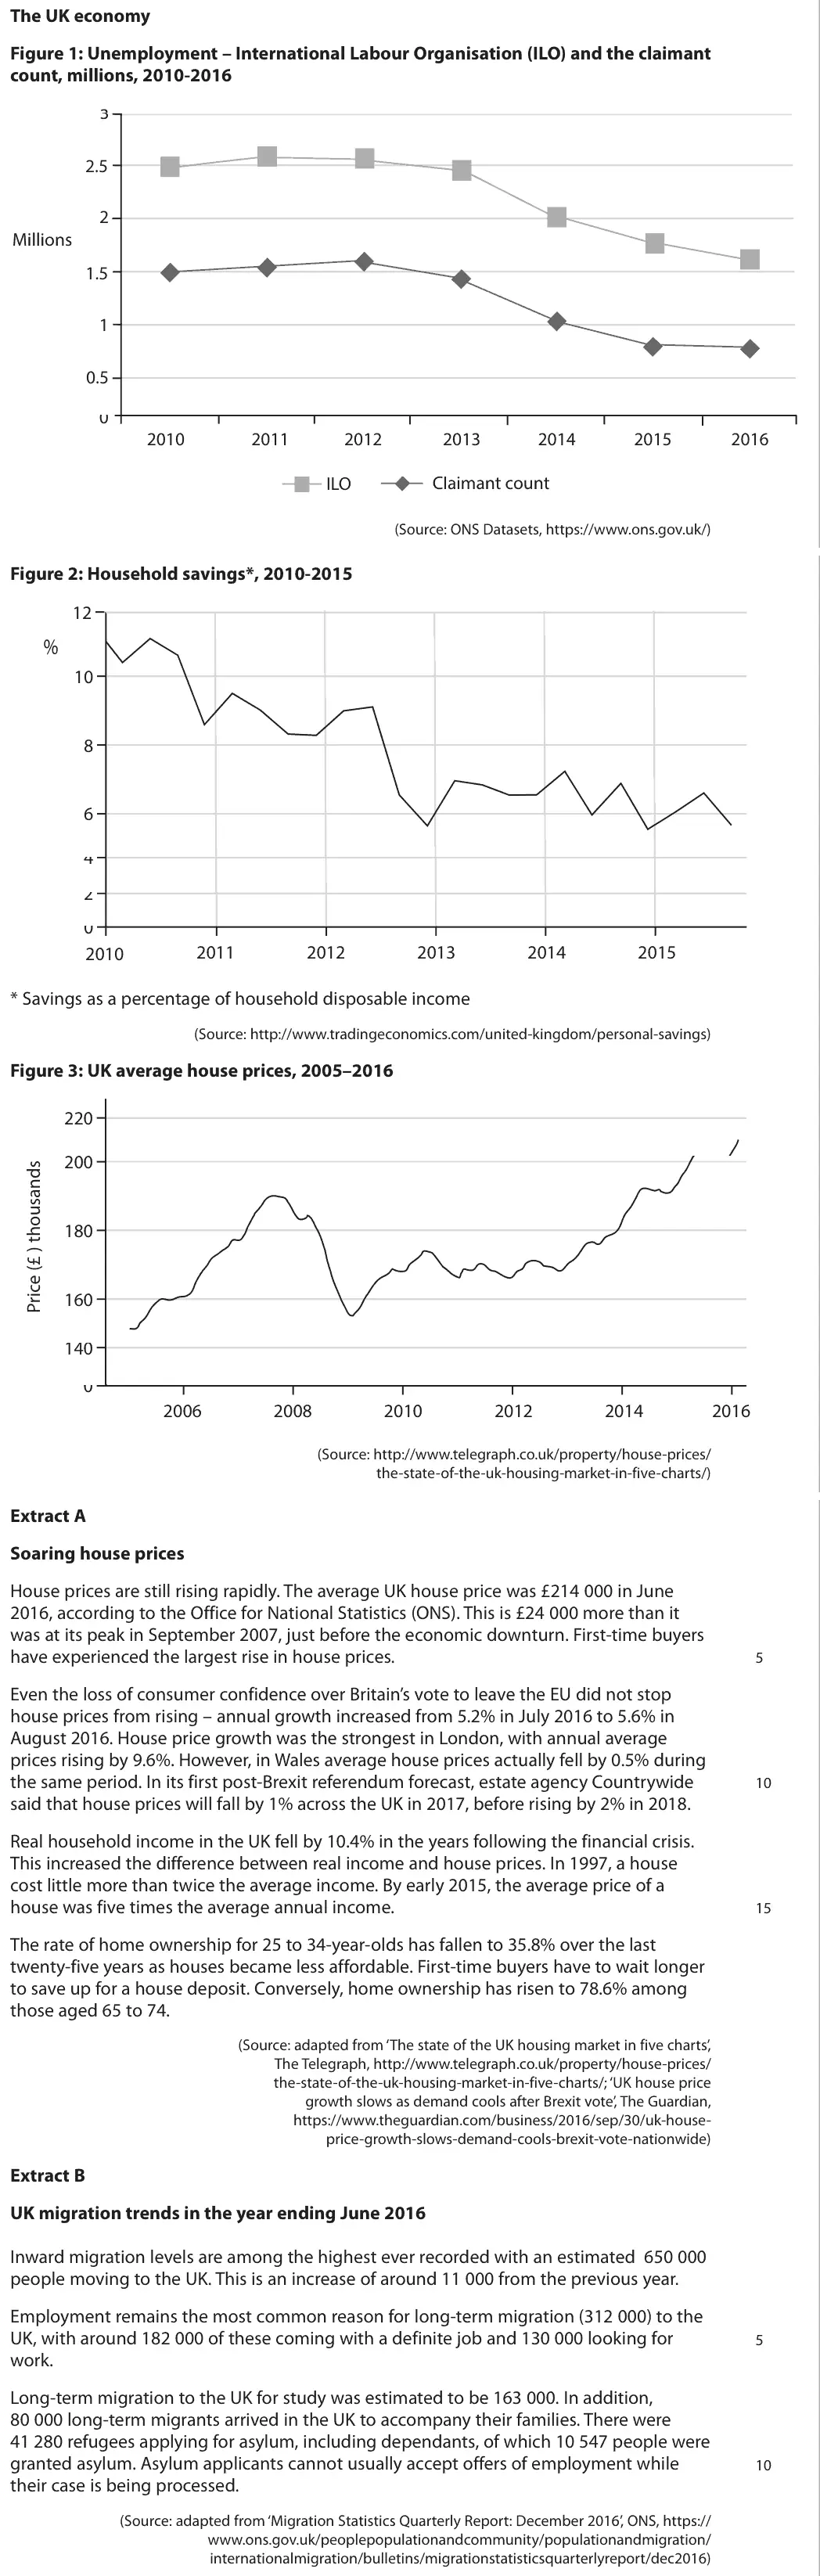
Data and extracts for question 6The UK economy Figure 1: Unemployment – International Labour Organisation (ILO) and the claimant count, millions, 2010-2016 3 2.5 2 Millions 1.5 1 0.5 0 2010 2011 2012 2013 2014 2015 2016 ILO Claimant count (Source: ONS Datasets, https://www.ons.gov.uk/) Figure 2: Household savings*, 2010-2015 12 % 10 8 6 4 2 0 2011 2012 2013 2014 2015 2010 * Savings as a percentage of household disposable income (Source: http://www.tradingeconomics.com/united-kingdom/personal-savings) Figure 3: UK average house prices, 2005–2016 220 200 180 160 140 0 2006 2008 2010 2012 2014 2016 (Source: http://www.telegraph.co.uk/property/house-prices/ the-state-of-the-uk-housing-market-in-five-charts/) Extract A Soaring house prices House prices are still rising rapidly. The average UK house price was £214 000 in June 2016, according to the Office for National Statistics (ONS). This is £24 000 more than it was at its peak in September 2007, just before the economic downturn. First-time buyers have experienced the largest rise in house prices. 5 Even the loss of consumer confidence over Britain’s vote to leave the EU did not stop house prices from rising – annual growth increased from 5.2% in July 2016 to 5.6% in August 2016. House price growth was the strongest in London, with annual average prices rising by 9.6%. However, in Wales average house prices actually fell by 0.5% during the same period. In its first post-Brexit referendum forecast, estate agency Countrywide 10 said that house prices will fall by 1% across the UK in 2017, before rising by 2% in 2018. Real household income in the UK fell by 10.4% in the years following the financial crisis. This increased the difference between real income and house prices. In 1997, a house cost little more than twice the average income. By early 2015, the average price of a house was five times the average annual income. 15 The rate of home ownership for 25 to 34-year-olds has fallen to 35.8% over the last twenty-five years as houses became less affordable. First-time buyers have to wait longer to save up for a house deposit. Conversely, home ownership has risen to 78.6% among those aged 65 to 74. (Source: adapted from ‘The state of the UK housing market in five charts’, The Telegraph, http://www.telegraph.co.uk/property/house-prices/ the-state-of-the-uk-housing-market-in-five-charts/; ‘UK house price growth slows as demand cools after Brexit vote’, The Guardian, https://www.theguardian.com/business/2016/sep/30/uk-house- price-growth-slows-demand-cools-brexit-vote-nationwide) Extract B UK migration trends in the year ending June 2016 Inward migration levels are among the highest ever recorded with an estimated 650 000 people moving to the UK. This is an increase of around 11 000 from the previous year. Employment remains the most common reason for long-term migration (312 000) to the UK, with around 182 000 of these coming with a definite job and 130 000 looking for 5 work. Long-term migration to the UK for study was estimated to be 163 000. In addition, 80 000 long-term migrants arrived in the UK to accompany their families. There were 41 280 refugees applying for asylum, including dependants, of which 10 547 people were granted asylum. Asylum applicants cannot usually accept offers of employment while 10 their case is being processed. (Source: adapted from ‘Migration Statistics Quarterly Report: December 2016’, ONS, https:// www.ons.gov.uk/peoplepopulationandcommunity/populationandmigration/ internationalmigration/bulletins/migrationstatisticsquarterlyreport/dec2016)
(g) Evaluate the likely impact of high inflation on the UK government’s macroeconomic objectives. (20)
June 2019 · AS Paper 2 · Q4(a) 1 mark AO1=1 Definition Hard inflation
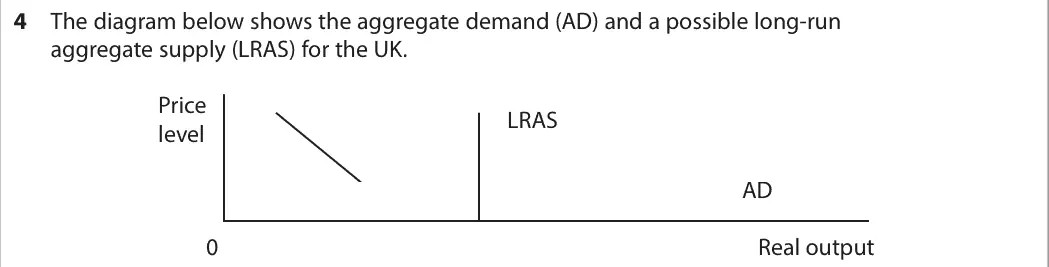
Data and extracts for question 44 The diagram below shows the aggregate demand (AD) and a possible long-run aggregate supply (LRAS) for the UK. Price LRAS level AD 0 Real output
(a) Define the term ‘price level’. (1)
June 2019 · AS Paper 2 · Q6(g) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard macroeconomic objectives
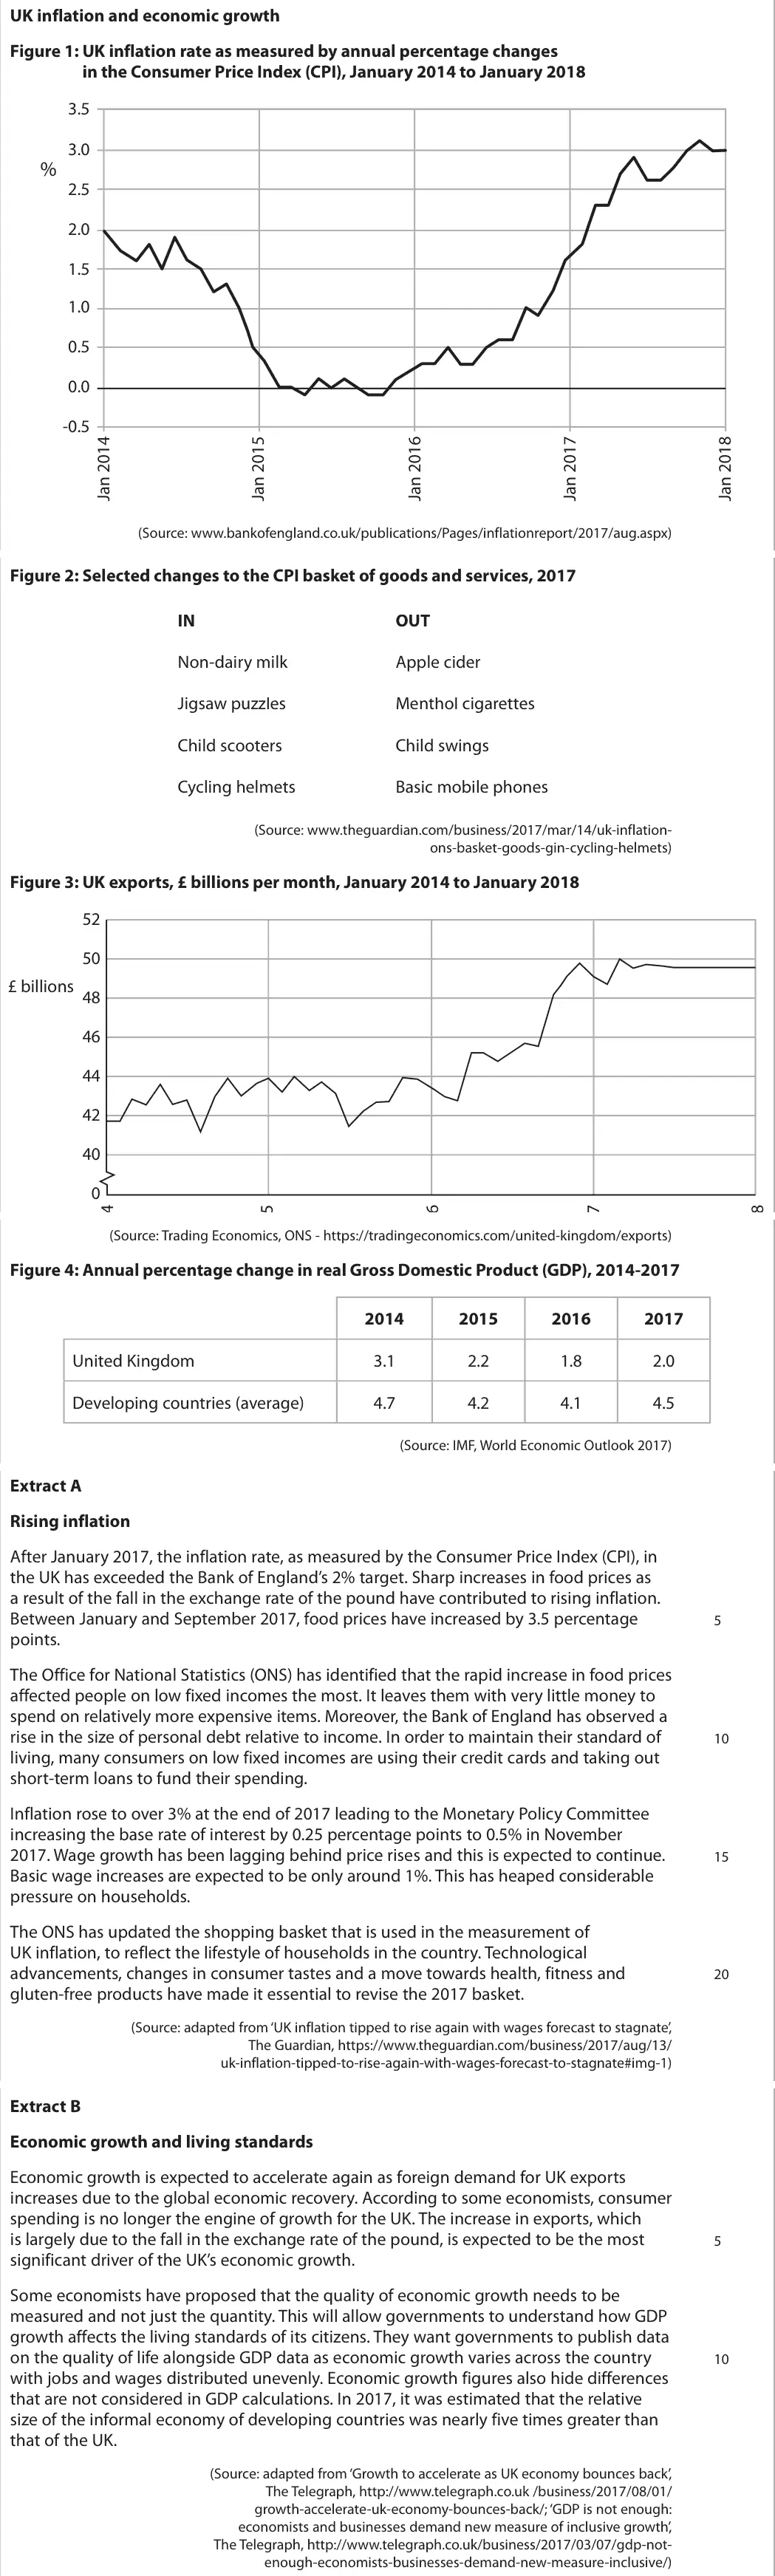
Data and extracts for question 6UK inflation and economic growth Figure 1: UK inflation rate as measured by annual percentage changes in the Consumer Price Index (CPI), January 2014 to January 2018 3.5 3.0 % 2.5 2.0 1.5 1.0 0.5 0.0 -0.5 (Source: www.bankofengland.co.uk/publications/Pages/inflationreport/2017/aug.aspx) Figure 2: Selected changes to the CPI basket of goods and services, 2017 IN OUT Non-dairy milk Apple cider Jigsaw puzzles Menthol cigarettes Child scooters Child swings Cycling helmets Basic mobile phones (Source: www.theguardian.com/business/2017/mar/14/uk-inflation- ons-basket-goods-gin-cycling-helmets) Figure 3: UK exports, £ billions per month, January 2014 to January 2018 52 50 £ billions 48 46 44 42 40 0 (Source: Trading Economics, ONS - https://tradingeconomics.com/united-kingdom/exports) Figure 4: Annual percentage change in real Gross Domestic Product (GDP), 2014-2017 2014 2015 2016 2017 United Kingdom 3.1 2.2 1.8 2.0 Developing countries (average) 4.7 4.2 4.1 4.5 (Source: IMF, World Economic Outlook 2017) Extract A Rising inflation After January 2017, the inflation rate, as measured by the Consumer Price Index (CPI), in the UK has exceeded the Bank of England’s 2% target. Sharp increases in food prices as a result of the fall in the exchange rate of the pound have contributed to rising inflation. Between January and September 2017, food prices have increased by 3.5 percentage 5 points. The Office for National Statistics (ONS) has identified that the rapid increase in food prices affected people on low fixed incomes the most. It leaves them with very little money to spend on relatively more expensive items. Moreover, the Bank of England has observed a rise in the size of personal debt relative to income. In order to maintain their standard of 10 living, many consumers on low fixed incomes are using their credit cards and taking out short-term loans to fund their spending. Inflation rose to over 3% at the end of 2017 leading to the Monetary Policy Committee increasing the base rate of interest by 0.25 percentage points to 0.5% in November 2017. Wage growth has been lagging behind price rises and this is expected to continue. 15 Basic wage increases are expected to be only around 1%. This has heaped considerable pressure on households. The ONS has updated the shopping basket that is used in the measurement of UK inflation, to reflect the lifestyle of households in the country. Technological advancements, changes in consumer tastes and a move towards health, fitness and 20 gluten-free products have made it essential to revise the 2017 basket. (Source: adapted from ‘UK inflation tipped to rise again with wages forecast to stagnate’, The Guardian, https://www.theguardian.com/business/2017/aug/13/ uk-inflation-tipped-to-rise-again-with-wages-forecast-to-stagnate#img-1) Extract B Economic growth and living standards Economic growth is expected to accelerate again as foreign demand for UK exports increases due to the global economic recovery. According to some economists, consumer spending is no longer the engine of growth for the UK. The increase in exports, which is largely due to the fall in the exchange rate of the pound, is expected to be the most 5 significant driver of the UK’s economic growth. Some economists have proposed that the quality of economic growth needs to be measured and not just the quantity. This will allow governments to understand how GDP growth affects the living standards of its citizens. They want governments to publish data on the quality of life alongside GDP data as economic growth varies across the country 10 with jobs and wages distributed unevenly. Economic growth figures also hide differences that are not considered in GDP calculations. In 2017, it was estimated that the relative size of the informal economy of developing countries was nearly five times greater than that of the UK. (Source: adapted from ‘Growth to accelerate as UK economy bounces back’, The Telegraph, http://www.telegraph.co.uk /business/2017/08/01/ growth-accelerate-uk-economy-bounces-back/; ‘GDP is not enough: economists and businesses demand new measure of inclusive growth’, The Telegraph, http://www.telegraph.co.uk/business/2017/03/07/gdp-not- enough-economists-businesses-demand-new-measure-inclusive/)
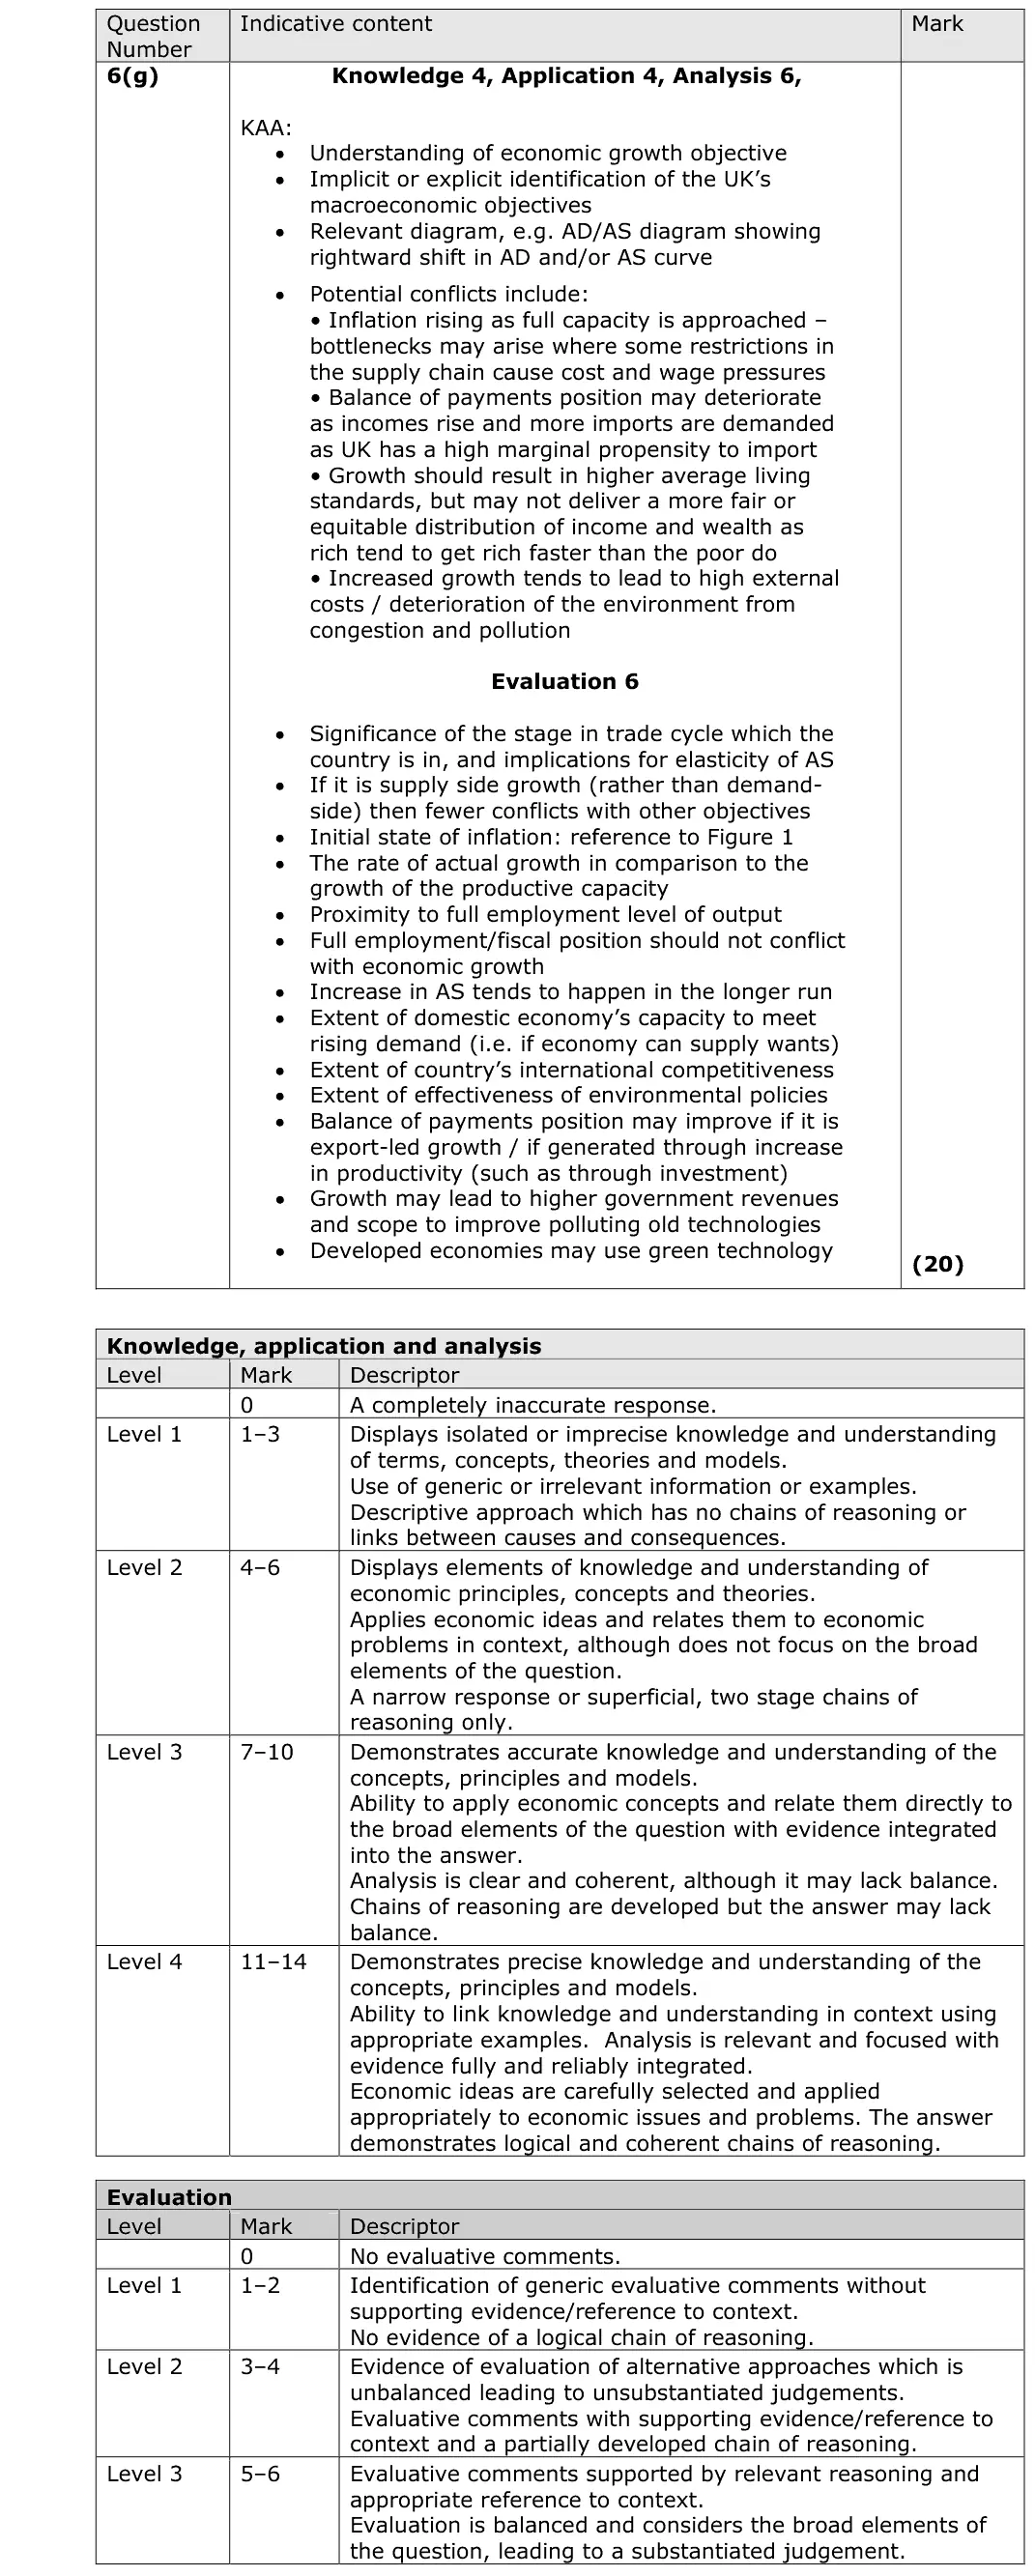
(g) Evaluate the potential conflicts between the objective of economic growth and two other UK macroeconomic objectives. (20)
June 2022 · AS Paper 2 · Q4(a) 1 mark AO1=1 Definition Hard aggregate demand
Data and extracts for question 44 The UK exchange rate changed from £1 = $1.53 in January 2015 to £1 = $1.22 in October 2019.
(a) Define the term ‘exchange rate’. (1)
June 2022 · AS Paper 2 · Q6(g) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard supply side policies
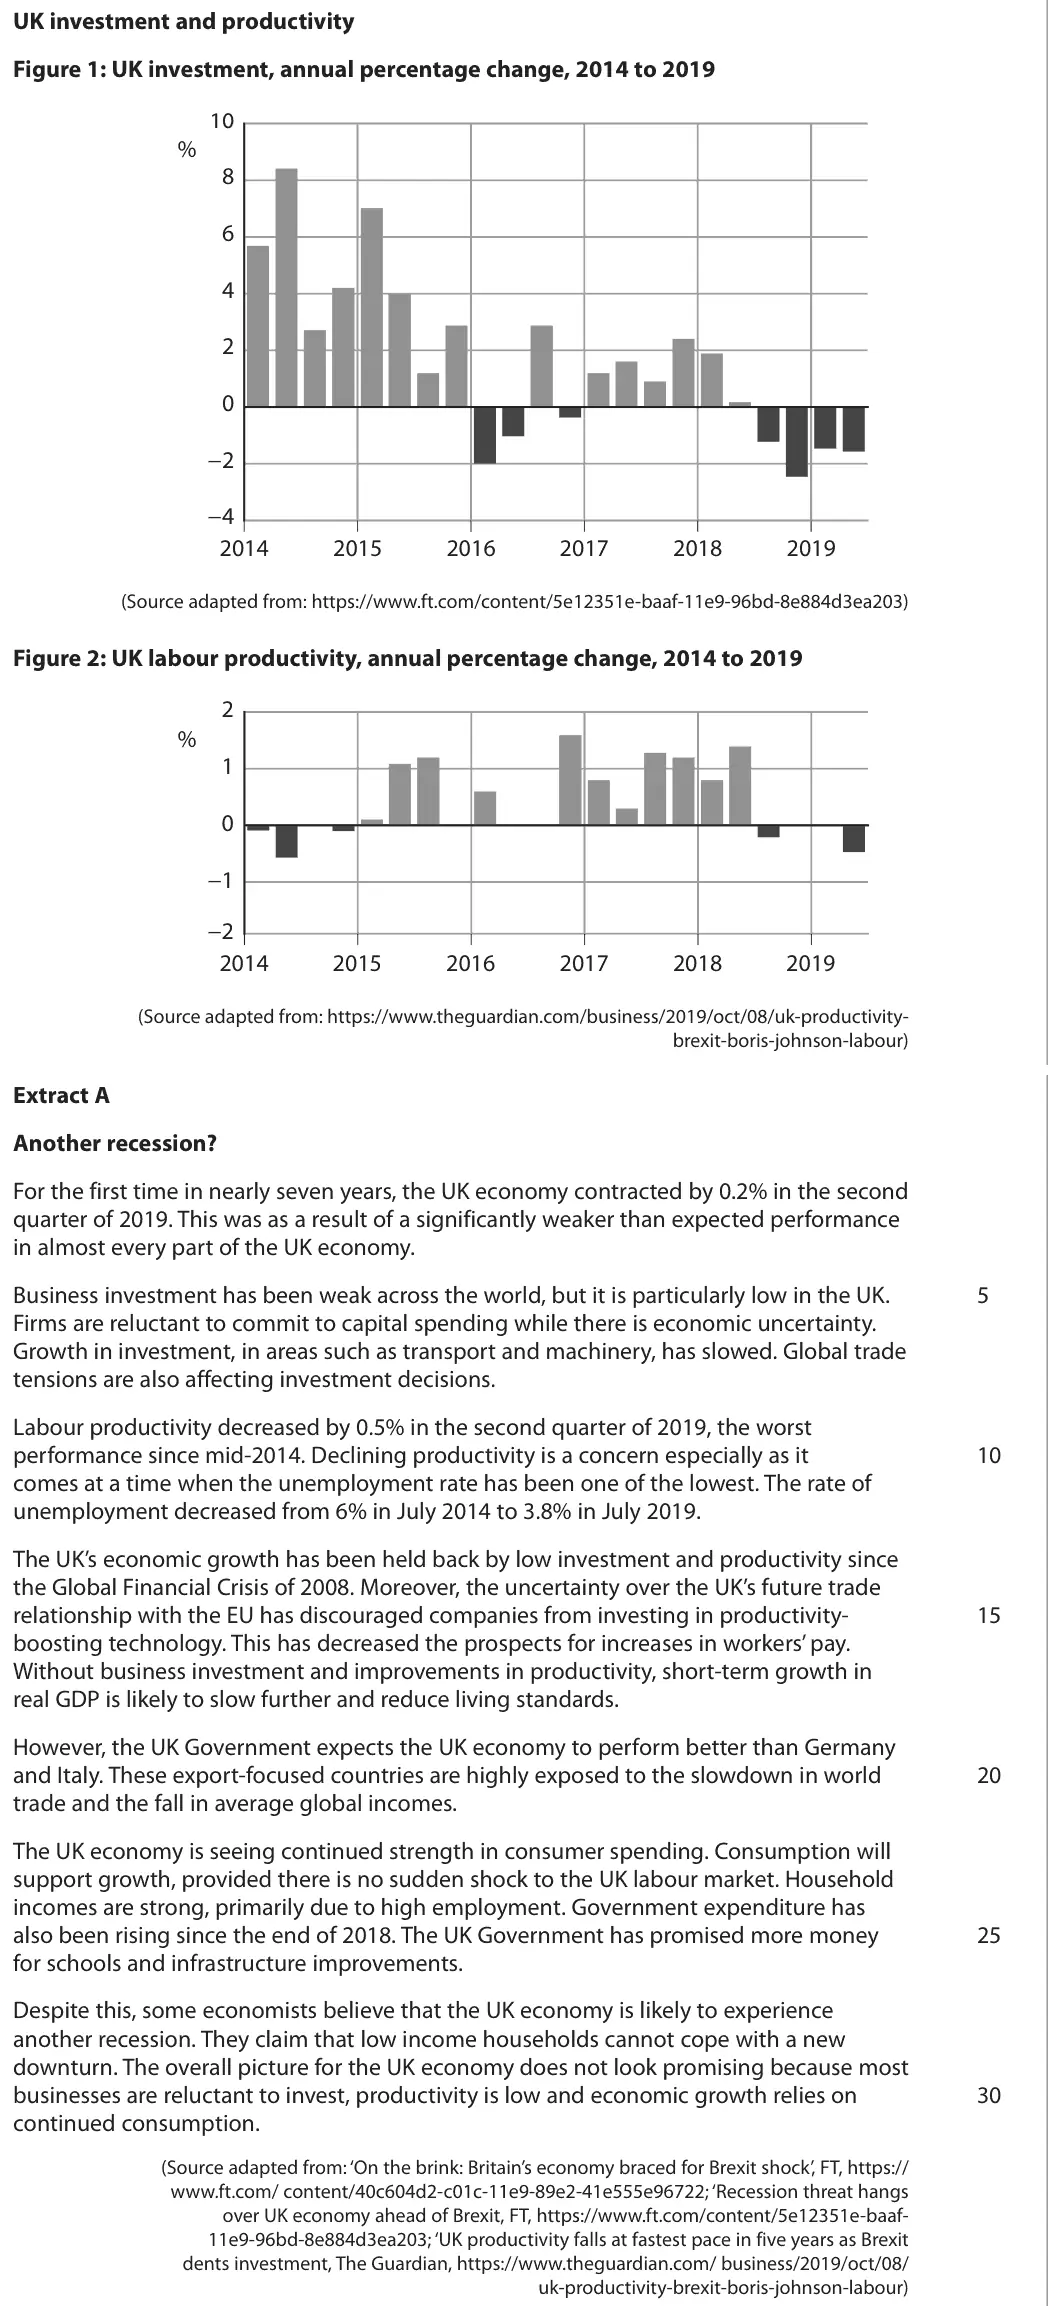
Data and extracts for question 6UK investment and productivity Figure 1: UK investment, annual percentage change, 2014 to 2019 10 % 8 6 4 2 0 -2 -4 2014 2015 2016 2017 2018 2019 (Source adapted from: https://www.ft.com/content/5e12351e-baaf-11e9-96bd-8e884d3ea203) Figure 2: UK labour productivity, annual percentage change, 2014 to 2019 2 % 1 0 -1 -2 2014 2015 2016 2017 2018 2019 (Source adapted from: https://www.theguardian.com/business/2019/oct/08/uk-productivity- brexit-boris-johnson-labour) Extract A Another recession? For the first time in nearly seven years, the UK economy contracted by 0.2% in the second quarter of 2019. This was as a result of a significantly weaker than expected performance in almost every part of the UK economy. Business investment has been weak across the world, but it is particularly low in the UK. 5 Firms are reluctant to commit to capital spending while there is economic uncertainty. Growth in investment, in areas such as transport and machinery, has slowed. Global trade tensions are also affecting investment decisions. Labour productivity decreased by 0.5% in the second quarter of 2019, the worst performance since mid-2014. Declining productivity is a concern especially as it 10 comes at a time when the unemployment rate has been one of the lowest. The rate of unemployment decreased from 6% in July 2014 to 3.8% in July 2019. The UK’s economic growth has been held back by low investment and productivity since the Global Financial Crisis of 2008. Moreover, the uncertainty over the UK’s future trade relationship with the EU has discouraged companies from investing in productivity- 15 boosting technology. This has decreased the prospects for increases in workers’ pay. Without business investment and improvements in productivity, short-term growth in real GDP is likely to slow further and reduce living standards. However, the UK Government expects the UK economy to perform better than Germany and Italy. These export-focused countries are highly exposed to the slowdown in world 20 trade and the fall in average global incomes. The UK economy is seeing continued strength in consumer spending. Consumption will support growth, provided there is no sudden shock to the UK labour market. Household incomes are strong, primarily due to high employment. Government expenditure has also been rising since the end of 2018. The UK Government has promised more money 25 for schools and infrastructure improvements. Despite this, some economists believe that the UK economy is likely to experience another recession. They claim that low income households cannot cope with a new downturn. The overall picture for the UK economy does not look promising because most businesses are reluctant to invest, productivity is low and economic growth relies on 30 continued consumption. (Source adapted from: ‘On the brink: Britain’s economy braced for Brexit shock’, FT, https:// www.ft.com/ content/40c604d2-c01c-11e9-89e2-41e555e96722; ‘Recession threat hangs over UK economy ahead of Brexit, FT, https://www.ft.com/content/5e12351e-baaf- 11e9-96bd-8e884d3ea203; ‘UK productivity falls at fastest pace in five years as Brexit dents investment, The Guardian, https://www.theguardian.com/ business/2019/oct/08/ uk-productivity-brexit-boris-johnson-labour)
(g) Evaluate the supply-side policies the UK Government could use to increase the UK’s productivity. (20)
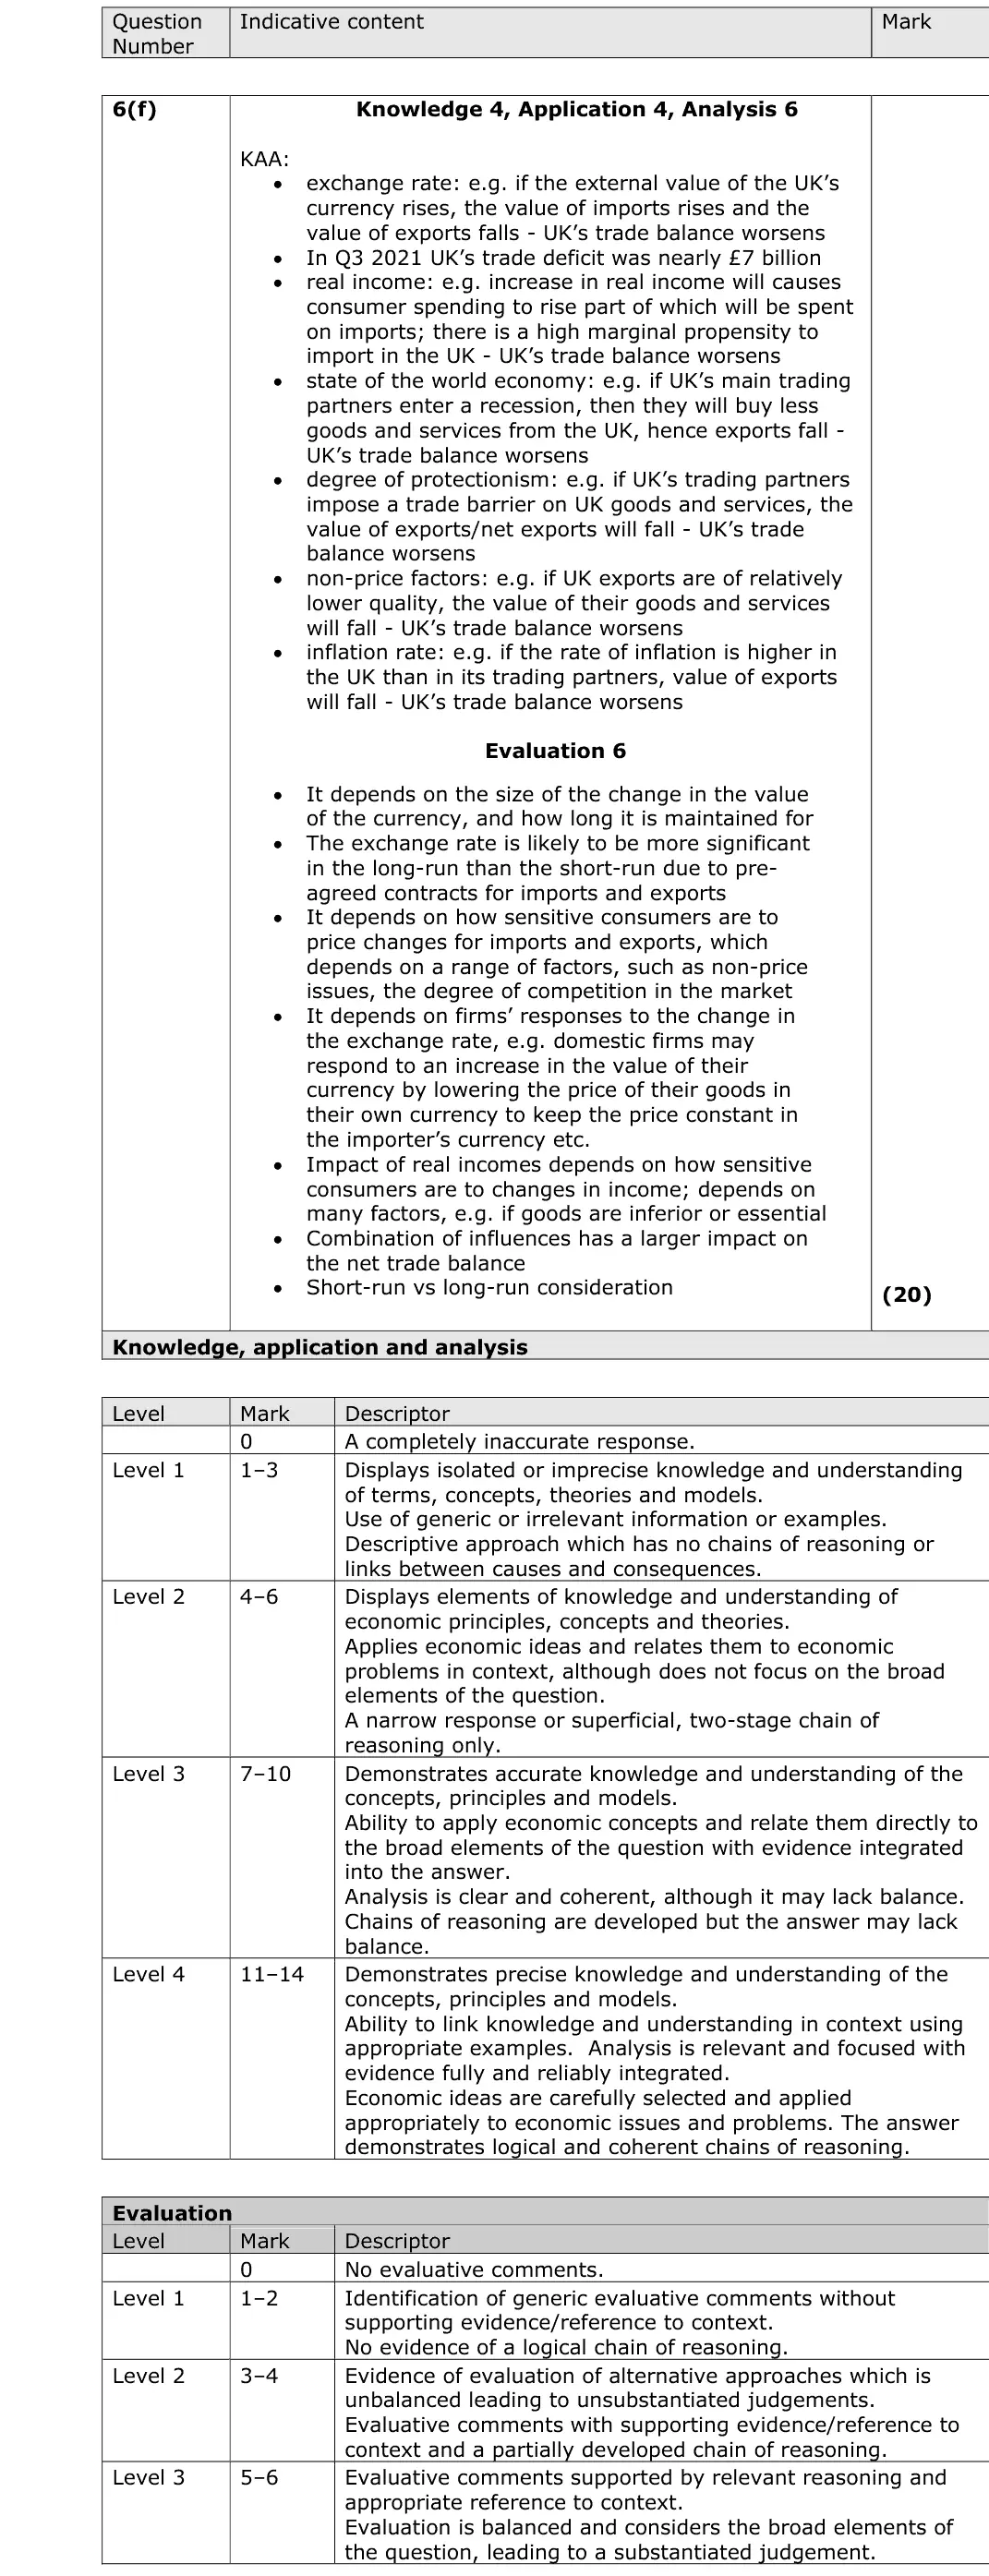
June 2023 · AS Paper 2 · Q6(f) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or Hard aggregate demandbalance of payments
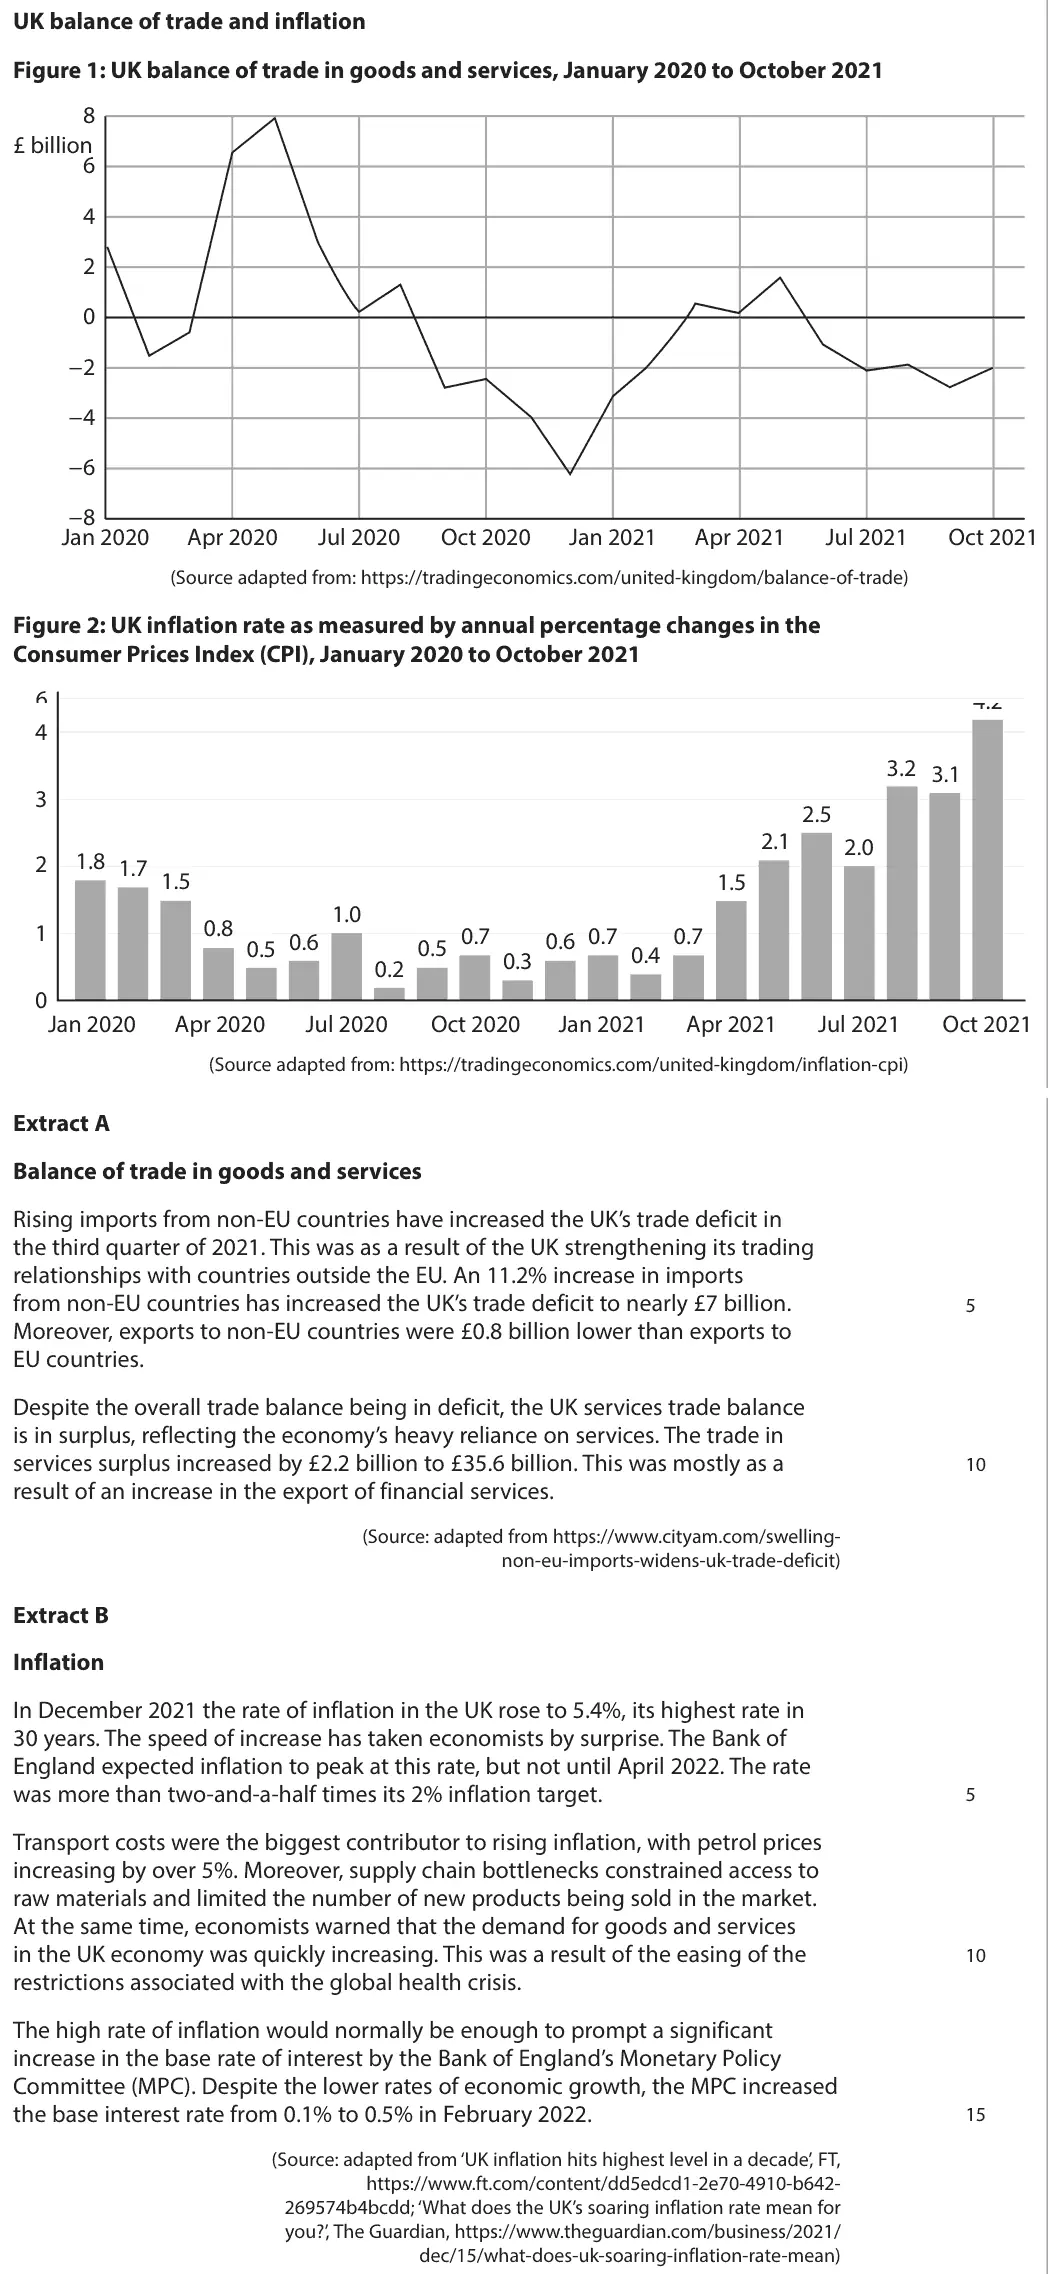
Data and extracts for question 6UK balance of trade and inflation Figure 1: UK balance of trade in goods and services, January 2020 to October 2021 8 £ billion 6 4 2 0 -2 -4 -6 -8 Jan 2020 Apr 2020 Jul 2020 Oct 2020 Jan 2021 Apr 2021 Jul 2021 Oct 2021 (Source adapted from: https://tradingeconomics.com/united-kingdom/balance-of-trade) Figure 2: UK inflation rate as measured by annual percentage changes in the Consumer Prices Index (CPI), January 2020 to October 2021 6 % 5 4.2 4 3.2 3.1 3 2.5 2.1 2.0 1.8 2 1.7 1.5 1.5 1.0 0.8 1 0.7 0.7 0.6 0.7 0.4 0.5 0.6 0.5 0.3 0.2 0 Jan 2020 Apr 2020 Jul 2020 Oct 2020 Jan 2021 Apr 2021 Jul 2021 Oct 2021 (Source adapted from: https://tradingeconomics.com/united-kingdom/inflation-cpi) Extract A Balance of trade in goods and services Rising imports from non-EU countries have increased the UK’s trade deficit in the third quarter of 2021. This was as a result of the UK strengthening its trading relationships with countries outside the EU. An 11.2% increase in imports from non-EU countries has increased the UK’s trade deficit to nearly £7 billion. 5 Moreover, exports to non-EU countries were £0.8 billion lower than exports to EU countries. Despite the overall trade balance being in deficit, the UK services trade balance is in surplus, reflecting the economy’s heavy reliance on services. The trade in 10 services surplus increased by £2.2 billion to £35.6 billion. This was mostly as a result of an increase in the export of financial services. (Source: adapted from https://www.cityam.com/swelling- non-eu-imports-widens-uk-trade-deficit) Extract B Inflation In December 2021 the rate of inflation in the UK rose to 5.4%, its highest rate in 30 years. The speed of increase has taken economists by surprise. The Bank of England expected inflation to peak at this rate, but not until April 2022. The rate was more than two-and-a-half times its 2% inflation target. 5 Transport costs were the biggest contributor to rising inflation, with petrol prices increasing by over 5%. Moreover, supply chain bottlenecks constrained access to raw materials and limited the number of new products being sold in the market. At the same time, economists warned that the demand for goods and services in the UK economy was quickly increasing. This was a result of the easing of the 10 restrictions associated with the global health crisis. The high rate of inflation would normally be enough to prompt a significant increase in the base rate of interest by the Bank of England’s Monetary Policy Committee (MPC). Despite the lower rates of economic growth, the MPC increased the base interest rate from 0.1% to 0.5% in February 2022. 15 (Source: adapted from ‘UK inflation hits highest level in a decade’, FT, https://www.ft.com/content/dd5edcd1-2e70-4910-b642- 269574b4bcdd; ‘What does the UK’s soaring inflation rate mean for you?’, The Guardian, https://www.theguardian.com/business/2021/ dec/15/what-does-uk-soaring-inflation-rate-mean)
(f) Evaluate the main influences on the UK’s net trade balance. (20)
June 2024 · AS Paper 2 · Q2(a) 1 mark AO1=1 Definition Hard national income and the multiplier
Data and extracts for question 22 In 2019 the marginal propensity to consume in the UK was estimated to be 0.8.
(a) Define the term ‘marginal propensity to consume’. (1)
June 2024 · AS Paper 2 · Q3(b) 3 marks AO1=1, AO2=1, AO3=1 Short answer Hard unemployment
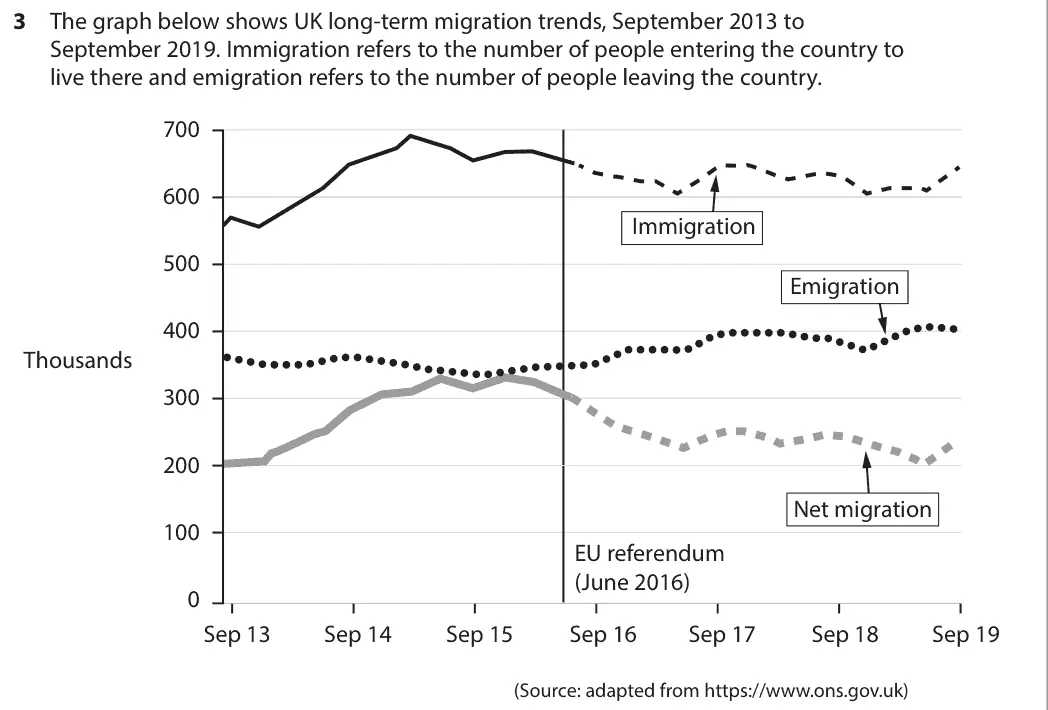
Data and extracts for question 33 The graph below shows UK long-term migration trends, September 2013 to September 2019. Immigration refers to the number of people entering the country to live there and emigration refers to the number of people leaving the country. 700 600 Immigration 500 Emigration 400 Thousands 300 200 Net migration 100 EU referendum (June 2016) 0 Sep 13 Sep 14 Sep 15 Sep 16 Sep 17 Sep 18 Sep 19 (Source: adapted from https://www.ons.gov.uk)
(b) With reference to the above chart, explain one likely effect of migration on employment in the UK. (3)
June 2024 · AS Paper 2 · Q6(e) 15 marks AO1=3, AO2=3, AO3=3, AO4=6 15-mark response Hard fiscal and monetary policy
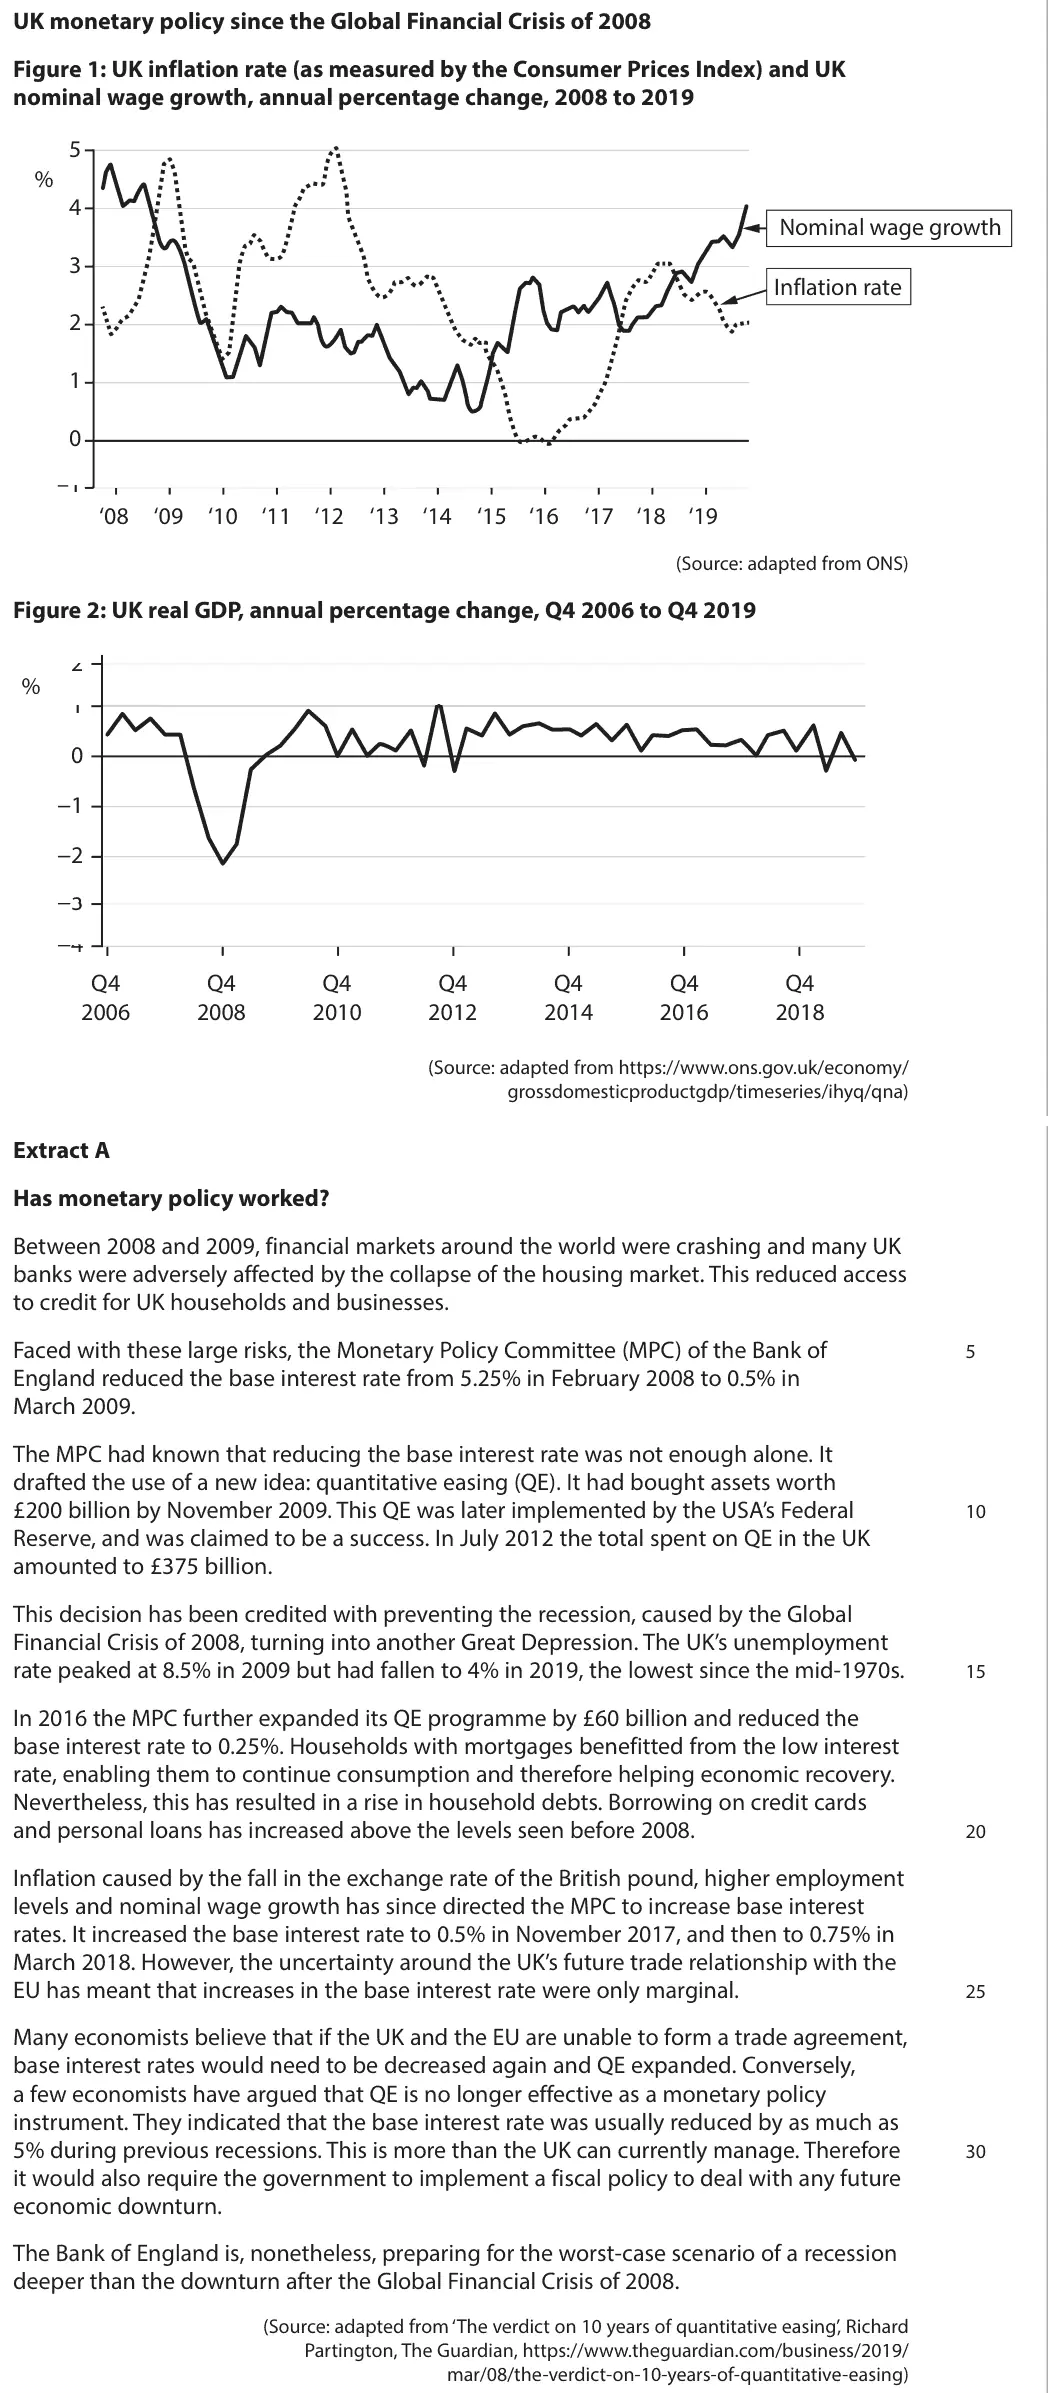
Data and extracts for question 6UK monetary policy since the Global Financial Crisis of 2008 Figure 1: UK inflation rate (as measured by the Consumer Prices Index) and UK nominal wage growth, annual percentage change, 2008 to 2019 5 % 4 Nominal wage growth 3 Inflation rate 2 1 0 –1 ‘08 ‘09 ‘10 ‘11 ‘12 ‘13 ‘14 ‘15 ‘16 ‘17 ‘18 ‘19 (Source: adapted from ONS) Figure 2: UK real GDP, annual percentage change, Q4 2006 to Q4 2019 2 % 1 0 -1 -2 -3 -4 Q4 Q4 Q4 Q4 Q4 Q4 Q4 2006 2008 2010 2012 2014 2016 2018 (Source: adapted from https://www.ons.gov.uk/economy/ grossdomesticproductgdp/timeseries/ihyq/qna) Extract A Has monetary policy worked? Between 2008 and 2009, financial markets around the world were crashing and many UK banks were adversely affected by the collapse of the housing market. This reduced access to credit for UK households and businesses. Faced with these large risks, the Monetary Policy Committee (MPC) of the Bank of 5 England reduced the base interest rate from 5.25% in February 2008 to 0.5% in March 2009. The MPC had known that reducing the base interest rate was not enough alone. It drafted the use of a new idea: quantitative easing (QE). It had bought assets worth £200 billion by November 2009. This QE was later implemented by the USA’s Federal 10 Reserve, and was claimed to be a success. In July 2012 the total spent on QE in the UK amounted to £375 billion. This decision has been credited with preventing the recession, caused by the Global Financial Crisis of 2008, turning into another Great Depression. The UK’s unemployment rate peaked at 8.5% in 2009 but had fallen to 4% in 2019, the lowest since the mid-1970s. 15 In 2016 the MPC further expanded its QE programme by £60 billion and reduced the base interest rate to 0.25%. Households with mortgages benefitted from the low interest rate, enabling them to continue consumption and therefore helping economic recovery. Nevertheless, this has resulted in a rise in household debts. Borrowing on credit cards and personal loans has increased above the levels seen before 2008. 20 Inflation caused by the fall in the exchange rate of the British pound, higher employment levels and nominal wage growth has since directed the MPC to increase base interest rates. It increased the base interest rate to 0.5% in November 2017, and then to 0.75% in March 2018. However, the uncertainty around the UK’s future trade relationship with the EU has meant that increases in the base interest rate were only marginal. 25 Many economists believe that if the UK and the EU are unable to form a trade agreement, base interest rates would need to be decreased again and QE expanded. Conversely, a few economists have argued that QE is no longer effective as a monetary policy instrument. They indicated that the base interest rate was usually reduced by as much as 5% during previous recessions. This is more than the UK can currently manage. Therefore 30 it would also require the government to implement a fiscal policy to deal with any future economic downturn. The Bank of England is, nonetheless, preparing for the worst-case scenario of a recession deeper than the downturn after the Global Financial Crisis of 2008. (Source: adapted from ‘The verdict on 10 years of quantitative easing’, Richard Partington, The Guardian, https://www.theguardian.com/business/2019/ mar/08/the-verdict-on-10-years-of-quantitative-easing)
(e) Discuss factors, apart from changes in real wages, which the MPC may have considered when changing the base interest rate. (15)
June 2025 · AS Paper 2 · Q2(b) 3 marks AO1=1, AO2=1, AO3=1 Short answer Hard aggregate demand
Data and extracts for question 22 The table shows average UK house prices between January 2023 and March 2023. Month and year Average house price (£) January 2023 286 321 February 2023 284 152 March 2023 281 555 (Source: adapted from https://landregistry.data.gov.uk/)
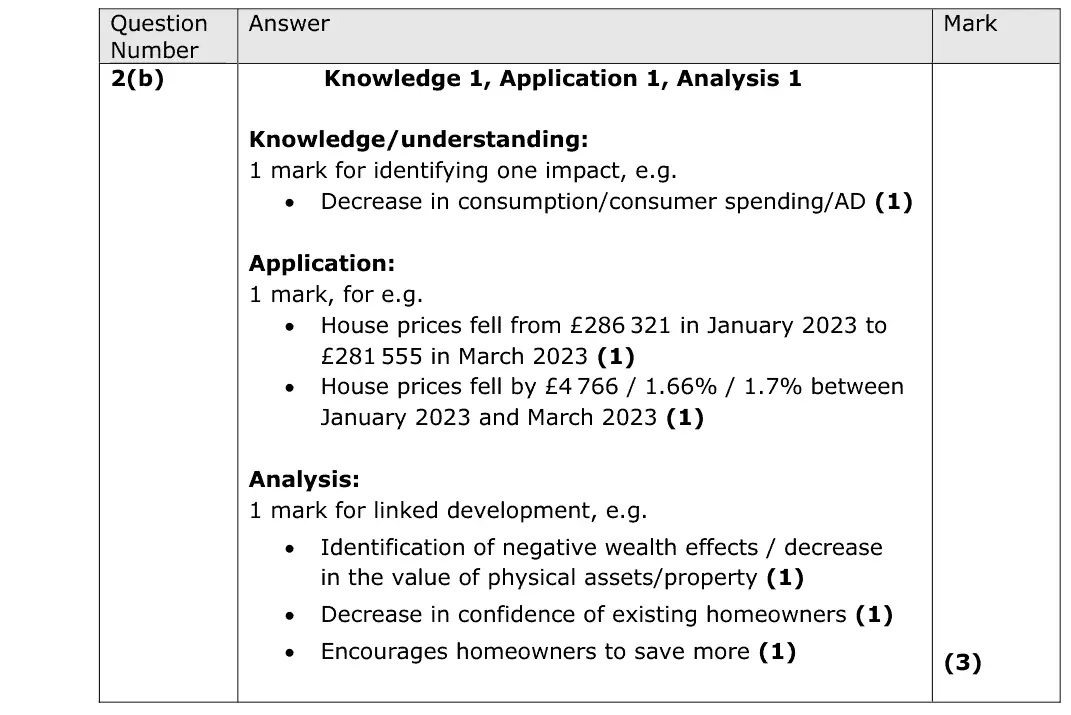
(b) Explain one likely impact of the fall in average UK house prices on existing homeowners between January 2023 and March 2023. Refer to the table on page 4 in your answer. (3)
October 2020 · AS Paper 2 · Q6(e) 15 marks AO1=3, AO2=3, AO3=3, AO4=6 15-mark response Hard economic growth and the trade cycleaggregate supply
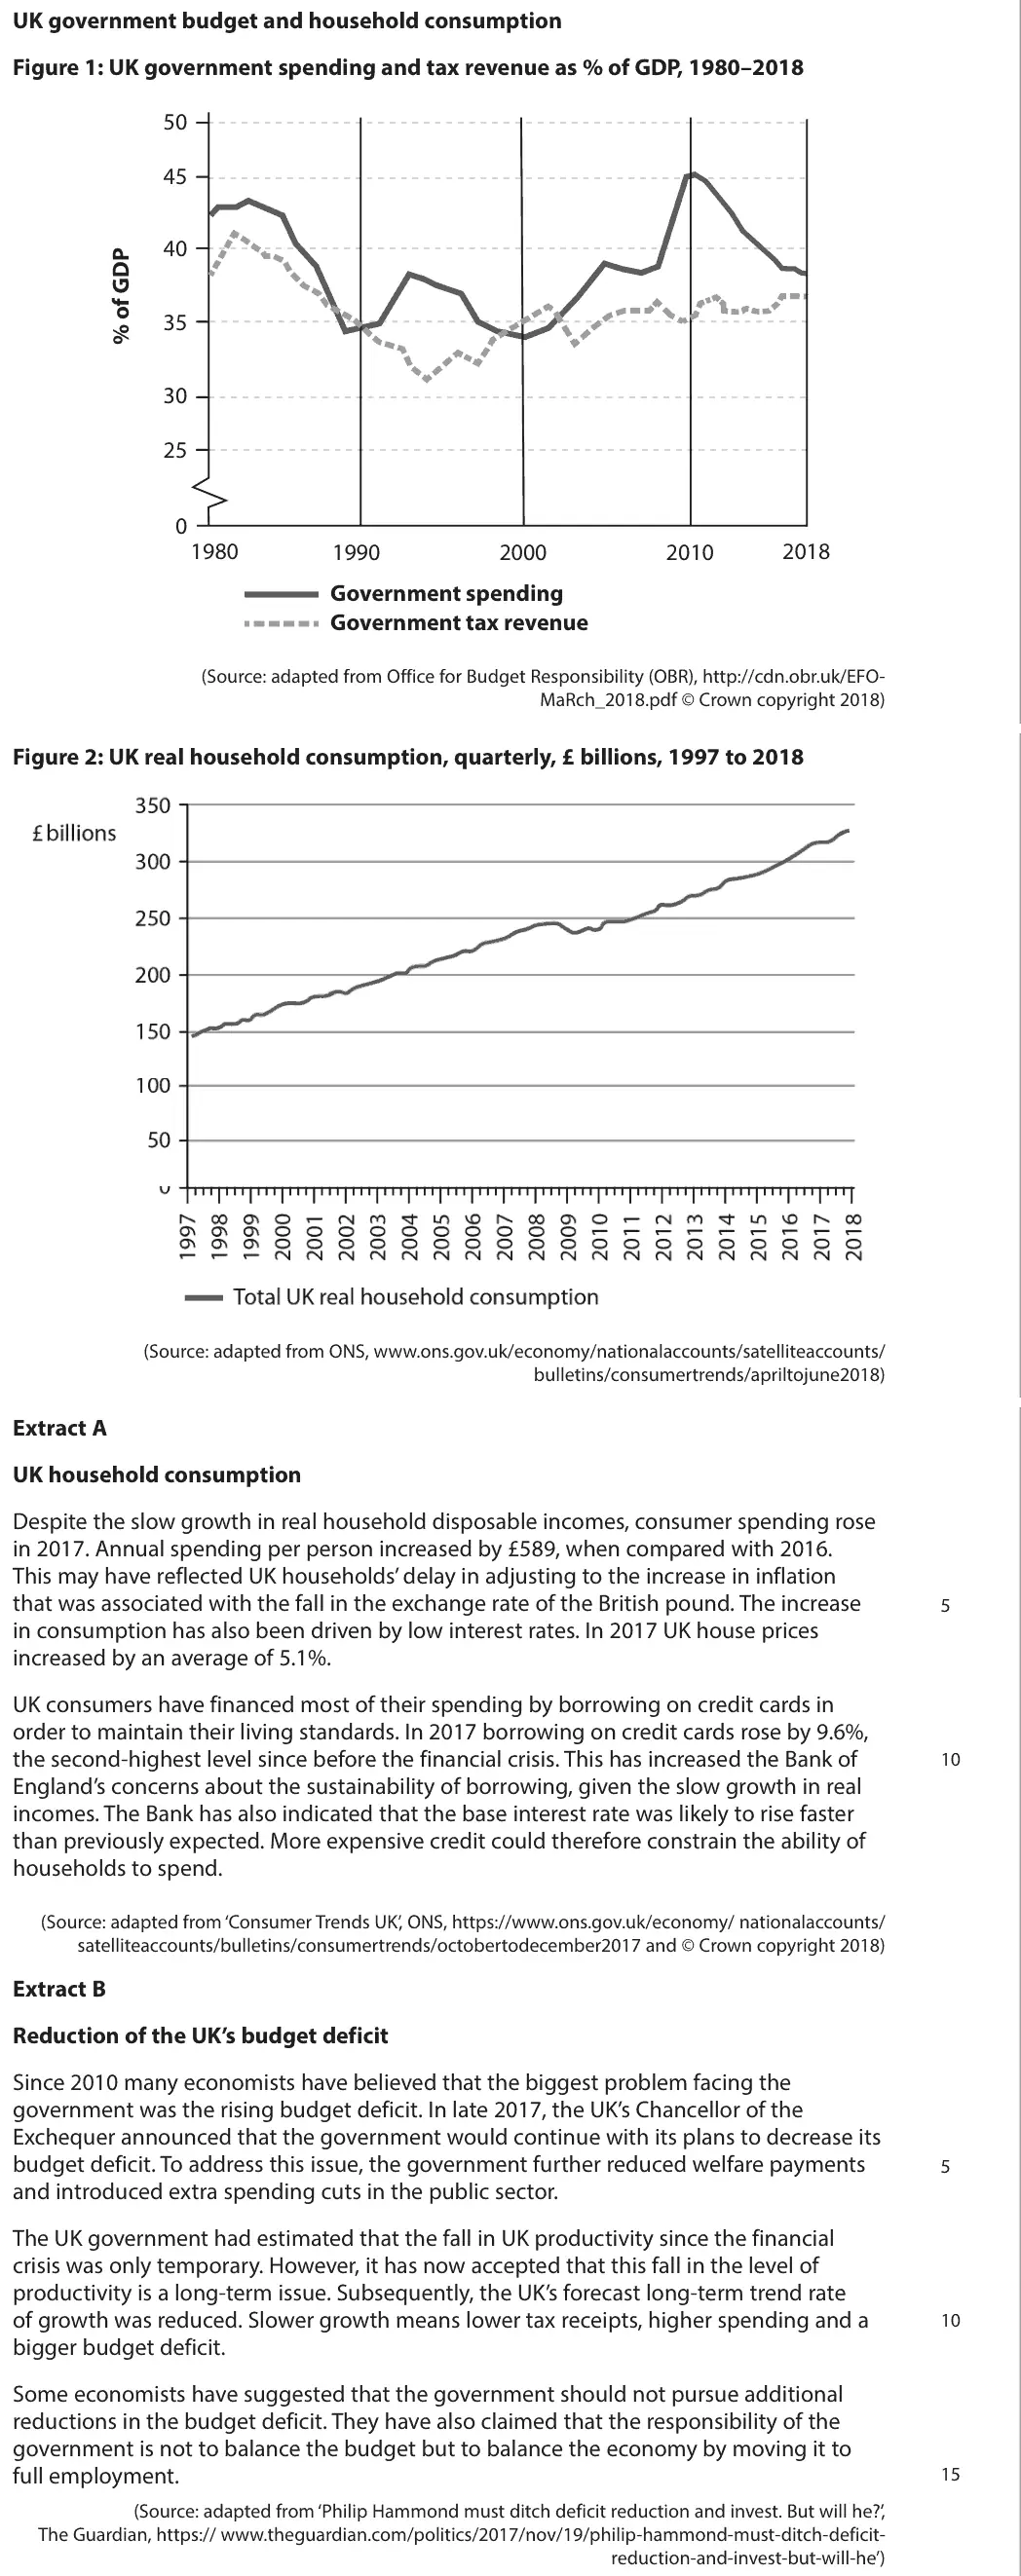
Data and extracts for question 6UK government budget and household consumption Figure 1: UK government spending and tax revenue as % of GDP, 1980–2018 50 45 40 35 30 25 0 1980 2018 1990 2000 2010 Government spending Government tax revenue (Source: adapted from Office for Budget Responsibility (OBR), http://cdn.obr.uk/EFO- MaRch_2018.pdf © Crown copyright 2018) Figure 2: UK real household consumption, quarterly, £ billions, 1997 to 2018 (Source: adapted from ONS, www.ons.gov.uk/economy/nationalaccounts/satelliteaccounts/ bulletins/consumertrends/apriltojune2018) Extract A UK household consumption Despite the slow growth in real household disposable incomes, consumer spending rose in 2017. Annual spending per person increased by £589, when compared with 2016. This may have reflected UK households’ delay in adjusting to the increase in inflation that was associated with the fall in the exchange rate of the British pound. The increase 5 in consumption has also been driven by low interest rates. In 2017 UK house prices increased by an average of 5.1%. UK consumers have financed most of their spending by borrowing on credit cards in order to maintain their living standards. In 2017 borrowing on credit cards rose by 9.6%, the second-highest level since before the financial crisis. This has increased the Bank of 10 England’s concerns about the sustainability of borrowing, given the slow growth in real incomes. The Bank has also indicated that the base interest rate was likely to rise faster than previously expected. More expensive credit could therefore constrain the ability of households to spend. (Source: adapted from ‘Consumer Trends UK’, ONS, https://www.ons.gov.uk/economy/ nationalaccounts/ satelliteaccounts/bulletins/consumertrends/octobertodecember2017 and © Crown copyright 2018) Extract B Reduction of the UK’s budget deficit Since 2010 many economists have believed that the biggest problem facing the government was the rising budget deficit. In late 2017, the UK’s Chancellor of the Exchequer announced that the government would continue with its plans to decrease its budget deficit. To address this issue, the government further reduced welfare payments 5 and introduced extra spending cuts in the public sector. The UK government had estimated that the fall in UK productivity since the financial crisis was only temporary. However, it has now accepted that this fall in the level of productivity is a long-term issue. Subsequently, the UK’s forecast long-term trend rate of growth was reduced. Slower growth means lower tax receipts, higher spending and a 10 bigger budget deficit. Some economists have suggested that the government should not pursue additional reductions in the budget deficit. They have also claimed that the responsibility of the government is not to balance the budget but to balance the economy by moving it to full employment. 15 (Source: adapted from ‘Philip Hammond must ditch deficit reduction and invest. But will he?’, The Guardian, https:// www.theguardian.com/politics/2017/nov/19/philip-hammond-must-ditch-deficit- reduction-and-invest-but-will-he’)
(e) Discuss the factors that might explain why ‘the UK’s forecast long-term trend rate of growth was reduced’ (Extract B lines 9–10). (15)
June 2017 · Paper 1 · Q6(d) 10 marks AO1=2, AO2=2, AO3=2, AO4=4 10-mark response Hard public goods and information gapsrational decision making and behavioural economics
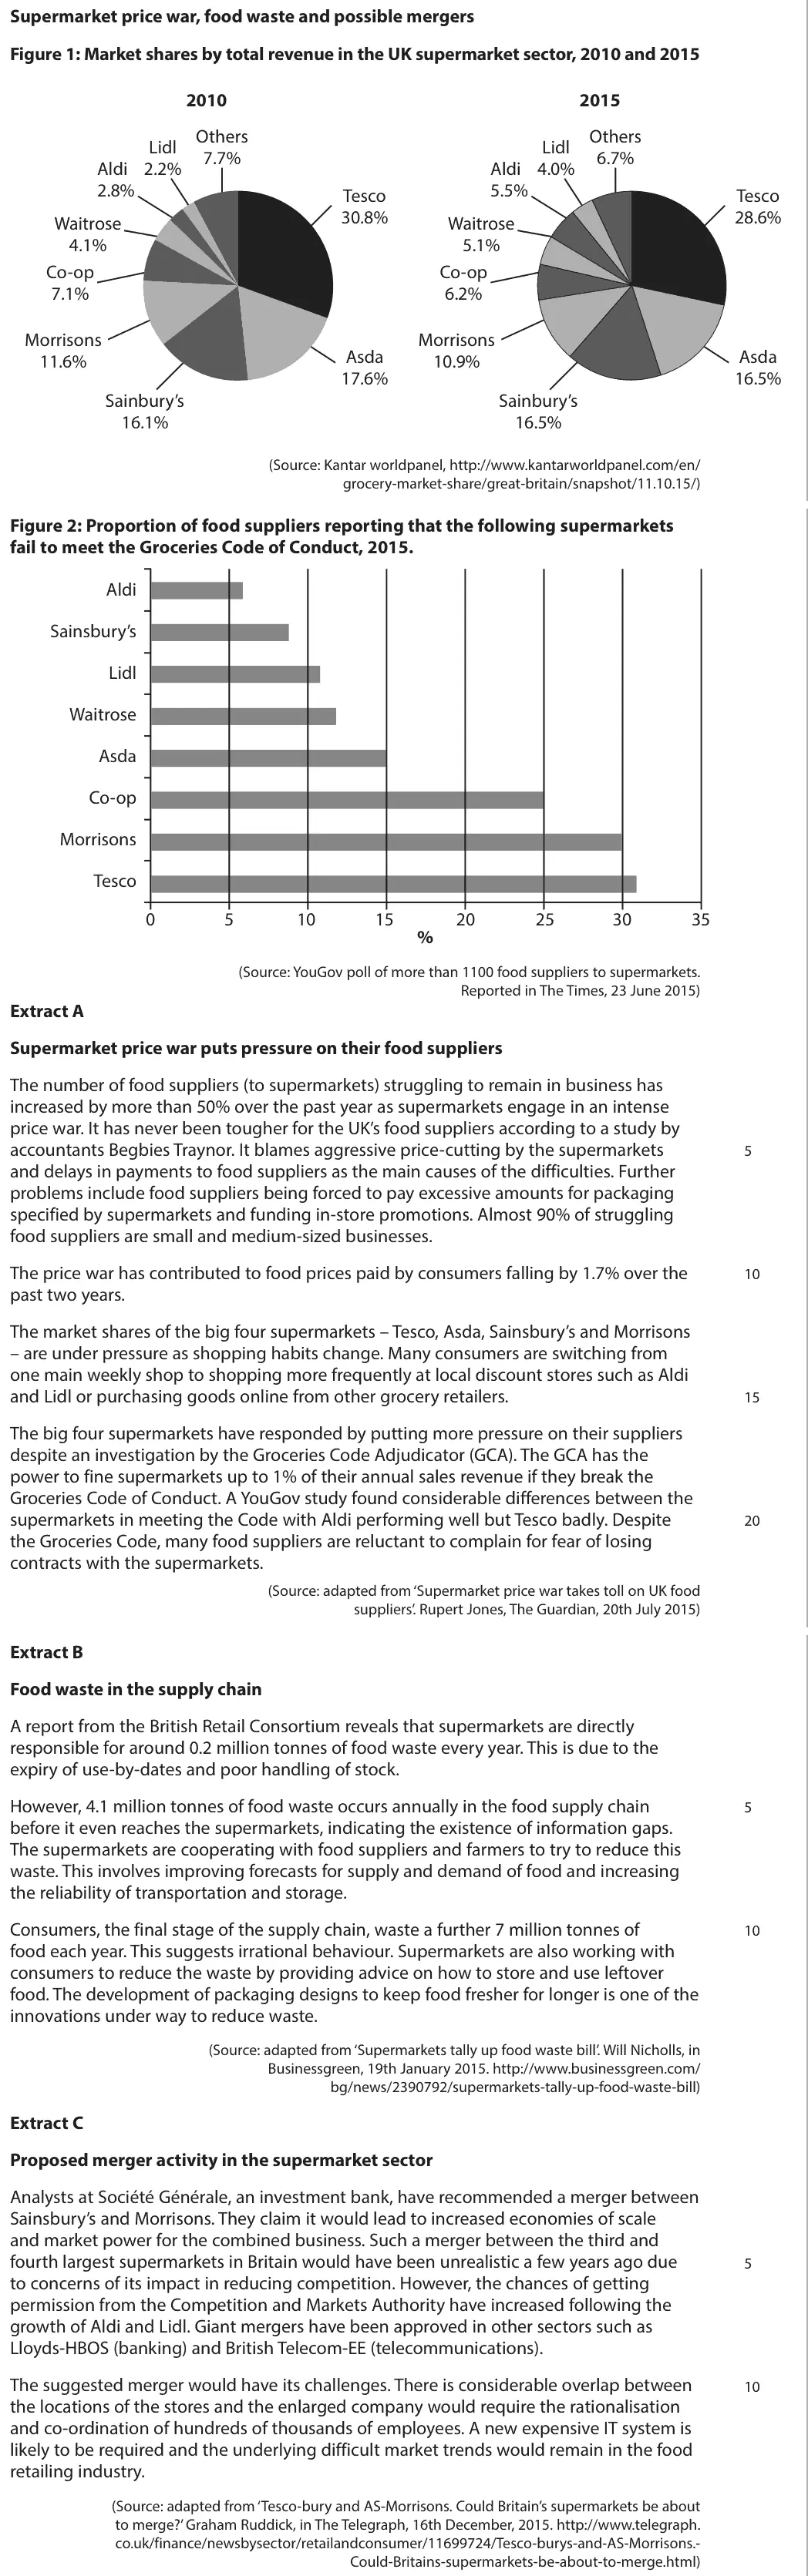
Data and extracts for question 6Supermarket price war, food waste and possible mergers Figure 1: Market shares by total revenue in the UK supermarket sector, 2010 and 2015 2010 2015 Others Others Lidl Lidl 7.7% 6.7% Aldi 2.2% Aldi 4.0% 2.8% 5.5% Tesco Tesco 30.8% 28.6% Waitrose Waitrose 4.1% 5.1% Co-op Co-op 7.1% 6.2% Morrisons Morrisons Asda Asda 11.6% 10.9% 17.6% 16.5% Sainbury’s Sainbury’s 16.1% 16.5% (Source: Kantar worldpanel, http://www.kantarworldpanel.com/en/ grocery-market-share/great-britain/snapshot/11.10.15/) Figure 2: Proportion of food suppliers reporting that the following supermarkets fail to meet the Groceries Code of Conduct, 2015. Aldi Sainsbury’s Lidl Waitrose Asda Co-op Morrisons Tesco 0 5 10 15 20 25 30 35 % (Source: YouGov poll of more than 1100 food suppliers to supermarkets. Reported in The Times, 23 June 2015) Extract A Supermarket price war puts pressure on their food suppliers The number of food suppliers (to supermarkets) struggling to remain in business has increased by more than 50% over the past year as supermarkets engage in an intense price war. It has never been tougher for the UK’s food suppliers according to a study by accountants Begbies Traynor. It blames aggressive price-cutting by the supermarkets 5 and delays in payments to food suppliers as the main causes of the difficulties. Further problems include food suppliers being forced to pay excessive amounts for packaging specified by supermarkets and funding in-store promotions. Almost 90% of struggling food suppliers are small and medium-sized businesses. The price war has contributed to food prices paid by consumers falling by 1.7% over the 10 past two years. The market shares of the big four supermarkets – Tesco, Asda, Sainsbury’s and Morrisons – are under pressure as shopping habits change. Many consumers are switching from one main weekly shop to shopping more frequently at local discount stores such as Aldi and Lidl or purchasing goods online from other grocery retailers. 15 The big four supermarkets have responded by putting more pressure on their suppliers despite an investigation by the Groceries Code Adjudicator (GCA). The GCA has the power to fine supermarkets up to 1% of their annual sales revenue if they break the Groceries Code of Conduct. A YouGov study found considerable differences between the supermarkets in meeting the Code with Aldi performing well but Tesco badly. Despite 20 the Groceries Code, many food suppliers are reluctant to complain for fear of losing contracts with the supermarkets. (Source: adapted from ‘Supermarket price war takes toll on UK food suppliers’. Rupert Jones, The Guardian, 20th July 2015) Extract B Food waste in the supply chain A report from the British Retail Consortium reveals that supermarkets are directly responsible for around 0.2 million tonnes of food waste every year. This is due to the expiry of use-by-dates and poor handling of stock. However, 4.1 million tonnes of food waste occurs annually in the food supply chain 5 before it even reaches the supermarkets, indicating the existence of information gaps. The supermarkets are cooperating with food suppliers and farmers to try to reduce this waste. This involves improving forecasts for supply and demand of food and increasing the reliability of transportation and storage. Consumers, the final stage of the supply chain, waste a further 7 million tonnes of 10 food each year. This suggests irrational behaviour. Supermarkets are also working with consumers to reduce the waste by providing advice on how to store and use leftover food. The development of packaging designs to keep food fresher for longer is one of the innovations under way to reduce waste. (Source: adapted from ‘Supermarkets tally up food waste bill’. Will Nicholls, in Businessgreen, 19th January 2015. http://www.businessgreen.com/ bg/news/2390792/supermarkets-tally-up-food-waste-bill) Extract C Proposed merger activity in the supermarket sector Analysts at Société Générale, an investment bank, have recommended a merger between Sainsbury’s and Morrisons. They claim it would lead to increased economies of scale and market power for the combined business. Such a merger between the third and fourth largest supermarkets in Britain would have been unrealistic a few years ago due 5 to concerns of its impact in reducing competition. However, the chances of getting permission from the Competition and Markets Authority have increased following the growth of Aldi and Lidl. Giant mergers have been approved in other sectors such as Lloyds-HBOS (banking) and British Telecom-EE (telecommunications). The suggested merger would have its challenges. There is considerable overlap between 10 the locations of the stores and the enlarged company would require the rationalisation and co-ordination of hundreds of thousands of employees. A new expensive IT system is likely to be required and the underlying difficult market trends would remain in the food retailing industry. (Source: adapted from ‘Tesco-bury and AS-Morrisons. Could Britain’s supermarkets be about to merge?’ Graham Ruddick, in The Telegraph, 16th December, 2015. http://www.telegraph. co.uk/finance/newsbysector/retailandconsumer/11699724/Tesco-burys-and-AS-Morrisons.- Could-Britains-supermarkets-be-about-to-merge.html)
(d) Assess the extent to which ‘information gaps’ (Extract B, lines 5 and 6) and ‘irrational behaviour’ (Extract B, line 11) are the main causes of food waste in the UK. (10)
June 2019 · Paper 1 · Q3(b) 4 marks AO1=2, AO2=2 Diagram Hard market structures and efficiency
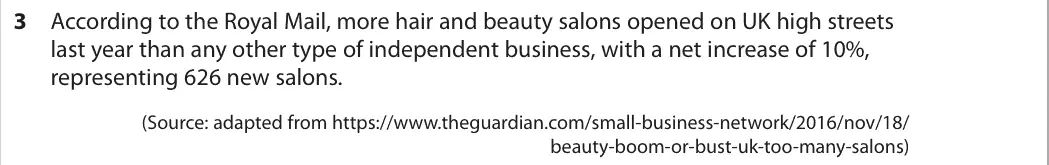
Data and extracts for question 33 According to the Royal Mail, more hair and beauty salons opened on UK high streets last year than any other type of independent business, with a net increase of 10%, representing 626 new salons. (Source: adapted from https://www.theguardian.com/small-business-network/2016/nov/18/ beauty-boom-or-bust-uk-too-many-salons)
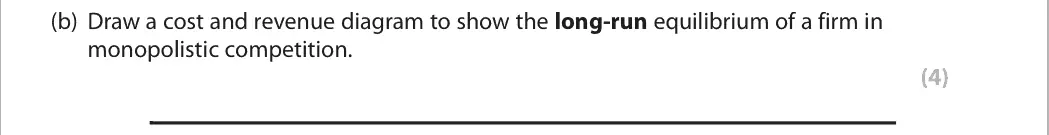
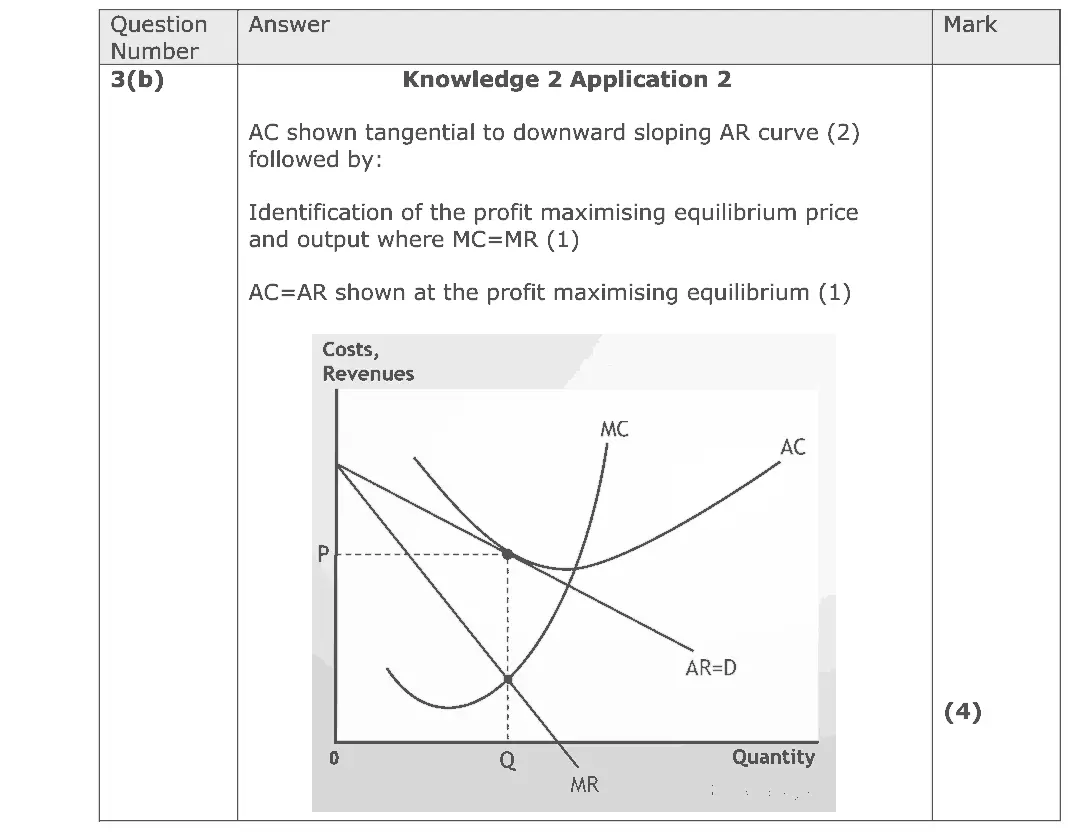
(b) Draw a cost and revenue diagram to show the long-run equilibrium of a firm in monopolistic competition. (4)
June 2022 · Paper 1 · Q6(b) 8 marks AO1=2, AO2=2, AO3=2, AO4=2 8-mark response Hard price elasticity of demandelasticity of supply
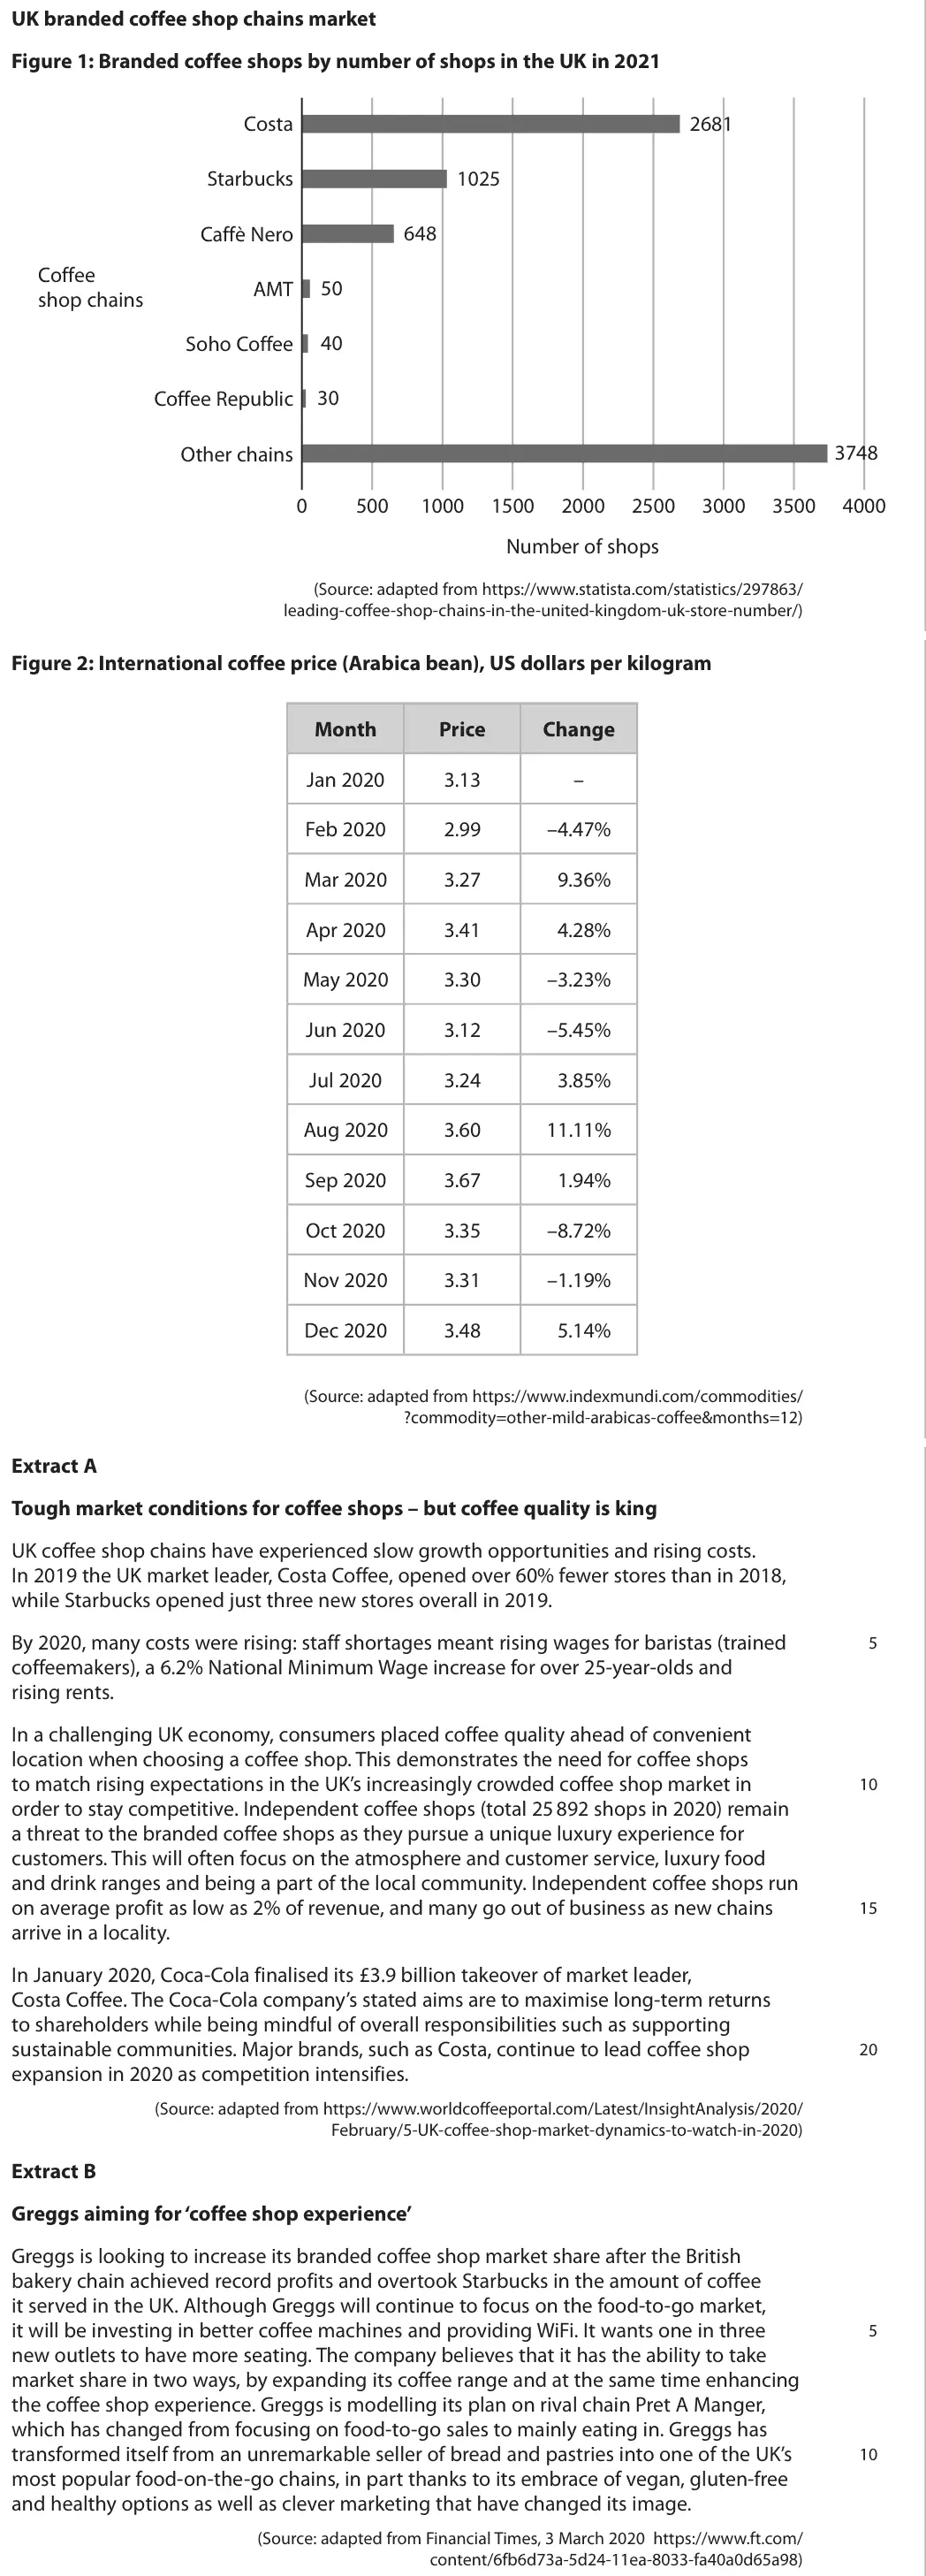
Data and extracts for question 6UK branded coffee shop chains market Figure 1: Branded coffee shops by number of shops in the UK in 2021 Costa 2681 Starbucks 1025 Caffè Nero 648 Coffee 50 AMT shop chains 40 Soho Coffee 30 Coffee Republic 3748 Other chains 0 500 1000 1500 2000 2500 3000 3500 4000 Number of shops (Source: adapted from https://www.statista.com/statistics/297863/ leading-coffee-shop-chains-in-the-united-kingdom-uk-store-number/) Figure 2: International coffee price (Arabica bean), US dollars per kilogram Month Price Change Jan 2020 3.13 – Feb 2020 2.99 –4.47% Mar 2020 3.27 9.36% Apr 2020 3.41 4.28% May 2020 3.30 –3.23% Jun 2020 3.12 –5.45% Jul 2020 3.24 3.85% Aug 2020 3.60 11.11% Sep 2020 3.67 1.94% Oct 2020 3.35 –8.72% Nov 2020 3.31 –1.19% Dec 2020 3.48 5.14% (Source: adapted from https://www.indexmundi.com/commodities/ ?commodity=other-mild-arabicas-coffee&months=12) Extract A Tough market conditions for coffee shops – but coffee quality is king UK coffee shop chains have experienced slow growth opportunities and rising costs. In 2019 the UK market leader, Costa Coffee, opened over 60% fewer stores than in 2018, while Starbucks opened just three new stores overall in 2019. By 2020, many costs were rising: staff shortages meant rising wages for baristas (trained 5 coffeemakers), a 6.2% National Minimum Wage increase for over 25-year-olds and rising rents. In a challenging UK economy, consumers placed coffee quality ahead of convenient location when choosing a coffee shop. This demonstrates the need for coffee shops to match rising expectations in the UK’s increasingly crowded coffee shop market in 10 order to stay competitive. Independent coffee shops (total 25 892 shops in 2020) remain a threat to the branded coffee shops as they pursue a unique luxury experience for customers. This will often focus on the atmosphere and customer service, luxury food and drink ranges and being a part of the local community. Independent coffee shops run on average profit as low as 2% of revenue, and many go out of business as new chains 15 arrive in a locality. In January 2020, Coca-Cola finalised its £3.9 billion takeover of market leader, Costa Coffee. The Coca-Cola company’s stated aims are to maximise long-term returns to shareholders while being mindful of overall responsibilities such as supporting sustainable communities. Major brands, such as Costa, continue to lead coffee shop 20 expansion in 2020 as competition intensifies. (Source: adapted from https://www.worldcoffeeportal.com/Latest/InsightAnalysis/2020/ February/5-UK-coffee-shop-market-dynamics-to-watch-in-2020) Extract B Greggs aiming for ‘coffee shop experience’ Greggs is looking to increase its branded coffee shop market share after the British bakery chain achieved record profits and overtook Starbucks in the amount of coffee it served in the UK. Although Greggs will continue to focus on the food-to-go market, it will be investing in better coffee machines and providing WiFi. It wants one in three 5 new outlets to have more seating. The company believes that it has the ability to take market share in two ways, by expanding its coffee range and at the same time enhancing the coffee shop experience. Greggs is modelling its plan on rival chain Pret A Manger, which has changed from focusing on food-to-go sales to mainly eating in. Greggs has transformed itself from an unremarkable seller of bread and pastries into one of the UK’s 10 most popular food-on-the-go chains, in part thanks to its embrace of vegan, gluten-free and healthy options as well as clever marketing that have changed its image. (Source: adapted from Financial Times, 3 March 2020 https://www.ft.com/ content/6fb6d73a-5d24-11ea-8033-fa40a0d65a98)
(b) With reference to Figure 2 and your understanding of price elasticity, examine two factors that may cause significant changes in the international price of coffee beans. (8)
June 2024 · Paper 1 · Q8 25 marks AO1=4, AO2=4, AO3=8, AO4=9 25-mark essay Either/or Hard monopsony and contestability
8 Bytedance, which owns TikTok, has launched its own fragrance ‘Emotif’. The Beijing-based social media giant has already entered the food and drink markets. (Source adapted from: https://www.businessoffashion.com/news/china/ tiktoks-parent-company-enters-chinas-perfume-market/) Evaluate the level of contestability in the fragrance industry or another industry of your choice.
October 2020 · Paper 1 · Q4(a) 2 marks AO1=1, AO3=1 Short answer Hard revenues costs and profits
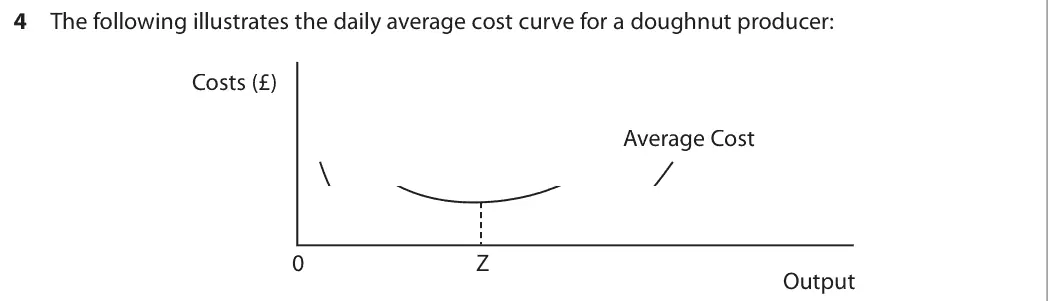
Data and extracts for question 44 The following illustrates the daily average cost curve for a doughnut producer: Costs (£) Average Cost 0 Z Output
(a) Explain what happens to total cost at output levels greater than Z. (2)
June 2022 · Paper 2 · Q4(b) 4 marks AO1=3, AO2=1 Short answer Hard public finances and taxation
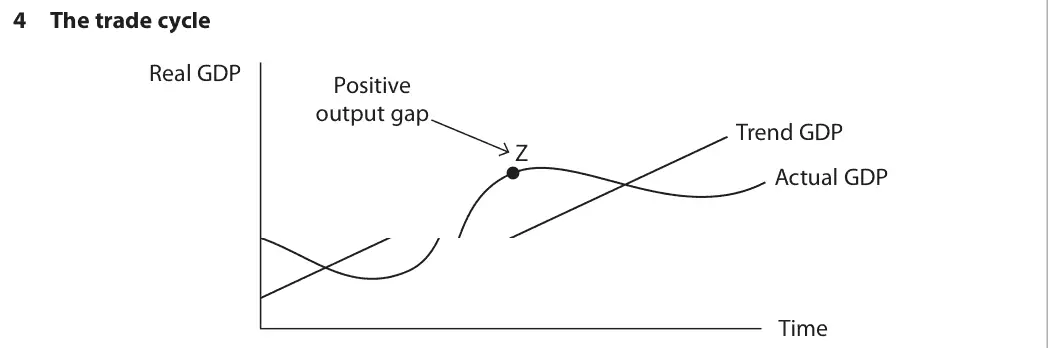
Data and extracts for question 44 The trade cycle Real GDP Positive output gap Trend GDP Z Actual GDP Time
(b) With reference to the graph, explain the difference between automatic stabilisers and discretionary fiscal policy. (4)
June 2025 · Paper 2 · Q4(a) 2 marks AO1=2 Short answer Hard globalisation and trade
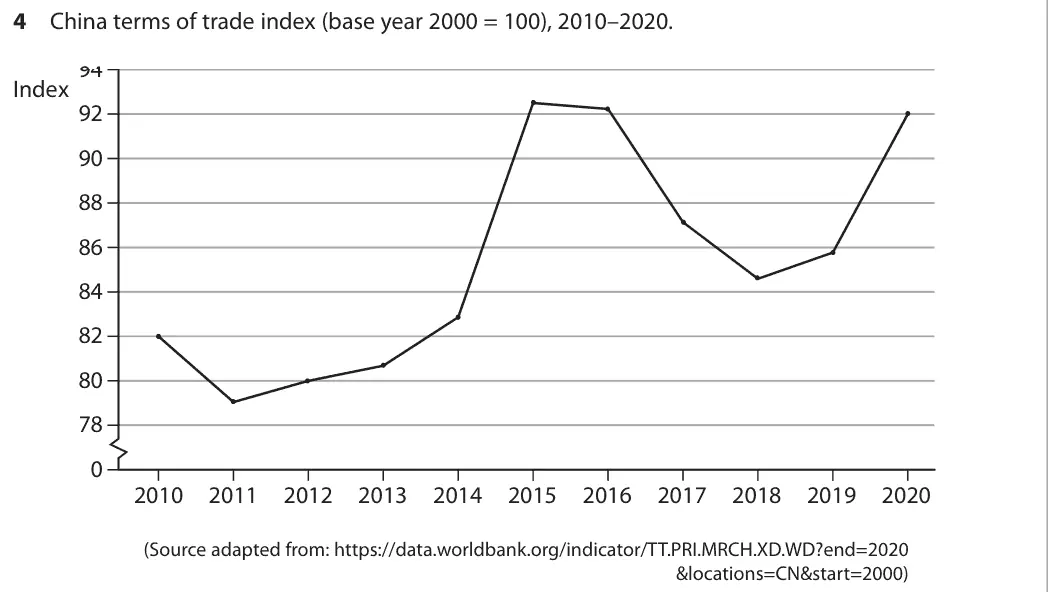
Data and extracts for question 44 China terms of trade index (base year 2000 = 100), 2010–2020. 94 Index 92 90 88 86 84 82 80 78 0 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 (Source adapted from: https://data.worldbank.org/indicator/TT.PRI.MRCH.XD.WD?end=2020 &locations=CN&start=2000)
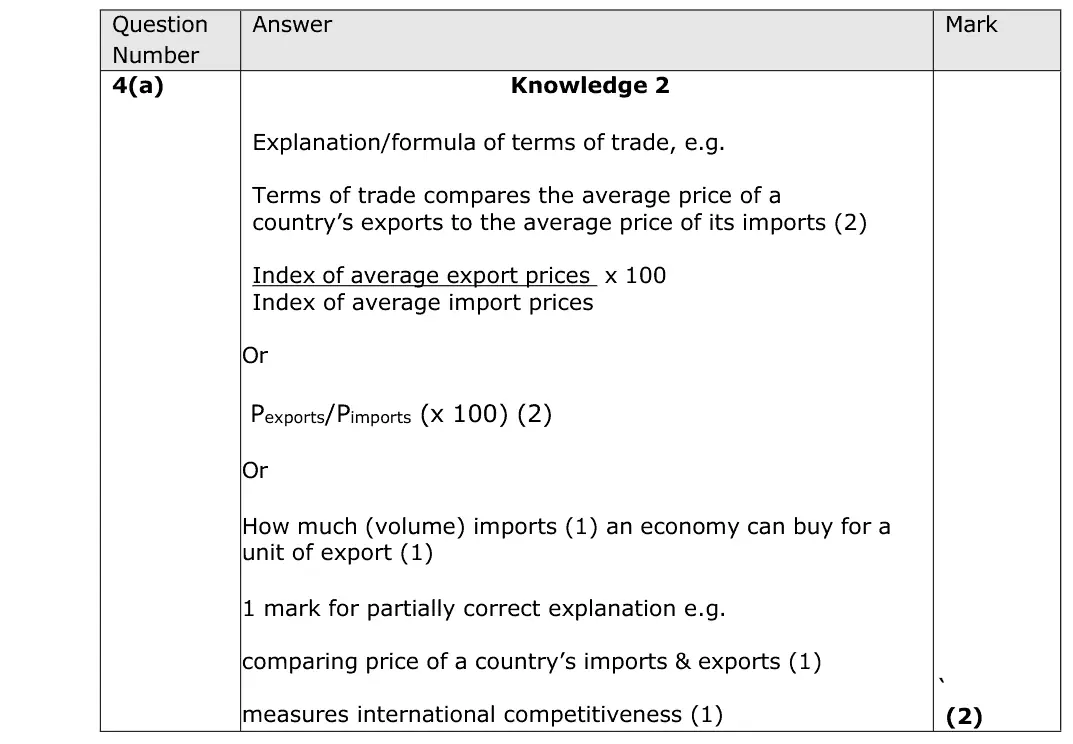
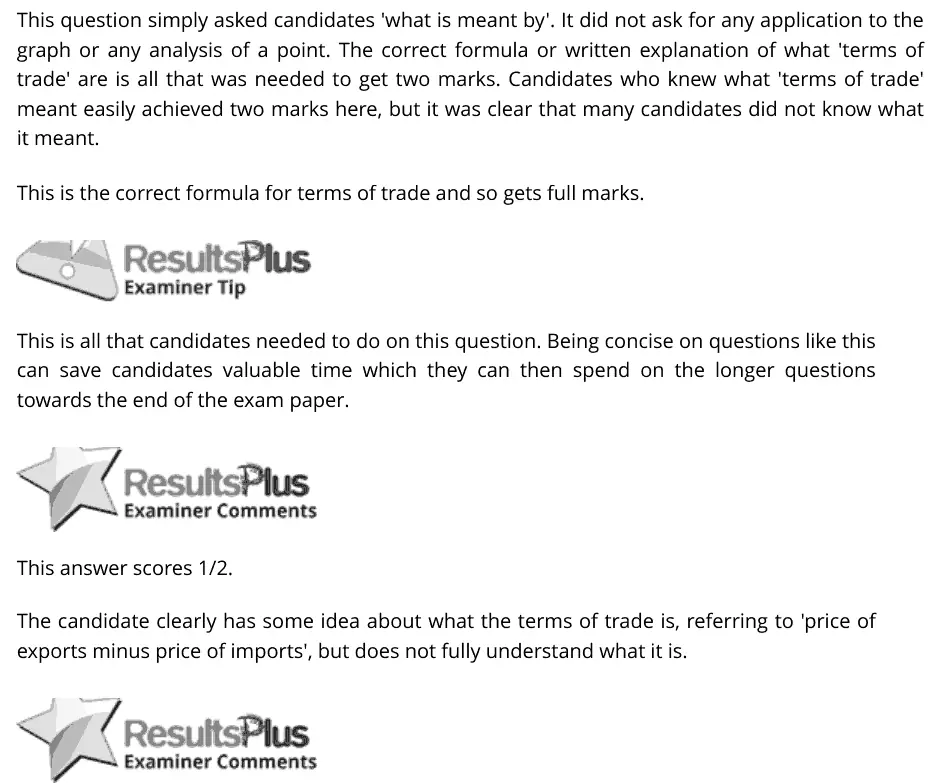
(a) Explain what is meant by ‘terms of trade’. (2)
June 2025 · Paper 2 · Q4(c) 2 marks AO1=1, AO3=1 Short answer Hard globalisation and tradebalance of payments
Data and extracts for question 44 China terms of trade index (base year 2000 = 100), 2010–2020. 94 Index 92 90 88 86 84 82 80 78 0 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 (Source adapted from: https://data.worldbank.org/indicator/TT.PRI.MRCH.XD.WD?end=2020 &locations=CN&start=2000)
(c) Explain the likely impact of the change in China’s terms of trade from 2012 to 2020 on China’s current account. Assume that demand for China’s exports and imports is price elastic. (2)
November 2021 · Paper 2 · Q5(c) 2 marks AO1=1, AO3=1 Short answer Hard measuring economic growth
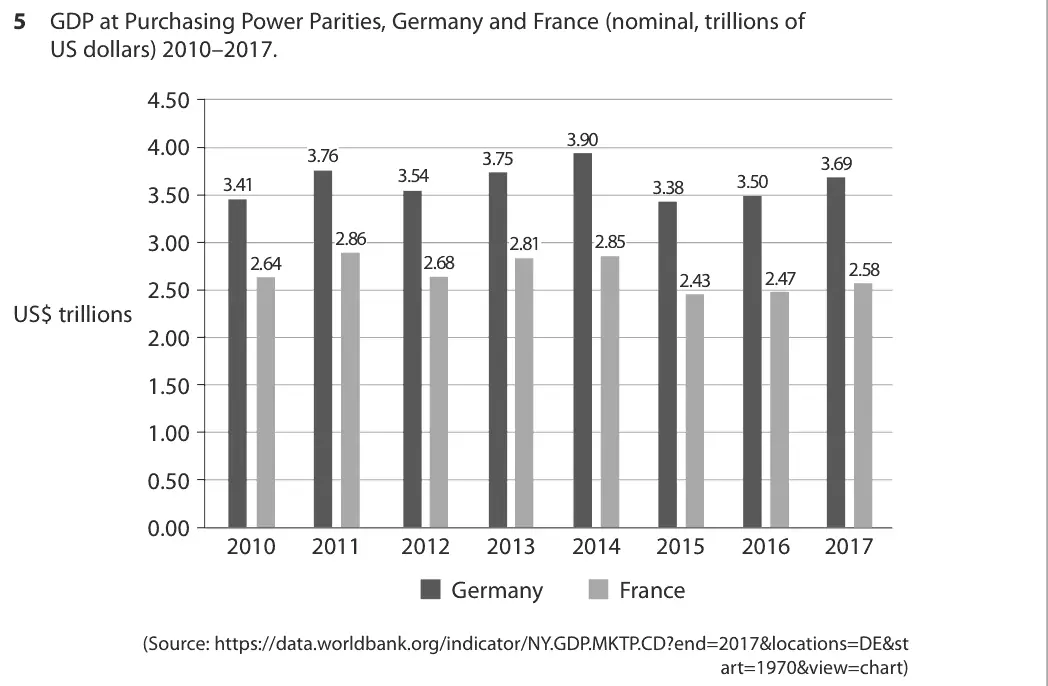
Data and extracts for question 55 GDP at Purchasing Power Parities, Germany and France (nominal, trillions of US dollars) 2010–2017. 4.50 3 . 90 4.00 3 . 76 3 . 75 3 . 69 3 . 54 3 . 50 3 . 41 3 . 38 3.50 2 . 86 3.00 2 . 85 2 . 81 2. 64 2 . 68 2 . 58 2 . 47 2 . 43 2.50 US$ trillions 2.00 1.50 1.00 0.50 0.00 2010 2011 2012 2013 2014 2015 2016 2017 Germany France (Source: https://data.worldbank.org/indicator/NY.GDP.MKTP.CD?end=2017&locations=DE&st art=1970&view=chart)
(c) Explain one reason why Purchasing Power Parities are used. (2)
October 2020 · Paper 2 · Q1(a) 2 marks AO2=2 Calculation Hard measuring economic growth
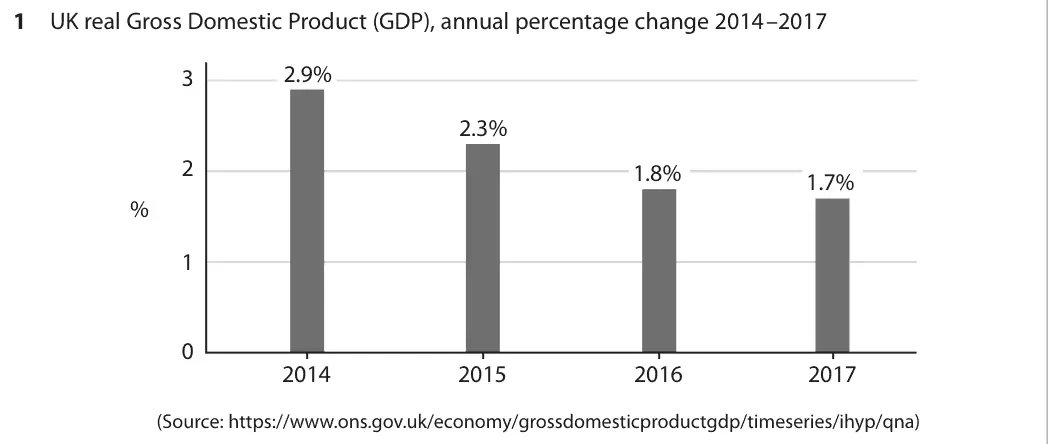
Data and extracts for question 11 UK real Gross Domestic Product (GDP), annual percentage change 2014–2017 2.9% 3 2.3% 2 1.8% 1.7% % 1 0 2014 2015 2016 2017 (Source: https://www.ons.gov.uk/economy/grossdomesticproductgdp/timeseries/ihyp/qna)
(a) Total real UK GDP in 2016 was £200 000 million. With reference to the chart above, calculate the total real UK GDP for 2017. You are advised to show your working. (2)
June 2017 · Paper 3 · Q2(b) 8 marks AO1=2, AO2=2, AO3=2, AO4=2 8-mark response Hard public finances and taxation
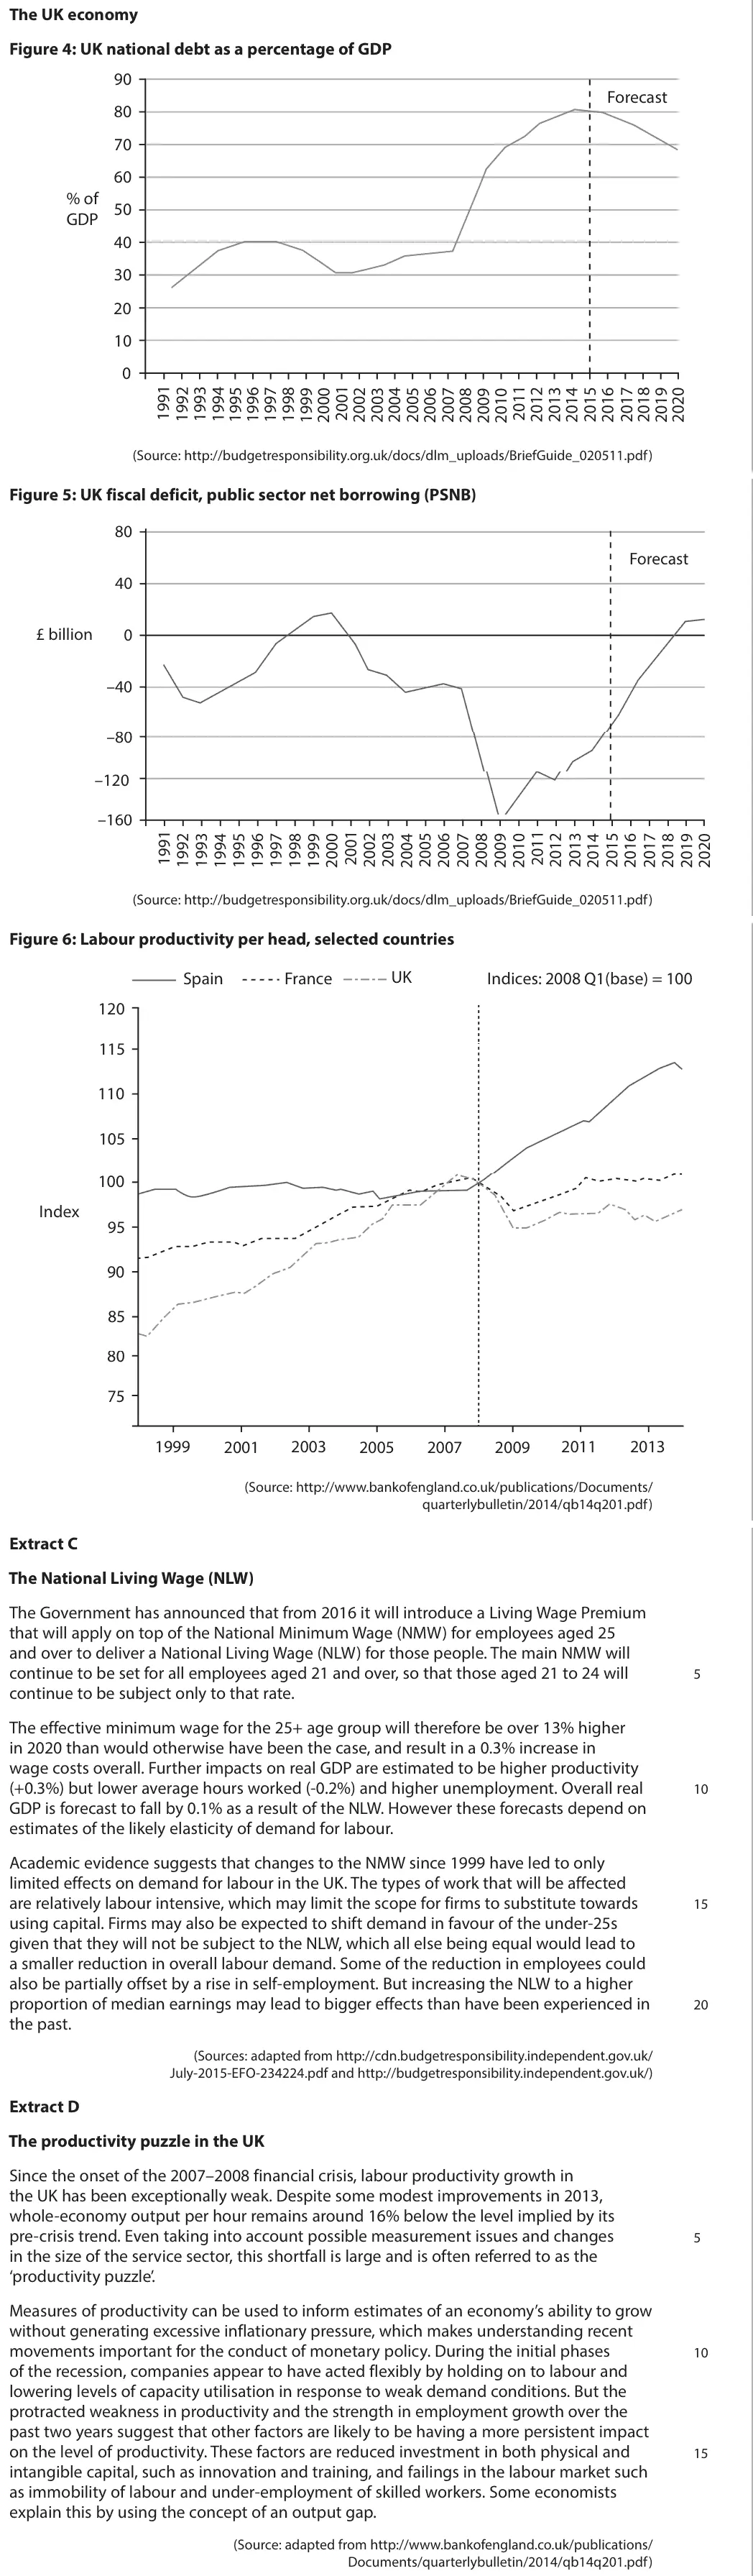
Data and extracts for question 2The UK economy Figure 4: UK national debt as a percentage of GDP 90 Forecast 80 70 60 % of 50 GDP 40 30 20 10 0 (Source: http://budgetresponsibility.org.uk/docs/dlm_uploads/BriefGuide_020511.pdf) Figure 5: UK fiscal deficit, public sector net borrowing (PSNB) 80 Forecast 40 £ billion 0 –40 –80 –120 –160 (Source: http://budgetresponsibility.org.uk/docs/dlm_uploads/BriefGuide_020511.pdf) Figure 6: Labour productivity per head, selected countries UK Spain France Indices: 2008 Q1(base) = 100 120 115 110 105 100 Index 95 90 85 80 75 1999 2001 2003 2005 2007 2009 2011 2013 (Source: http://www.bankofengland.co.uk/publications/Documents/ quarterlybulletin/2014/qb14q201.pdf) Extract C The National Living Wage (NLW) The Government has announced that from 2016 it will introduce a Living Wage Premium that will apply on top of the National Minimum Wage (NMW) for employees aged 25 and over to deliver a National Living Wage (NLW) for those people. The main NMW will continue to be set for all employees aged 21 and over, so that those aged 21 to 24 will 5 continue to be subject only to that rate. The effective minimum wage for the 25+ age group will therefore be over 13% higher in 2020 than would otherwise have been the case, and result in a 0.3% increase in wage costs overall. Further impacts on real GDP are estimated to be higher productivity (+0.3%) but lower average hours worked (-0.2%) and higher unemployment. Overall real 10 GDP is forecast to fall by 0.1% as a result of the NLW. However these forecasts depend on estimates of the likely elasticity of demand for labour. Academic evidence suggests that changes to the NMW since 1999 have led to only limited effects on demand for labour in the UK. The types of work that will be affected are relatively labour intensive, which may limit the scope for firms to substitute towards 15 using capital. Firms may also be expected to shift demand in favour of the under-25s given that they will not be subject to the NLW, which all else being equal would lead to a smaller reduction in overall labour demand. Some of the reduction in employees could also be partially offset by a rise in self-employment. But increasing the NLW to a higher proportion of median earnings may lead to bigger effects than have been experienced in 20 the past. (Sources: adapted from http://cdn.budgetresponsibility.independent.gov.uk/ July-2015-EFO-234224.pdf and http://budgetresponsibility.independent.gov.uk/) Extract D The productivity puzzle in the UK Since the onset of the 2007–2008 financial crisis, labour productivity growth in the UK has been exceptionally weak. Despite some modest improvements in 2013, whole-economy output per hour remains around 16% below the level implied by its pre-crisis trend. Even taking into account possible measurement issues and changes 5 in the size of the service sector, this shortfall is large and is often referred to as the ‘productivity puzzle’. Measures of productivity can be used to inform estimates of an economy’s ability to grow without generating excessive inflationary pressure, which makes understanding recent movements important for the conduct of monetary policy. During the initial phases 10 of the recession, companies appear to have acted flexibly by holding on to labour and lowering levels of capacity utilisation in response to weak demand conditions. But the protracted weakness in productivity and the strength in employment growth over the past two years suggest that other factors are likely to be having a more persistent impact on the level of productivity. These factors are reduced investment in both physical and 15 intangible capital, such as innovation and training, and failings in the labour market such as immobility of labour and under-employment of skilled workers. Some economists explain this by using the concept of an output gap. (Source: adapted from http://www.bankofengland.co.uk/publications/ Documents/quarterlybulletin/2014/qb14q201.pdf)
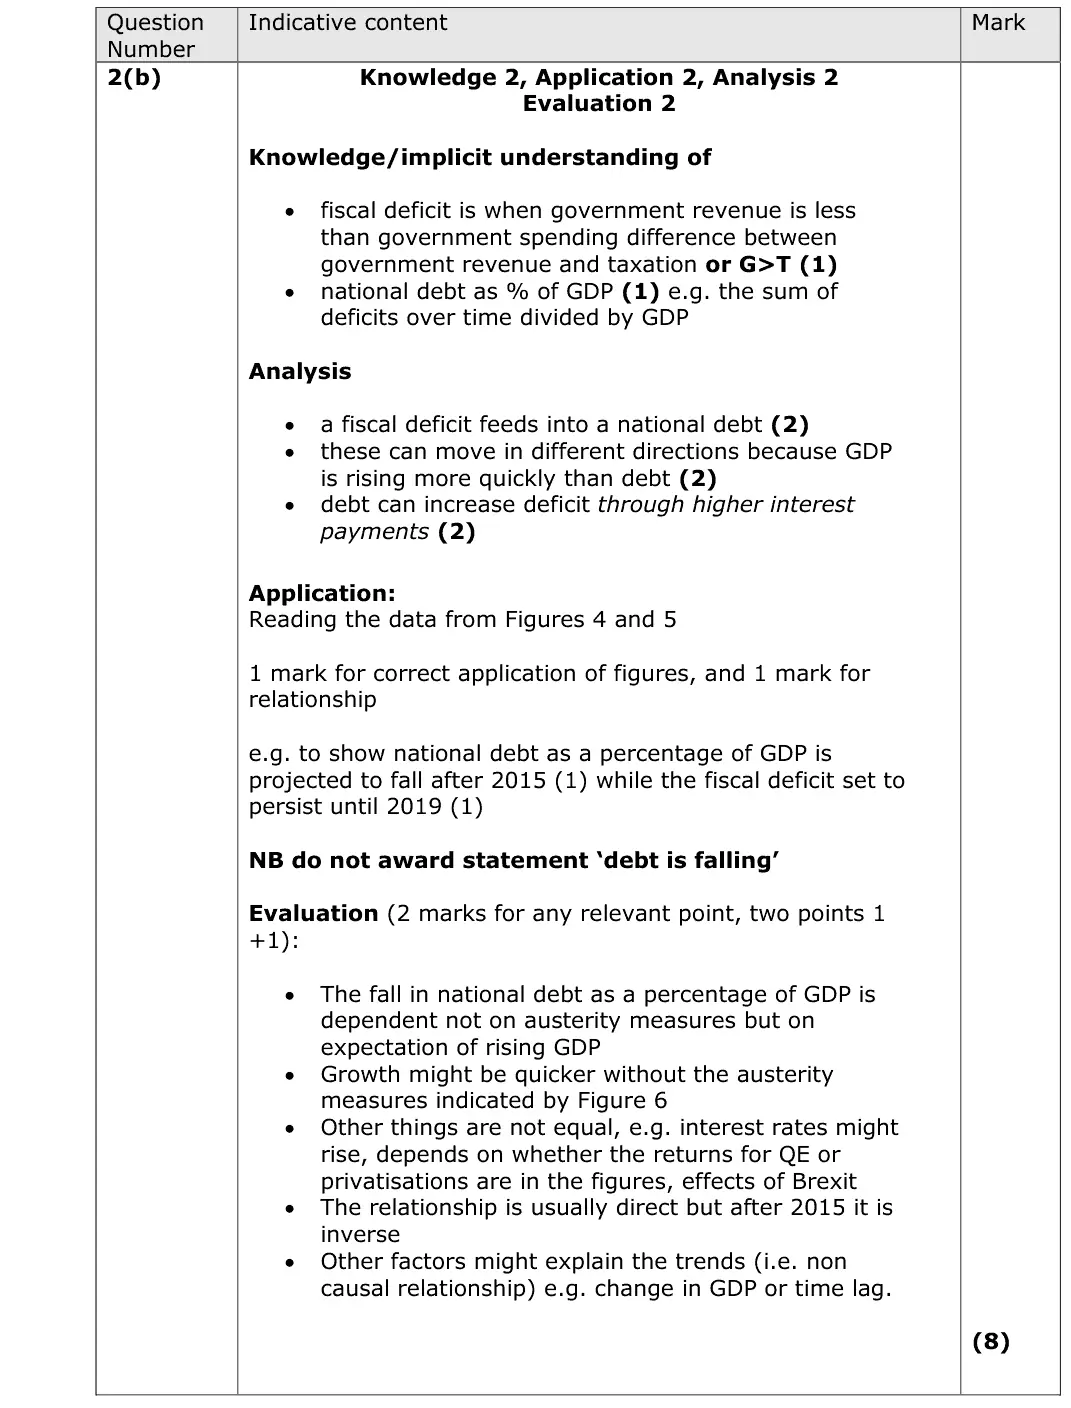
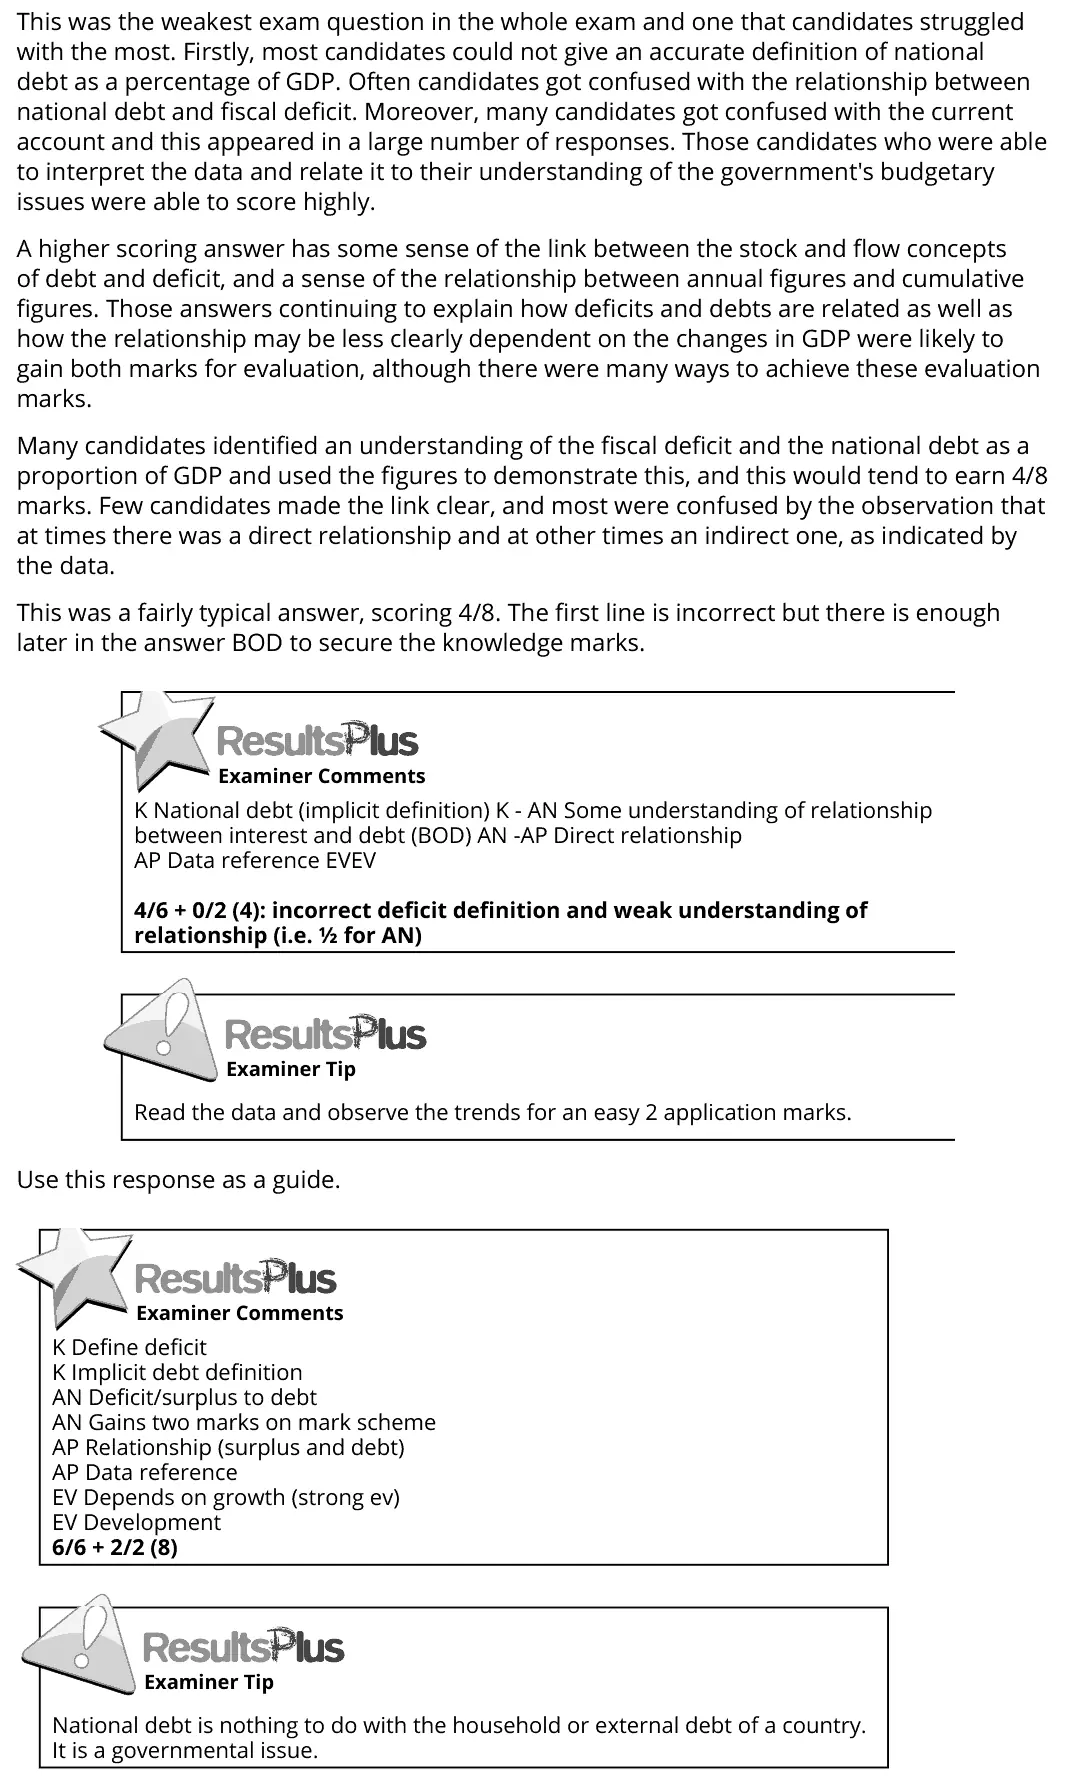
(b) With reference to Figures 4 and 5 and your own knowledge, examine the relationship between the national debt as a proportion of GDP and the fiscal deficit. (8)
June 2018 · Paper 3 · Q2(b) 8 marks AO1=2, AO2=2, AO3=2, AO4=2 8-mark response Hard revenues costs and profits
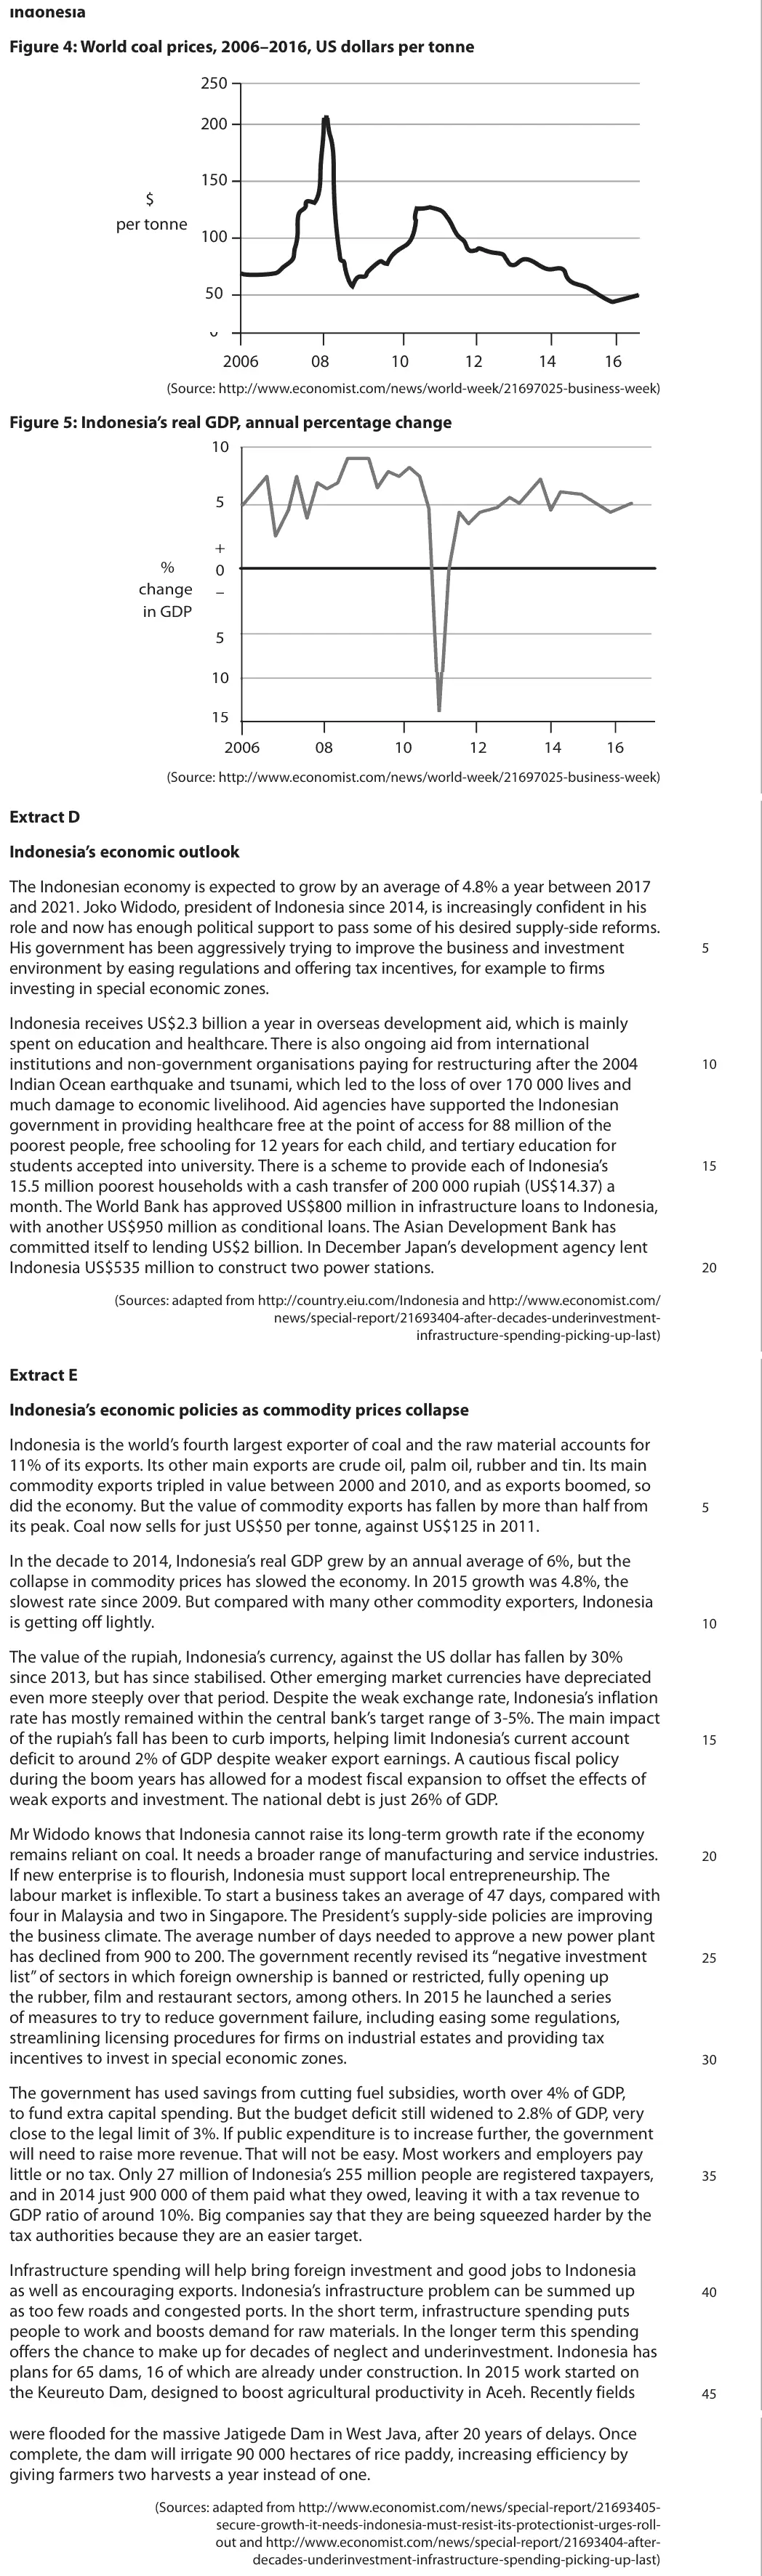
Data and extracts for question 2Indonesia Figure 4: World coal prices, 2006–2016, US dollars per tonne 250 200 150 $ per tonne 100 50 0 2006 08 10 12 14 16 (Source: http://www.economist.com/news/world-week/21697025-business-week) Figure 5: Indonesia’s real GDP, annual percentage change 10 5 + % 0 change – in GDP 5 10 15 2006 08 10 12 14 16 (Source: http://www.economist.com/news/world-week/21697025-business-week) Extract D Indonesia’s economic outlook The Indonesian economy is expected to grow by an average of 4.8% a year between 2017 and 2021. Joko Widodo, president of Indonesia since 2014, is increasingly confident in his role and now has enough political support to pass some of his desired supply-side reforms. His government has been aggressively trying to improve the business and investment 5 environment by easing regulations and offering tax incentives, for example to firms investing in special economic zones. Indonesia receives US$2.3 billion a year in overseas development aid, which is mainly spent on education and healthcare. There is also ongoing aid from international institutions and non-government organisations paying for restructuring after the 2004 10 Indian Ocean earthquake and tsunami, which led to the loss of over 170 000 lives and much damage to economic livelihood. Aid agencies have supported the Indonesian government in providing healthcare free at the point of access for 88 million of the poorest people, free schooling for 12 years for each child, and tertiary education for students accepted into university. There is a scheme to provide each of Indonesia’s 15 15.5 million poorest households with a cash transfer of 200 000 rupiah (US$14.37) a month. The World Bank has approved US$800 million in infrastructure loans to Indonesia, with another US$950 million as conditional loans. The Asian Development Bank has committed itself to lending US$2 billion. In December Japan’s development agency lent Indonesia US$535 million to construct two power stations. 20 (Sources: adapted from http://country.eiu.com/Indonesia and http://www.economist.com/ news/special-report/21693404-after-decades-underinvestment- infrastructure-spending-picking-up-last) Extract E Indonesia’s economic policies as commodity prices collapse Indonesia is the world’s fourth largest exporter of coal and the raw material accounts for 11% of its exports. Its other main exports are crude oil, palm oil, rubber and tin. Its main commodity exports tripled in value between 2000 and 2010, and as exports boomed, so did the economy. But the value of commodity exports has fallen by more than half from 5 its peak. Coal now sells for just US$50 per tonne, against US$125 in 2011. In the decade to 2014, Indonesia’s real GDP grew by an annual average of 6%, but the collapse in commodity prices has slowed the economy. In 2015 growth was 4.8%, the slowest rate since 2009. But compared with many other commodity exporters, Indonesia is getting off lightly. 10 The value of the rupiah, Indonesia’s currency, against the US dollar has fallen by 30% since 2013, but has since stabilised. Other emerging market currencies have depreciated even more steeply over that period. Despite the weak exchange rate, Indonesia’s inflation rate has mostly remained within the central bank’s target range of 3-5%. The main impact of the rupiah’s fall has been to curb imports, helping limit Indonesia’s current account 15 deficit to around 2% of GDP despite weaker export earnings. A cautious fiscal policy during the boom years has allowed for a modest fiscal expansion to offset the effects of weak exports and investment. The national debt is just 26% of GDP. Mr Widodo knows that Indonesia cannot raise its long-term growth rate if the economy remains reliant on coal. It needs a broader range of manufacturing and service industries. 20 If new enterprise is to flourish, Indonesia must support local entrepreneurship. The labour market is inflexible. To start a business takes an average of 47 days, compared with four in Malaysia and two in Singapore. The President’s supply-side policies are improving the business climate. The average number of days needed to approve a new power plant has declined from 900 to 200. The government recently revised its “negative investment 25 list” of sectors in which foreign ownership is banned or restricted, fully opening up the rubber, film and restaurant sectors, among others. In 2015 he launched a series of measures to try to reduce government failure, including easing some regulations, streamlining licensing procedures for firms on industrial estates and providing tax incentives to invest in special economic zones. 30 The government has used savings from cutting fuel subsidies, worth over 4% of GDP, to fund extra capital spending. But the budget deficit still widened to 2.8% of GDP, very close to the legal limit of 3%. If public expenditure is to increase further, the government will need to raise more revenue. That will not be easy. Most workers and employers pay little or no tax. Only 27 million of Indonesia’s 255 million people are registered taxpayers, 35 and in 2014 just 900 000 of them paid what they owed, leaving it with a tax revenue to GDP ratio of around 10%. Big companies say that they are being squeezed harder by the tax authorities because they are an easier target. Infrastructure spending will help bring foreign investment and good jobs to Indonesia as well as encouraging exports. Indonesia’s infrastructure problem can be summed up 40 as too few roads and congested ports. In the short term, infrastructure spending puts people to work and boosts demand for raw materials. In the longer term this spending offers the chance to make up for decades of neglect and underinvestment. Indonesia has plans for 65 dams, 16 of which are already under construction. In 2015 work started on the Keureuto Dam, designed to boost agricultural productivity in Aceh. Recently fields 45 were flooded for the massive Jatigede Dam in West Java, after 20 years of delays. Once complete, the dam will irrigate 90 000 hectares of rice paddy, increasing efficiency by giving farmers two harvests a year instead of one. (Sources: adapted from http://www.economist.com/news/special-report/21693405- secure-growth-it-needs-indonesia-must-resist-its-protectionist-urges-roll- out and http://www.economist.com/news/special-report/21693404-after- decades-underinvestment-infrastructure-spending-picking-up-last)
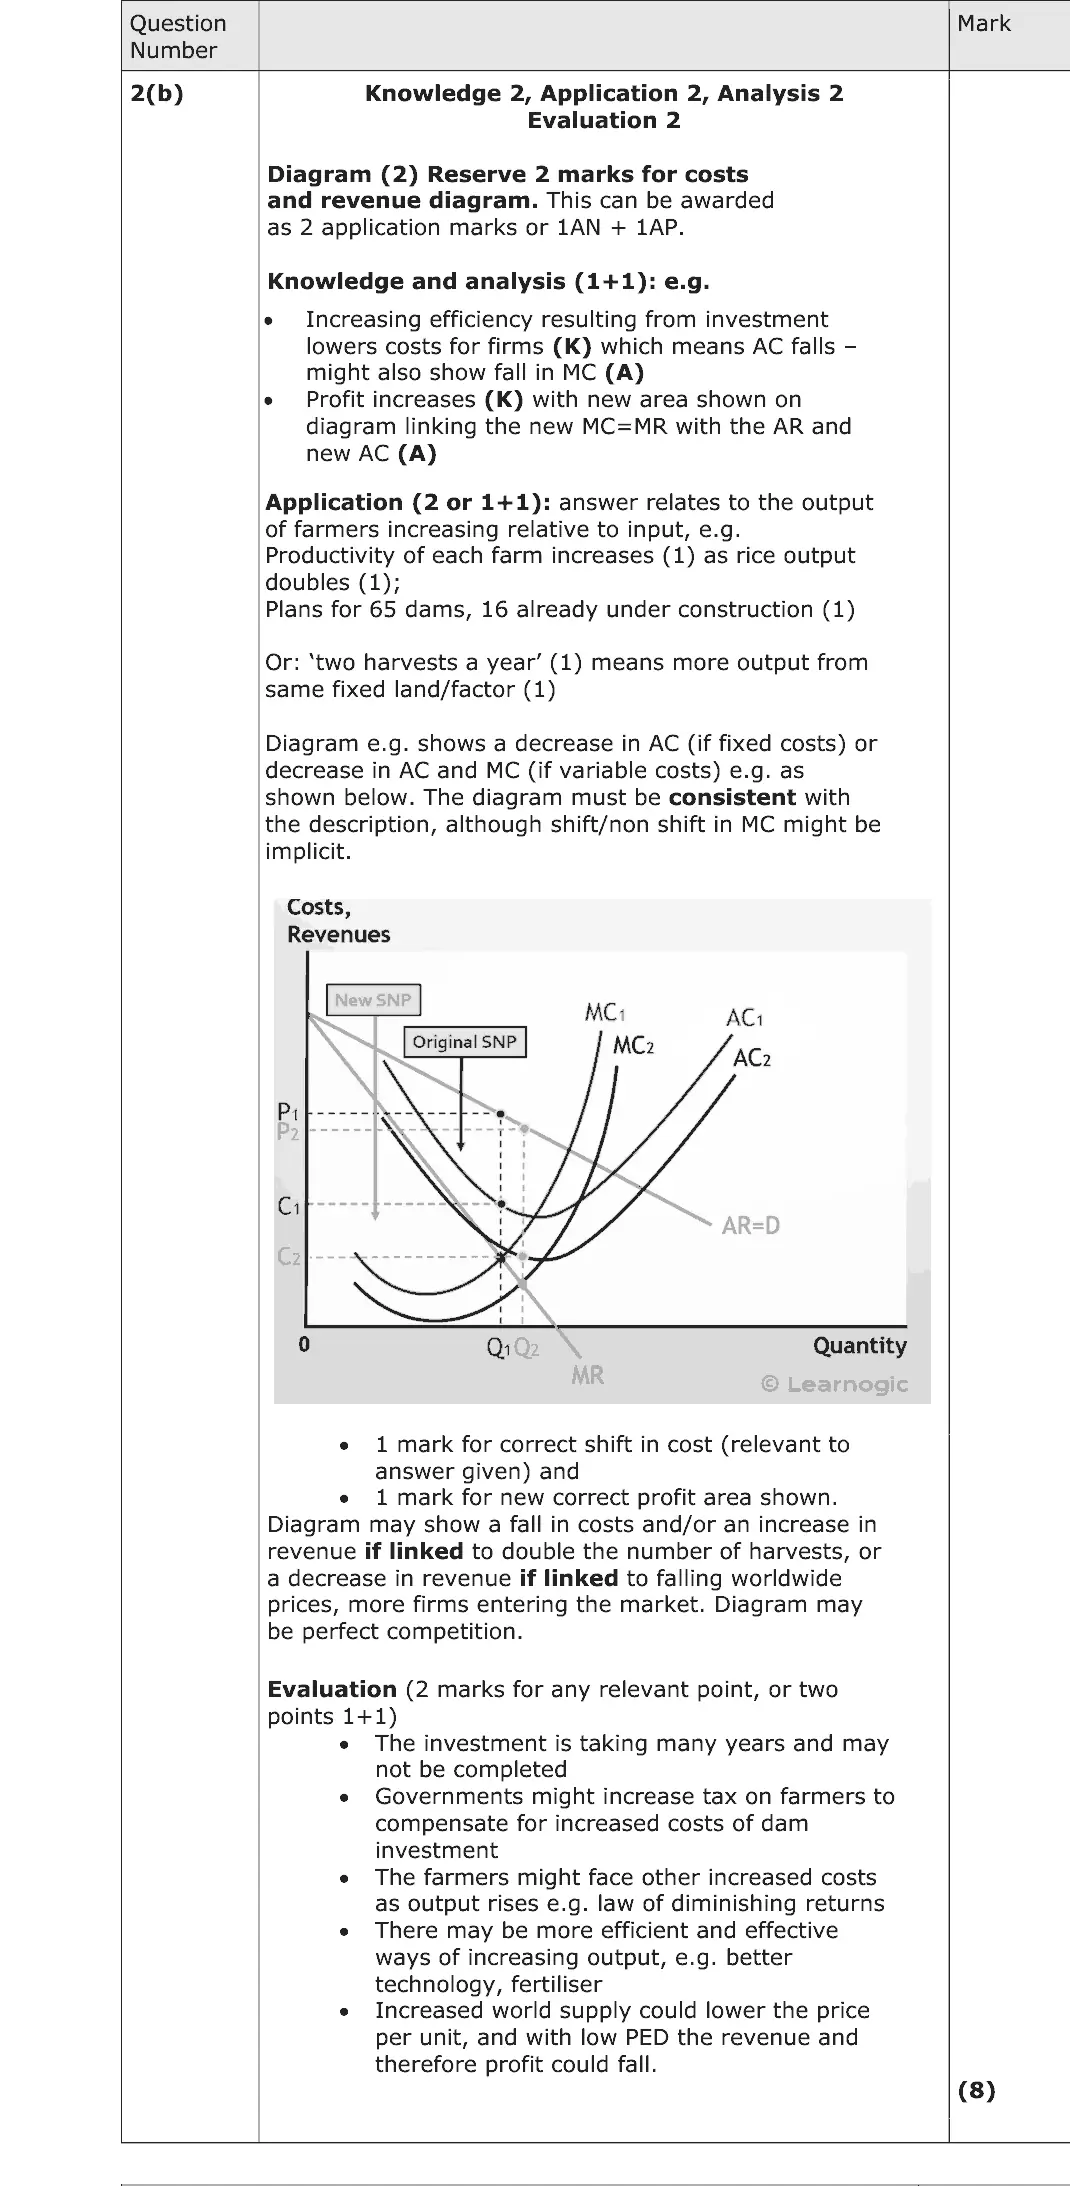
(b) Examine the likely effects on the profitability of Indonesian rice farmers of the government’s increased investment in dams (Extract E, lines 43-48). Use a cost and revenue diagram to support your answer. (8)
June 2019 · Paper 3 · Q2(e) 25 marks AO1=4, AO2=4, AO3=8, AO4=9 25-mark essay Either/or Hard inflation
Data and extracts for question 2Mozambique Figure 2: Interest rates (bank rate of the central bank) and inflation rates of selected African countries, 2017 Selected country Central bank Inflation rate rate of interest (CPI measure) Congo (D.R.) 14% 13.8% Ghana 21% 9.1% Kenya 10% 10.1% Malawi 18% 21.4% Mozambique 21.75% 18.0% Nigeria 14% 21.1% (Source: official government websites, and other news sources, July 2017) Extract D Rising debt levels in Africa Increases in national debt have brought several African governments towards a debt-servicing crisis when the repayment of debt and interest become unsustainable. Between 2010 and 2015, many sub-Saharan countries raised debt totalling more than £20 billion. Back then, with commodity prices soaring and foreign loans available at very 5 low interest rates, everyone agreed that borrowing was the way to grow an economy with expansionary fiscal policy. Since 2015, some African governments – beneficiaries of big debt write-offs at the start of the century – have taken to private debt markets too eagerly, leaving them with heavy repayment schedules at a time of lower commodity prices. 10 Until recently, the International Monetary Fund (IMF) has played down African debt concerns, pointing to better management of public resources and greater transparency. But it was shaken by Mozambique’s default on more than £2 billion of secret loans used to purchase a non-existent tuna-fishing fleet, raising fears of hidden debt in other African countries with similar levels of corruption. The median level of debt in sub-Saharan Africa 15 had risen sharply from 34% of gross domestic product in 2013 to 48% in 2017. Although that is low by international standards, analysts said debt burdens were heavier than they appeared because of most African countries’ low tax base. “The real thing to look for is debt to revenue, or debt-service as a percentage of government spending,” said John Ashbourne, Africa Economist at Capital Economics. In several countries, he said, debt 20 payments were above 20% of government revenue, with an opportunity cost in terms of government spending. (Source: adapted from African debt worries intensify as levels near tipping point by David Pilling © Financial Times 2017 https://www.ft.com/ content/939808dc-b4d8-11e7-a398-73d59db9e399) Extract E Mozambique’s economic stability is being put to the test The economy of Mozambique, which gained independence from Portugal in 1975, has continued to under-perform. Large-scale emigration, especially of skilled workers, economic dependence on South Africa, a severe drought, a prolonged civil war and political tensions have hindered the country’s development. More than half of 5 Mozambique’s 26 million people continue to live below the poverty line. GDP growth declined to 3.6% in 2016 due to fiscal tightening and a slowdown in foreign direct investment. A weak manufacturing sector employs just 3.2% of the population, and is made up of small enterprises (90%), many of which were set up with the aid of microfinance. Traditional export earnings dropped due to depressed global demand. 10 In addition a wide-scale drought seriously affected agricultural production. Foreign currency inflows have weakened – as large-scale gas projects were put on hold, and 14 external lenders suspended direct budget support, as a lesson to be learned from the tuna-fleet scandal. The state budget deficit was 10.7% of GDP in 2017. High interest rates have reduced aggregate demand, and import costs added to inflation following further 15 depreciation of Mozambique’s currency, the metical, to a new low of 100 meticals to £1. Mozambique needs urgently to improve its investment environment and confidence in its institutions. The World Economic Forum’s global competitiveness ranking placed Mozambique 136 out of 137 countries. Longer term, Mozambique’s economic prospects are promising. There has been 20 progress in talks on restoring international confidence in the government’s running of the economy, leading to a lasting and sustainable agreement between rival political groups. The development of gas fields off Mozambique’s coast discovered in 2011 is set to transform the economy, coming into production in the 2020s. A rise in coal and electricity exports should help growth to increase. But in the short term, it remains 25 uncertain whether Mozambique can deliver badly needed economic stability. (Source: adapted from http://www.africaneconomicoutlook.org/en/country-notes/ mozambiqua and https://www.chathamhouse.org/expert/comment/ mozambique-s-stability-being-put-test 6 October 2017 Dr Alex Vines OBE) Extract F Microfinance in Mozambique Microfinance in Mozambique started in the late 1980s through projects initiated by international relief organisations. The sector has expanded to include many private banks and non-government organisations (NGOs), see Figure 3. This has resulted in wider use (over 100 000 borrowers) and many new business start-ups which could not have gained 5 finance from any other source. Evidence suggests that there is unfulfilled demand for microfinance and a large potential for expansion. (Source: adapted from http://www.mftransparency.org/microfinance-pricing/mozambique/) Figure 3: The cost of microfinance loans in Mozambique, 2015 Each symbol represents loans 200% to a number of borrowers (up to 2 000) by one institution. Institution Type Private banks 150% NGO 100% Mean annual percentage rate of interest 50% 0% 40 000 0 20 000 60 000 Loan size (meticals) (Source: http://www.mftransparency.org/microfinance-pricing/mozambique/)
(e) Evaluate the likely microeconomic and macroeconomic effects of relatively high inflation rates in many African countries. (25)
June 2022 · Paper 3 · Q1(b) 8 marks AO1=2, AO2=2, AO3=2, AO4=2 8-mark response Hard price elasticity of demand
Data and extracts for question 1The food delivery industry Figure 1: Market share for third‑party food delivery services in the UK, 2019 1.2% 10.2% 21.3% 67.3% Just Eat Deliveroo Uber Eats Others (Source: adapted from https://onefourzerogroup.com/the‑takeaway‑takeover/) Extract A National Minimum Wage rises are more significant for 23 to 25-year-olds In 2021, the National Minimum Wage main rate, also known as the National Living Wage, rose by 2.2% to £8.91, following a 6.2% rise in 2020. By reducing the age at which people are eligible for the National Living Wage to 23 in 2021, it is estimated that an additional 7.5% of 23 to 25-year-olds could get a 71p an hour pay rise. This amounts to an 8.7% 5 increase, which may cause further financial worries for employers. (Source: adapted from https://www.ndna.org.uk/NDNA/News/Latest_news/2020/ Minimum_wages_to_rise_by_inflation_in_April.aspx) Extract B What is the true cost of the food delivery service? The food delivery industry has boomed in recent years. Just Eat, Uber Eats and Deliveroo all offer very similar services – third‑party food delivery firms that take up to 30% of the price of restaurant meals and deliver them to customers within a certain radius. The average spend per customer is around £15 with a £5 delivery fee, about five times 5 more expensive than cooking at home and the same price as eating in the restaurant. Cash rich, time poor professionals increasingly turn to food delivery. Food delivery comes with many layers of packaging. In the UK, there are 200 million meals annually with around 1.4 billion individual pieces of plastic for heat retention and protection when travelling, but does it really have to be plastic? People tend to 10 order more food, often high in fat, sugar and salt, and don’t even have to get up from their sofa. But there are concerns that the delivery firms are exploiting employees who have no alternative. There is an issue of low pay and informal contracts. Delivery drivers are classed as ‘independent contractors’, and therefore not subject to some employment 15 rights including a guaranteed minimum wage, sick pay, pensions or holiday pay. Drivers are paid either a flat hourly rate, or a fee per delivery. Factors such as delivery distance, speed, how busy it is and whether there are multiple drop‑offs are all factored into how much a driver is paid. Deliveroo says its wages amount to around £10 per hour, but drivers say that during 2020 their pay has been as low as £1 per hour. Drivers are not 20 paid extra for petrol or to maintain their vehicles. Many drivers are recent immigrants or students, who do not have property or savings to fall back on. The government could address this with widening minimum pay legislation to contracted workers, by setting codes of practice, or by setting recommended wage targets. Furthermore, there are health and safety issues for workers. Vehicle safety checks, 25 length of shifts and safety equipment are of concern. However, there are still people who take benefit from working flexibility. (Source: adapted from https://www.theguardian.com/australia‑news/2020/oct/25/home- food-delivery‑what‑is‑the‑most‑ethical‑way‑to‑order‑in and https://digitalcommons.molloy. edu/cgi/viewcontent.cgi?article=1043&context=bus_fac) Extract C Integration in the third‑party food delivery industry The Competition and Markets Authority (CMA) is watching carefully to prevent any one firm having complete control of the food delivery industry. Just Eat, the market leader, agreed to merge with successful Dutch firm Takeaway.com in 2020, creating a new European leader by revenues. It also bought Grubhub in the US, with 20 million active 5 users. Just Eat uses an aggressive pricing strategy, undercutting delivery fees below the average cost of other firms in the market, that will force them to merge in order to gain some economies of scale. Amazon, having failed with its own delivery company Amazon Restaurants in 2018, has bought 16% of Deliveroo. The CMA took over a year to agree to the partial integration, 10 on the argument that Deliveroo would close down without external investment. Amazon has unique expertise in marketing, increasing customer share and, most importantly, efficiency in delivering things. Food delivery is often uneconomical because a single household puts in a single order from a single restaurant at any one time. Tech companies such as Amazon can improve the business: once a meal has been ordered, an 15 app often moves that restaurant to the top of the rankings for that neighbourhood, in the hope of getting a second and third delivery. So why do restaurants turn to these delivery firms? The sheer volume of customers these delivery firms can hold makes it a difficult deal to turn down. But resentment from small business restaurant owners, angry at being wholly dependent on tech companies, is 20 growing. Most restaurants would prefer that customers come in and pick up their orders themselves because they do not have to pay the 30% commission. Restaurant profit margins are small, and the effects of a 20% fall in the external value of the pound since 2016 on food costs are significant, given that over half of their food and drink is sourced outside the UK. 25 (Source: adapted from https://www.ft.com/content/c20f6848‑3c4b‑11ea‑a01a-bae547046735 https://www.ft.com/content/edf8a144‑a101‑4ef8‑80e3‑7d2f1565d35c and https://www.thisismoney.co.uk/money/markets/article‑8138703/Uber‑set‑sell- takeaway-division‑rival‑Deliveroo‑two‑years.html and https://www.ft.com/content/c20f6848-3c4b‑11ea‑a01a‑bae547046735 and https://www.ft.com/content/bed7c4d8-28c1-11ea-9a4f-963f0ec7e134 and https://www.economist.com/1843/2021/01/26/gulp‑the‑secret‑economics-of-food‑delivery)
(b) With reference to Extract B, examine whether the demand for delivered food is price inelastic and income elastic. (8)
June 2022 · Paper 3 · Q2(a) 5 marks AO1=2, AO2=2, AO3=1 Short answer Hard emerging and developing economies
Data and extracts for question 2Sub‑Saharan Africa – growth and development Figure 2: Kenya population, millions, 1960 to 2020 60 53.7 50 42.0 40 millions 32.0 30 23.7 20 16.4 11.3 8.1 10 0 1960 1970 1980 1990 2000 2010 2020 (Source: adapted from Population, total ‑ Kenya | Data (worldbank.org)) Extract D Growth and development in Africa: 'Africa has a massive opportunity as a low‑cost provider of services' The outlook for Africa’s economies is not as simple as the Lewis model of growth and development implies: do more manufacturing or stay poor. Many countries are expanding into areas that economists are starting to call 'industries without smoking 5 chimneys'. Some, such as flower‑exports, may not be classified as manufactured goods in export statistics. But the process of producing flowers looks a lot like factory work and demands many of the same management skills. These industries also deliver many of the benefits of normal manufacturing, including many well‑paid jobs, and greater opportunities. 10 (Source: adapted from https://www.economist.com/special‑report/2020/03/26/many‑of- africas-economies‑are‑doing‑well) Extract E The demography of Kenya – ‘Demography will shape Africa’s future’ Falling birth rates, when accompanied by rising literacy, can help kick‑start growth. In Kenya 39% of the population is below the age of 15, falling from 43% in 2009. The labour force (15–64 years) is 57% and is the fastest growing population group. 6% of the population is over the age of 60. The number of children per family has fallen sharply, 5 from 8.1 children in 1978 to 4.6 children in 2008, and it is projected to possibly reach 2.4 children by 2050. In the 1970s little more than half of children in sub‑Saharan Africa were enrolled in primary school. That share has shot up to almost 100%. The statistic is slightly misleading, since the percentage of children regularly attending schools is nearer 60%. 10 Why does Kenya’s population continue to rise rapidly, while family size declines? There are two reasons. First, due to high fertility in previous decades, there are many more families in Kenya today. So even though families are smaller, the total number of children continues to grow. Second, Kenyans are living longer, with better healthcare – for example, polio was eradicated in 2014. Life expectancy is projected to increase from 15 54 years today to 68 years by 2050. 28% of Kenya is urbanised, and is becoming rapidly more so. By the 2030s it is expected that 36% of Kenyans will live in towns or cities rather than the poorer rural areas. Rich countries are urban countries. No country has ever reached high income levels with low urbanisation. Large urban centres have two distinct economic advantages. First, as more 20 people interact, there is more scope for innovation. Young people need jobs, but they also create jobs. Kenya has an educated workforce and a dynamic service industry, which typically has lower barriers of entry than agriculture or manufacturing, and provides opportunities for young entrepreneurs. Second, larger groups of population living in close proximity allow for economies of scale. 25 In light of these facts, Kenya’s future pattern of population growth can be a force of good. A large urbanising and well‑educated population tends to generate a strong middle class and vibrant private sector. Economic development may be easier to achieve and sustain – though it is not guaranteed. (Source: adapted from https://www.economist.com/special‑report/2020/03/26/ africas‑population‑will‑double‑by‑2050 and https://kenya.unfpa.org/sites/default/files/pub‑pdf/state_of_kenya_population_ report_2020.pdf and https://www.worldbank.org/en/news/opinion/2010/04/28/ demographic‑transition‑growth‑kenya) Extract F Kenya has an absolute advantage in cut flowers In the UK, 80% of cut flowers come via the Netherlands, although a significant proportion come from Kenya. Some Kenyan flowers come straight to the UK on direct flights from Nairobi, where entire terminals at certain airports are dedicated to flights exporting flowers. 5 Kenya flower production has three major advantages over the Netherlands: areas of high altitude with cool nights, which many flowers benefit from, proximity to the equator for maximum hours of sunlight, and cheaper labour. This means an end to seasonal production and the beginning of a 365‑day‑a‑year absolute advantage. The Netherlands has cost advantages in machinery and transport equipment, not flowers. 10 Cut flowers are now Kenya’s second largest export after tea, contributing around 1% of the country’s GDP. They are also one of the country’s largest sources of employment, with over 100 000 people working directly in the flower industry and an estimated two million indirectly. (Source: adapted from: https://www.economist.com/middle‑east‑and‑africa/2021/02/11/ kenyas-floral‑exports‑are-blooming‑once‑more) Extract G Changes in interest rates in sub‑Saharan Africa When Robert Matsiko was a young man his grain‑milling business in eastern Africa was destroyed by fire. Now, after building it back up from the ashes, he is being hurt by high interest rates. To buy a new machine he must borrow from a bank at an annual rate of 22%. 'You fear to do that,' Mr Matsiko says. Many other entrepreneurs feel the same, 5 which stops their businesses from growing, although very small firms can get help from microfinance schemes. Kenya’s central bank rate has fallen from over 20% to 7% in the last decade, but the rates charged to small businesses and individuals are much higher than the central bank interest rate. In sub‑Saharan Africa, the gap between saving and borrowing rates 10 is higher than anywhere else. The average bank lends at 6.8% above the central bank interest rate. Mobile banking, credit‑information sharing and innovation have helped to bring borrowing costs down. But until birth rates fall, interest rates will stay relatively high, because families with many children cannot afford to save. (Source: adapted from https://www.economist.com/finance‑and‑economics/2020/05/21/ why-interest‑rates-are‑so-high‑in-africa)
(a) Explain what is meant by the Lewis model. Refer to Extract D in your answer. (5)
June 2022 · Paper 3 · Q2(c) 12 marks AO1=2, AO2=2, AO3=4, AO4=4 12-mark response Hard globalisation and trade
Data and extracts for question 2Sub‑Saharan Africa – growth and development Figure 2: Kenya population, millions, 1960 to 2020 60 53.7 50 42.0 40 millions 32.0 30 23.7 20 16.4 11.3 8.1 10 0 1960 1970 1980 1990 2000 2010 2020 (Source: adapted from Population, total ‑ Kenya | Data (worldbank.org)) Extract D Growth and development in Africa: 'Africa has a massive opportunity as a low‑cost provider of services' The outlook for Africa’s economies is not as simple as the Lewis model of growth and development implies: do more manufacturing or stay poor. Many countries are expanding into areas that economists are starting to call 'industries without smoking 5 chimneys'. Some, such as flower‑exports, may not be classified as manufactured goods in export statistics. But the process of producing flowers looks a lot like factory work and demands many of the same management skills. These industries also deliver many of the benefits of normal manufacturing, including many well‑paid jobs, and greater opportunities. 10 (Source: adapted from https://www.economist.com/special‑report/2020/03/26/many‑of- africas-economies‑are‑doing‑well) Extract E The demography of Kenya – ‘Demography will shape Africa’s future’ Falling birth rates, when accompanied by rising literacy, can help kick‑start growth. In Kenya 39% of the population is below the age of 15, falling from 43% in 2009. The labour force (15–64 years) is 57% and is the fastest growing population group. 6% of the population is over the age of 60. The number of children per family has fallen sharply, 5 from 8.1 children in 1978 to 4.6 children in 2008, and it is projected to possibly reach 2.4 children by 2050. In the 1970s little more than half of children in sub‑Saharan Africa were enrolled in primary school. That share has shot up to almost 100%. The statistic is slightly misleading, since the percentage of children regularly attending schools is nearer 60%. 10 Why does Kenya’s population continue to rise rapidly, while family size declines? There are two reasons. First, due to high fertility in previous decades, there are many more families in Kenya today. So even though families are smaller, the total number of children continues to grow. Second, Kenyans are living longer, with better healthcare – for example, polio was eradicated in 2014. Life expectancy is projected to increase from 15 54 years today to 68 years by 2050. 28% of Kenya is urbanised, and is becoming rapidly more so. By the 2030s it is expected that 36% of Kenyans will live in towns or cities rather than the poorer rural areas. Rich countries are urban countries. No country has ever reached high income levels with low urbanisation. Large urban centres have two distinct economic advantages. First, as more 20 people interact, there is more scope for innovation. Young people need jobs, but they also create jobs. Kenya has an educated workforce and a dynamic service industry, which typically has lower barriers of entry than agriculture or manufacturing, and provides opportunities for young entrepreneurs. Second, larger groups of population living in close proximity allow for economies of scale. 25 In light of these facts, Kenya’s future pattern of population growth can be a force of good. A large urbanising and well‑educated population tends to generate a strong middle class and vibrant private sector. Economic development may be easier to achieve and sustain – though it is not guaranteed. (Source: adapted from https://www.economist.com/special‑report/2020/03/26/ africas‑population‑will‑double‑by‑2050 and https://kenya.unfpa.org/sites/default/files/pub‑pdf/state_of_kenya_population_ report_2020.pdf and https://www.worldbank.org/en/news/opinion/2010/04/28/ demographic‑transition‑growth‑kenya) Extract F Kenya has an absolute advantage in cut flowers In the UK, 80% of cut flowers come via the Netherlands, although a significant proportion come from Kenya. Some Kenyan flowers come straight to the UK on direct flights from Nairobi, where entire terminals at certain airports are dedicated to flights exporting flowers. 5 Kenya flower production has three major advantages over the Netherlands: areas of high altitude with cool nights, which many flowers benefit from, proximity to the equator for maximum hours of sunlight, and cheaper labour. This means an end to seasonal production and the beginning of a 365‑day‑a‑year absolute advantage. The Netherlands has cost advantages in machinery and transport equipment, not flowers. 10 Cut flowers are now Kenya’s second largest export after tea, contributing around 1% of the country’s GDP. They are also one of the country’s largest sources of employment, with over 100 000 people working directly in the flower industry and an estimated two million indirectly. (Source: adapted from: https://www.economist.com/middle‑east‑and‑africa/2021/02/11/ kenyas-floral‑exports‑are-blooming‑once‑more) Extract G Changes in interest rates in sub‑Saharan Africa When Robert Matsiko was a young man his grain‑milling business in eastern Africa was destroyed by fire. Now, after building it back up from the ashes, he is being hurt by high interest rates. To buy a new machine he must borrow from a bank at an annual rate of 22%. 'You fear to do that,' Mr Matsiko says. Many other entrepreneurs feel the same, 5 which stops their businesses from growing, although very small firms can get help from microfinance schemes. Kenya’s central bank rate has fallen from over 20% to 7% in the last decade, but the rates charged to small businesses and individuals are much higher than the central bank interest rate. In sub‑Saharan Africa, the gap between saving and borrowing rates 10 is higher than anywhere else. The average bank lends at 6.8% above the central bank interest rate. Mobile banking, credit‑information sharing and innovation have helped to bring borrowing costs down. But until birth rates fall, interest rates will stay relatively high, because families with many children cannot afford to save. (Source: adapted from https://www.economist.com/finance‑and‑economics/2020/05/21/ why-interest‑rates-are‑so-high‑in-africa)
(c) Using the example of cut flowers (Extract F), discuss how the concept of absolute advantage may lead to growth in Kenya. Use numerical or diagrammatic analysis in your answer. (12)
June 2023 · Paper 3 · Q2(d) 25 marks AO1=4, AO2=4, AO3=8, AO4=9 25-mark essay Either/or Hard aggregate demandlabour market
Data and extracts for question 2Changes in the nature of UK towns and cities Figure 3: Growing and declining high street firms – net change in store numbers, 2013–2022 Barbers Beauty salons Cafés and tearooms Nail salons Restaurants Fashion shops Estate agents Post Office services Clothes – women Banks and other financial institutions –4 000 –3 000 –2 000 –1 000 0 1 000 2 000 3 000 4 000 5 000 Net increase/decrease in store numbers (Source: adapted from https://www2.deloitte.com/uk/en/pages/consumer- business/articles/what-next-for-the-high-street.html) Figure 4: House price changes in the UK (%), 2005 to 2022 15 10 5 0 (%) –5 –10 –15 –20 2005 2010 2015 2020 2022 (Source: adapted from https://www.theguardian.com/money/2022/sep/28/ uk-house-prices-may-fall-20-amid-mortgage-carnage-warn-experts) Extract C What next for the high street? A high street is typically found in all UK towns and cities. Shops normally encountered in a typical UK high street can include successful small firms such as independent food retailers, cafés, nail and beauty salons, restaurants and charity shops. They differ from out‑of‑town shopping centres by being more diverse, family‑run and offering local or 5 personalised services. Customers are often very loyal. However, the high street may often have limited access by car or expensive parking facilities. The rise of online retailers such as Amazon and eBay have placed huge pressures on UK high streets, with many well‑known shops – and even successful retail chains – forced to close due to lost business. Many high street firms cannot compete on price with online 10 retailers who – because they frequently have very low fixed costs – can significantly undercut the high street shops on price. Even before online shopping, competition was eroding high street activity, with out‑of‑town retail parks that were not necessarily cheaper but provide a larger range of shops and offer plentiful parking. They offer a shopping experience that other retailing 15 cannot match – pleasant, safe pedestrian shopping, a clean environment, fun activities for children and spend‑the‑day‑there potential. While the list of retail and leisure failures might suggest that the high street does not have a future, some analysts argue the opposite. Many believe that the high street is ideally placed to reinvent itself in response to the structural shift in working and 20 shopping patterns that has resulted from the global health crisis 2020–22. The perceived weaknesses of the high street model – its fragmented ownership, lack of centralised coordination and high vacancy rates – become strengths as they lower the barriers to entry for new concepts and operators. They also enable risk taking and innovation that will ultimately lead to a more flourishing and diverse environment on our local high 25 streets. It should be possible for small firms to flourish even when staff shortages are pushing up wages in the high street, and house price falls damage consumer confidence and spending on perceived luxuries. (Source: adapted from https://www.designingbuildings.co.uk/ and https://www2.deloitte. com/uk/en/pages/consumer-business/articles/what-next-for-the-high-street.html) Extract D UK house prices may fall up to 20% Turmoil on the UK financial markets has prompted analysts to predict that house prices could fall dramatically, and many lenders in the mortgage sector are withdrawing deals. People coming to the end of their fixed‑rate mortgages are seeing rises from 2% to over 5.5%, with increases in the cost of borrowing of over £5 200 a year by 2024 for the 5 average mortgage in the UK. Many people think UK house prices will never fall, but analysts say the fall could be between 10% and 20%. One mortgage lender said that a lack of housing supply will not keep house prices up when mortgage interest rates are somewhere between 5% and 7%. He claimed that ‘the decade‑long property bubble is about to burst […] It’s a buyer’s market now’. The 10 greatest impact will be seen in the southeast of England. (Source: adapted from https://www.theguardian.com/money/2022/sep/28/ uk-house-prices-may-fall-20-amid-mortgage-carnage-warn-experts) Extract E UK job vacancies hit record 1.1 million as labour shortages increase The ratio of jobless people to vacancies is 1.45 to 1, lower than at any point in the last 40 years. Social care for example has 300 000 current unfilled posts. ‘Today’s figures show that labour shortages are now affecting the whole economy,’ said one analyst. ‘There are almost a million people fewer in the labour market, largely due to 5 younger people staying in education and older people dropping out of the workforce.’ The inactivity rate is 21.1%, and many people are not returning to work after the global health crisis. ‘People seeking work do not have the skills or availability that employers need,’ said Kitty Ussher, chief economist at the Institute of Directors. Firms offering higher wages does not solve the issue. 10 (Source: adapted from https://www.ft.com/content/463f4fbd- 3a50-45b5-891c-5cb5ba623df8)
(d) Evaluate the microeconomic and macroeconomic effects of falling house prices. (25)
June 2023 · Paper 3 · Q2(e) 25 marks AO1=4, AO2=4, AO3=8, AO4=9 25-mark essay Either/or Hard labour marketinflation
Data and extracts for question 2Changes in the nature of UK towns and cities Figure 3: Growing and declining high street firms – net change in store numbers, 2013–2022 Barbers Beauty salons Cafés and tearooms Nail salons Restaurants Fashion shops Estate agents Post Office services Clothes – women Banks and other financial institutions –4 000 –3 000 –2 000 –1 000 0 1 000 2 000 3 000 4 000 5 000 Net increase/decrease in store numbers (Source: adapted from https://www2.deloitte.com/uk/en/pages/consumer- business/articles/what-next-for-the-high-street.html) Figure 4: House price changes in the UK (%), 2005 to 2022 15 10 5 0 (%) –5 –10 –15 –20 2005 2010 2015 2020 2022 (Source: adapted from https://www.theguardian.com/money/2022/sep/28/ uk-house-prices-may-fall-20-amid-mortgage-carnage-warn-experts) Extract C What next for the high street? A high street is typically found in all UK towns and cities. Shops normally encountered in a typical UK high street can include successful small firms such as independent food retailers, cafés, nail and beauty salons, restaurants and charity shops. They differ from out‑of‑town shopping centres by being more diverse, family‑run and offering local or 5 personalised services. Customers are often very loyal. However, the high street may often have limited access by car or expensive parking facilities. The rise of online retailers such as Amazon and eBay have placed huge pressures on UK high streets, with many well‑known shops – and even successful retail chains – forced to close due to lost business. Many high street firms cannot compete on price with online 10 retailers who – because they frequently have very low fixed costs – can significantly undercut the high street shops on price. Even before online shopping, competition was eroding high street activity, with out‑of‑town retail parks that were not necessarily cheaper but provide a larger range of shops and offer plentiful parking. They offer a shopping experience that other retailing 15 cannot match – pleasant, safe pedestrian shopping, a clean environment, fun activities for children and spend‑the‑day‑there potential. While the list of retail and leisure failures might suggest that the high street does not have a future, some analysts argue the opposite. Many believe that the high street is ideally placed to reinvent itself in response to the structural shift in working and 20 shopping patterns that has resulted from the global health crisis 2020–22. The perceived weaknesses of the high street model – its fragmented ownership, lack of centralised coordination and high vacancy rates – become strengths as they lower the barriers to entry for new concepts and operators. They also enable risk taking and innovation that will ultimately lead to a more flourishing and diverse environment on our local high 25 streets. It should be possible for small firms to flourish even when staff shortages are pushing up wages in the high street, and house price falls damage consumer confidence and spending on perceived luxuries. (Source: adapted from https://www.designingbuildings.co.uk/ and https://www2.deloitte. com/uk/en/pages/consumer-business/articles/what-next-for-the-high-street.html) Extract D UK house prices may fall up to 20% Turmoil on the UK financial markets has prompted analysts to predict that house prices could fall dramatically, and many lenders in the mortgage sector are withdrawing deals. People coming to the end of their fixed‑rate mortgages are seeing rises from 2% to over 5.5%, with increases in the cost of borrowing of over £5 200 a year by 2024 for the 5 average mortgage in the UK. Many people think UK house prices will never fall, but analysts say the fall could be between 10% and 20%. One mortgage lender said that a lack of housing supply will not keep house prices up when mortgage interest rates are somewhere between 5% and 7%. He claimed that ‘the decade‑long property bubble is about to burst […] It’s a buyer’s market now’. The 10 greatest impact will be seen in the southeast of England. (Source: adapted from https://www.theguardian.com/money/2022/sep/28/ uk-house-prices-may-fall-20-amid-mortgage-carnage-warn-experts) Extract E UK job vacancies hit record 1.1 million as labour shortages increase The ratio of jobless people to vacancies is 1.45 to 1, lower than at any point in the last 40 years. Social care for example has 300 000 current unfilled posts. ‘Today’s figures show that labour shortages are now affecting the whole economy,’ said one analyst. ‘There are almost a million people fewer in the labour market, largely due to 5 younger people staying in education and older people dropping out of the workforce.’ The inactivity rate is 21.1%, and many people are not returning to work after the global health crisis. ‘People seeking work do not have the skills or availability that employers need,’ said Kitty Ussher, chief economist at the Institute of Directors. Firms offering higher wages does not solve the issue. 10 (Source: adapted from https://www.ft.com/content/463f4fbd- 3a50-45b5-891c-5cb5ba623df8)
(e) Evaluate the microeconomic and macroeconomic effects of labour shortages in the UK, or a developed economy of your choice. (25)
June 2025 · Paper 3 · Q2(a) 5 marks AO1=2, AO2=2, AO3=1 Diagram Hard indirect taxes and subsidies
Data and extracts for question 2Sources for use with SECTION B Read Figure 3 and the following Extracts (E to G) before answering Question 2. The economy of India Figure 3: Selected economic data for India, 2006–2021 Human GDP per capita % people living in Year Development (US$) absolute poverty Index (HDI) value 2006 820.0 0.611 55.1 2016 1 714.3 0.624 27.7 2021 2 238.1 0.633 16.4 (Source adapted from: https://www.statista.com/statistics/1272613/india-multidimensional- poverty-index/; https://data.worldbank.org/indicator/; UN Human Development Reports) Extract E 135 million Indians escape absolute poverty in recent years Absolute poverty in India, measured by the number of people living on under US$2.15 a day, has fallen dramatically over the last 15 years. The government’s dedicated focus on improving access to sanitation, nutrition, cooking oil, banking services, drinking water and electricity has led to significant advances in these 5 areas. The $2.3 million provision of subsidised cooking oil has positively transformed lives, with a 14.6 percentage points improvement in the access to cooking oil. (Source adapted from: https://pib.gov.in/) Extract F Buffer stocks in India The Indian government is required to maintain a buffer stock of 11 million tonnes of wheat and 10 million tonnes of rice. The grains are purchased from farmers at the minimum support price and stored in secure warehouses across the country. India, once troubled by famine, has more recently managed to remain self-sufficient in 5 most food categories except edible oils, and is the world’s largest rice exporter. Even during the global health crisis 2020-2022, when the government distributed free food to nearly 800 million people, buffer stocks ran down but not out. Farmers are encouraged to produce more without any consideration of sustainability. (Source adapted from: https://ig.ft.com/india-population/) Extract G Population growth in India “The greatest obstacle in the path of overall economic development is the alarming rate of population growth,” was one Indian government minister’s view in 1967. In the 1970s, the Indian government took radical measures to try to prevent population growth, with little success. 5 Then, in the 1980s and 1990s, India began opening up its economy to the private sector. Policymakers began viewing a growing young population in the form of the so-called demographic dividend – when a majority of a country’s population is of working age (15-64 years) – as an engine for further economic development. In May 2023 India took over from China as the country with the highest population reaching 1.4 billion. However, 10 it needs enough well-paying jobs designed to serve the modern, urban economy. (Source adapted from: https://www.aljazeera.com/features/2023/4/18/overtaking-chinas- population-will-india-gain-or-lose)
(a) Using a demand and supply diagram, explain the cost of a subsidy on the market for cooking oil to the Indian government (Extract E, line 6). (5)
November 2021 · Paper 3 · Q2(a) 5 marks AO1=2, AO2=2, AO3=1 Short answer Hard public finances and taxation
Data and extracts for question 2The German economy Figure 1: German government budget balance, percentage of GDP, 2010 to 2019 1.9 2 1.5 1.2 1.2 0.9 0.6 0 0 –0.1 –1 % of GDP –2 –4 –4.2 –6 2010 2012 2014 2016 2018 2020 (Source adapted from: The Economist Nov 14th 2019) Figure 2: German national debt, percentage of GDP, 2010 to 2019 85 80 75 70 % of GDP 65 60 55 0 2010 2012 2014 2016 2018 2020 (Source adapted from: The Economist Nov 14th 2019) Figure 3: Annual percentage change in real GDP, Germany and average of developed economies, 2005 to 2021 (forecasted data for 2020 and 2021) 4 2 0 % –2 –4 –6 2005 2010 2015 2020 Germany Average of developed economies (Source adapted from: IMF and German Federal Statistical Office) Figure 4: Unemployment rate in Germany, percentage of labour force, 2005 to 2020 (2020 figure is forecasted) 12.5 11 . 7 % 10 . 8 % 10.0 9 % 8 . 1 % 7 . 7 % 7 . 8 % 7.5 7 . 1 % 6 . 8 % 6 . 9 % 6 . 7 % 6 . 4 % 6 . 1 % 6 . 1 % % 5 . 7 % 5 . 2 % 5 % 5.0 2.5 0 (Source adapted from: bundesagentur für arbeit.de and https://www.ft.com/ content/5486b247-c73e-4887-a2b2-528b23e301a6) Extract C Why Germany keeps to budget rules despite a slowdown in growth Germany’s economic boom is over, as it has entered recession. During the last ten years of economic growth well over 4 million jobs were created. The fear of recession has revived a debate in Germany: should the government spend more to stimulate growth? It is written into the German constitution that the fiscal 5 deficit cannot be greater than 0.35% of GDP, once the effects of the economic cycle have been removed. Germany’s budget has been in surplus since 2014 and the government is always reluctant to increase spending which would create a deficit. In 2018, aided by booming employment and low interest costs on existing debt, the budget ran to a surplus 1.9% of GDP. 10 Germany’s main trading partners have long been angered by German fiscal policy. The French President criticised Germany’s budget and current account surpluses that “always occur at the expense of others”. Large parts of Germany’s infrastructure need significant investment. As the economy has slowed, a decision to run a balanced-budget policy has become harder to defend. In 15 wealthy regions of Germany, crumbling schools have been closed for fear of collapse, and information and mobile technology on a wide scale needs to be modernised. The World Economic Forum reported that accessibility of fibre optic broadband also “remains the privilege of the few”. However, private sector firms, such as major motor manufacturers, are still willing to invest in new technology and the profitability of some of these 20 firms, in the long run, benefits as a result. The state development bank puts Germany’s investment shortfall at €138 billion (£120 billion). Arguments for a much more expansionary fiscal policy have failed to influence government policy. Big government programmes, such as a recent package to reduce Germany’s carbon emissions, are only implemented when they satisfy fiscal rules. 25 (Source adapted from: The Economist Nov 14th 2019 and https://www.ft.com/content/3cec4908-d164-11e9-8367-807ebd53ab77 7th September 2019 and https://www.ft.com/content/198f072e-4e42-11ea-95a0-43d18ec715f5 and https://www.ft.com/content/d89d9404-c586-11e9-a8e9-296ca66511c9 and https://www.ft.com/content/8f87c03c-93dc-11e8-b67b-b8205561c3fe) Extract D Germany drops to number 7 in the Global Competitiveness Index Despite being the largest economy in the European Union, Germany’s competitiveness is declining, according to the World Economic Forum (WEF). Germany dropped four places in the WEF’s Global Competitiveness Index, coming in as the seventh-most competitive economy. Out of the 103 indicators used in the report, Germany received lower scores in 5 53 areas in 2019. (Source: https://www.dw.com/en/germany-falls-in-global-competitiveness- ranking/a-50745071 8 October 2019)
(a) Explain one reason why a country such as Germany wants to avoid an increase in the national debt relative to GDP (Figure 2). (5)

Work with an Edexcel economics tutor

Want to work through the hard ones with a tutor? Message us.

Prefer email? Send an enquiry

If you are under 18, please include a parent's contact details. Enquiries go to enquiries@economicsaleveltutor.com and are deleted once handled. All tutoring is online.