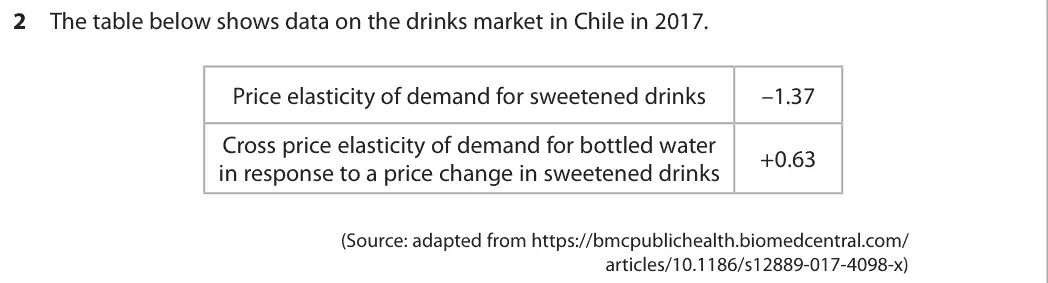June 2022: Paper 1

100 marks · 19 question parts · Paper, mark scheme and report on Pearson's site

Question by question

QTopicMarksAOType
1(a) Supply, demand and price determination 1AO3=1Multiple choice
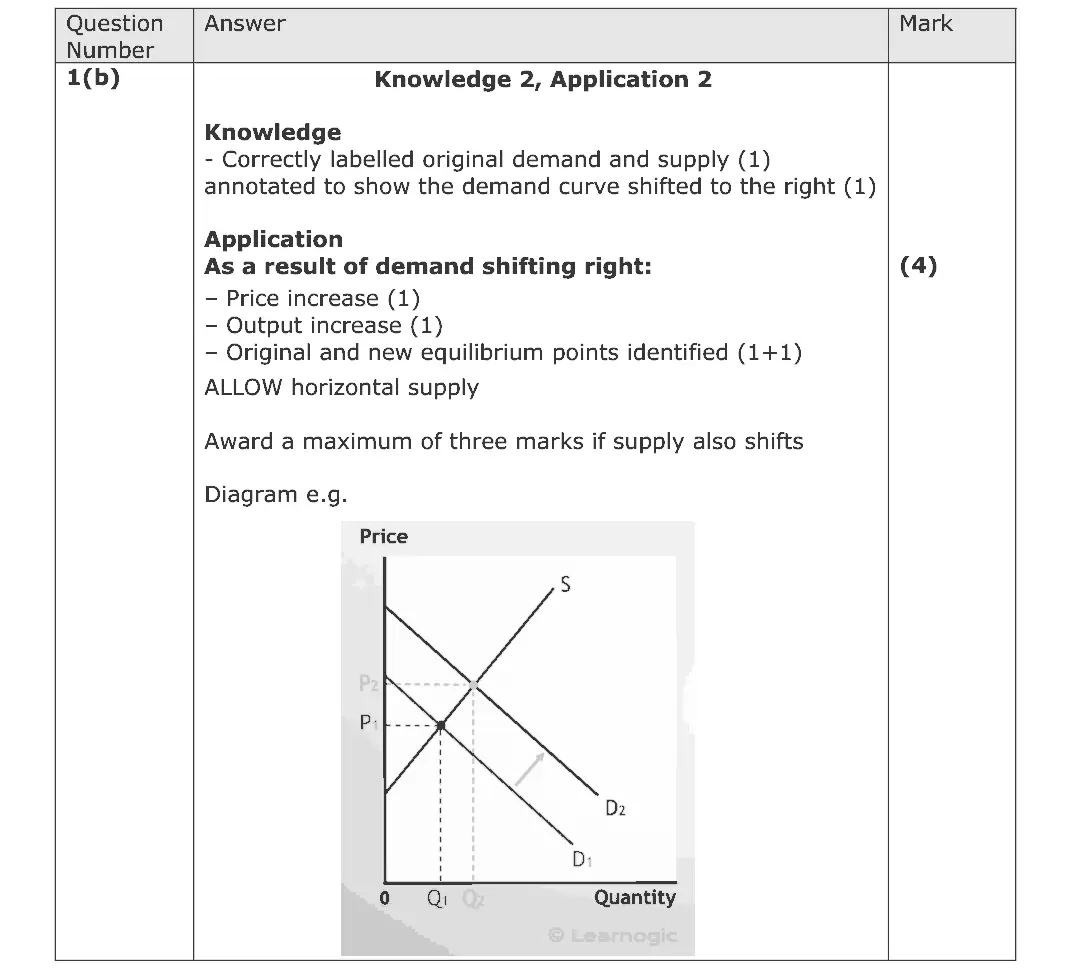
1(b) Supply, demand and price determination 4AO1=2,AO2=2Diagram
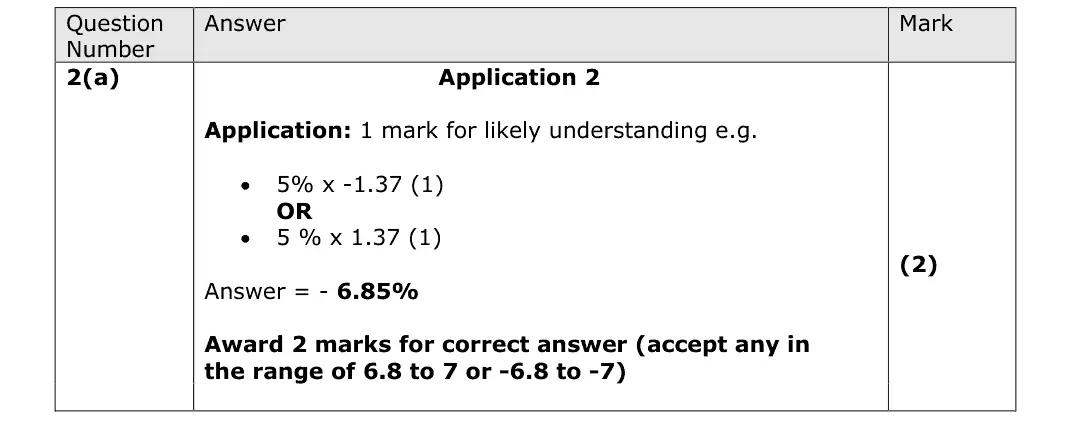
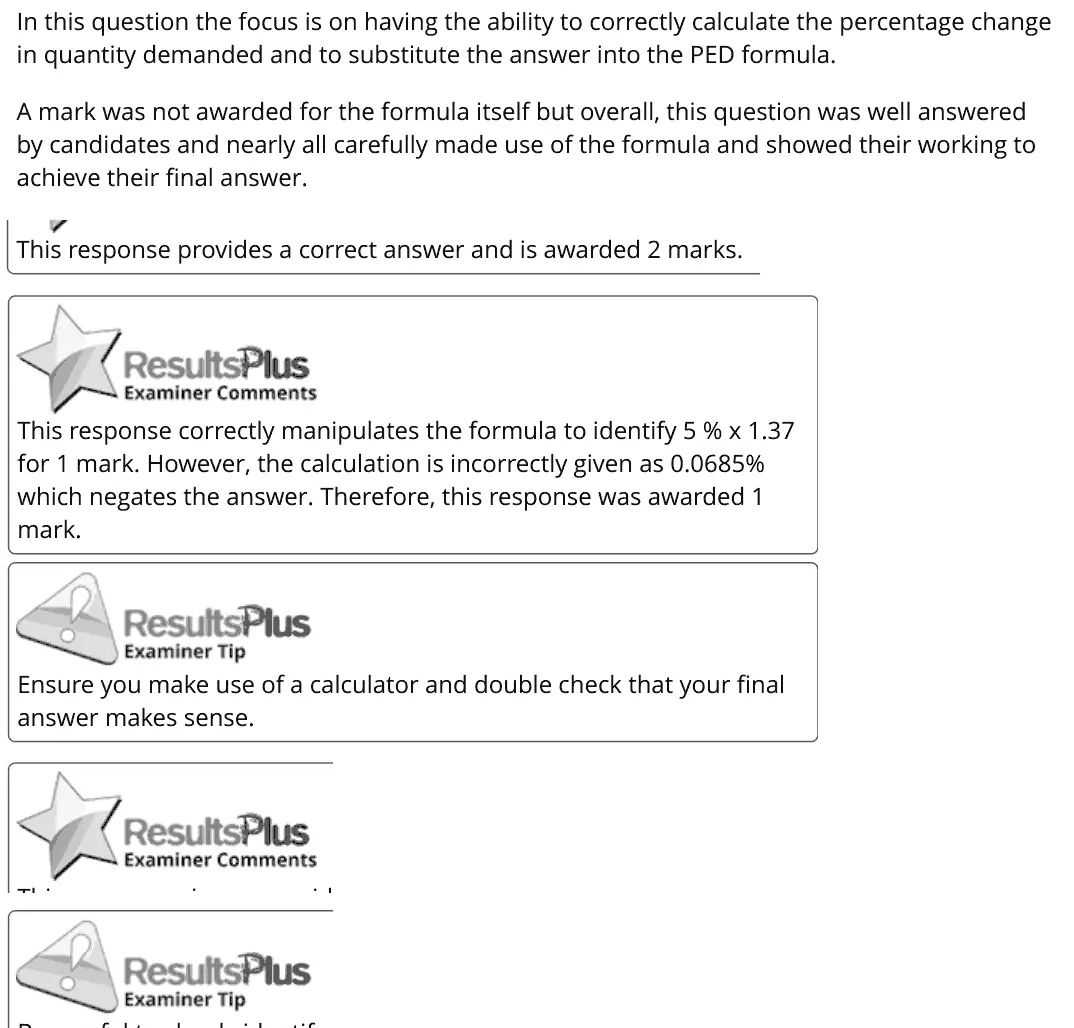
2(a) Price, income and cross elasticities of demand 2AO2=2Calculation
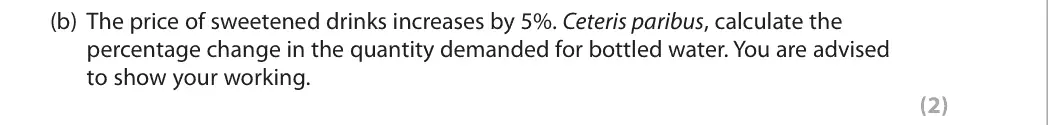
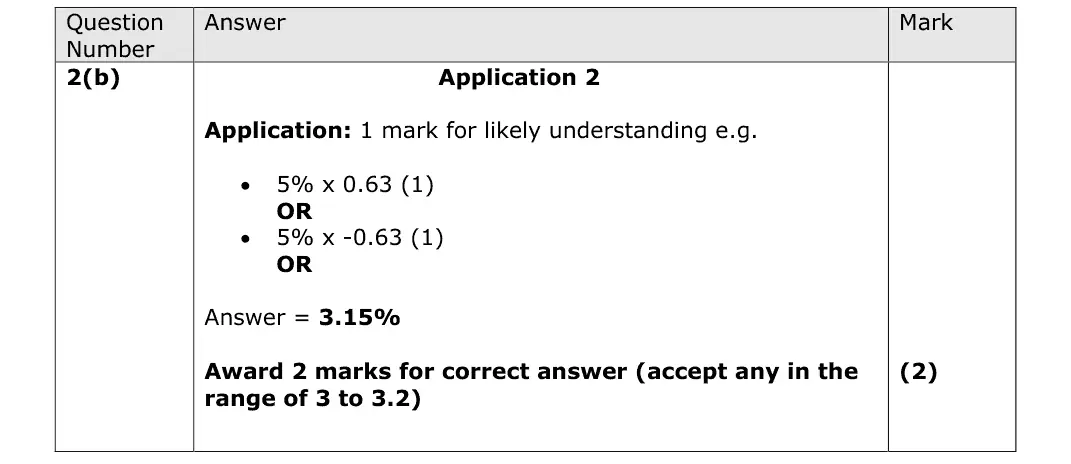
2(b) Price, income and cross elasticities of demand 2AO2=2Calculation
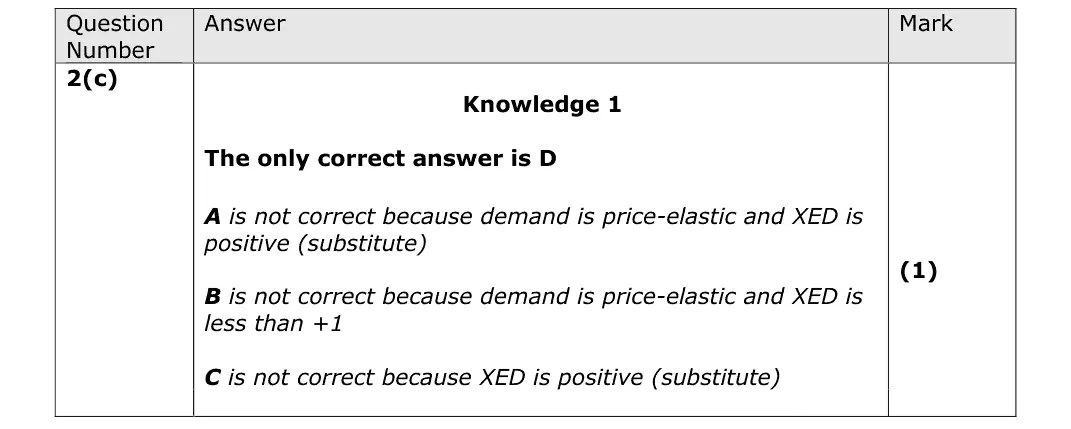
2(c) Price, income and cross elasticities of demand 1AO1=1Multiple choice
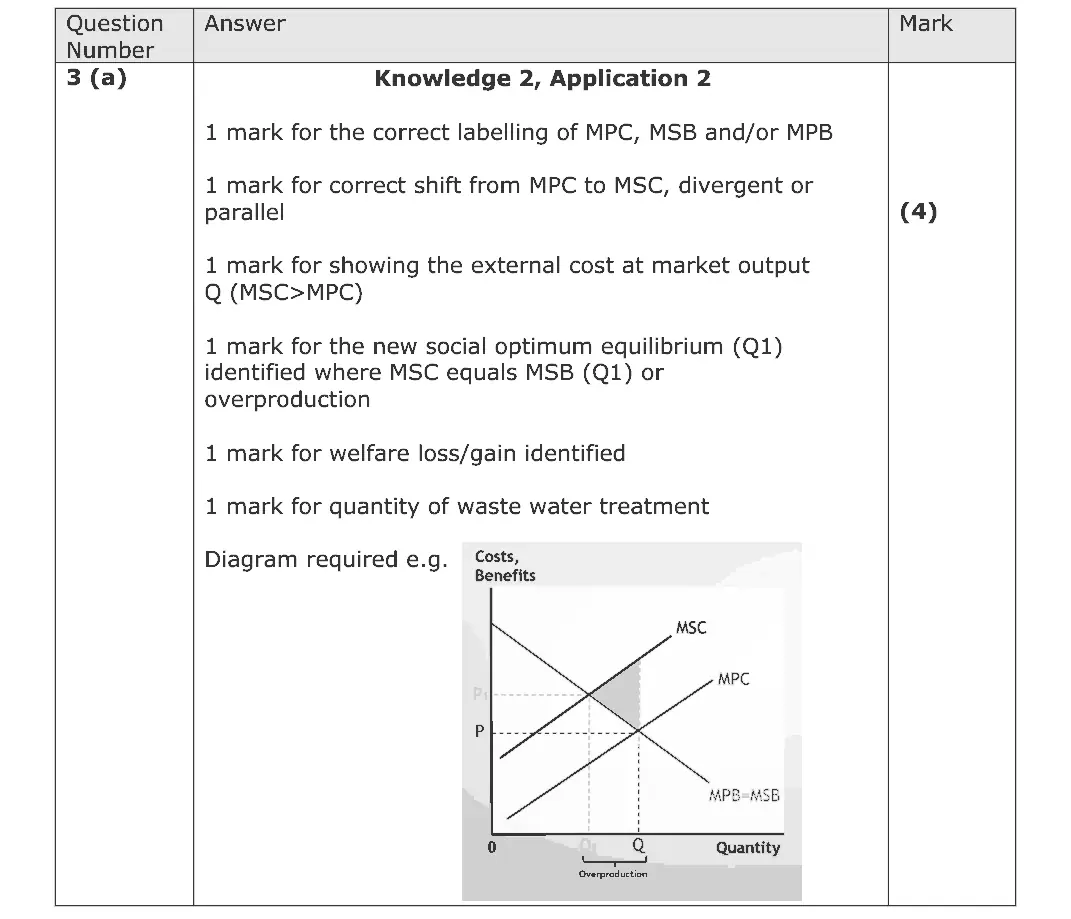
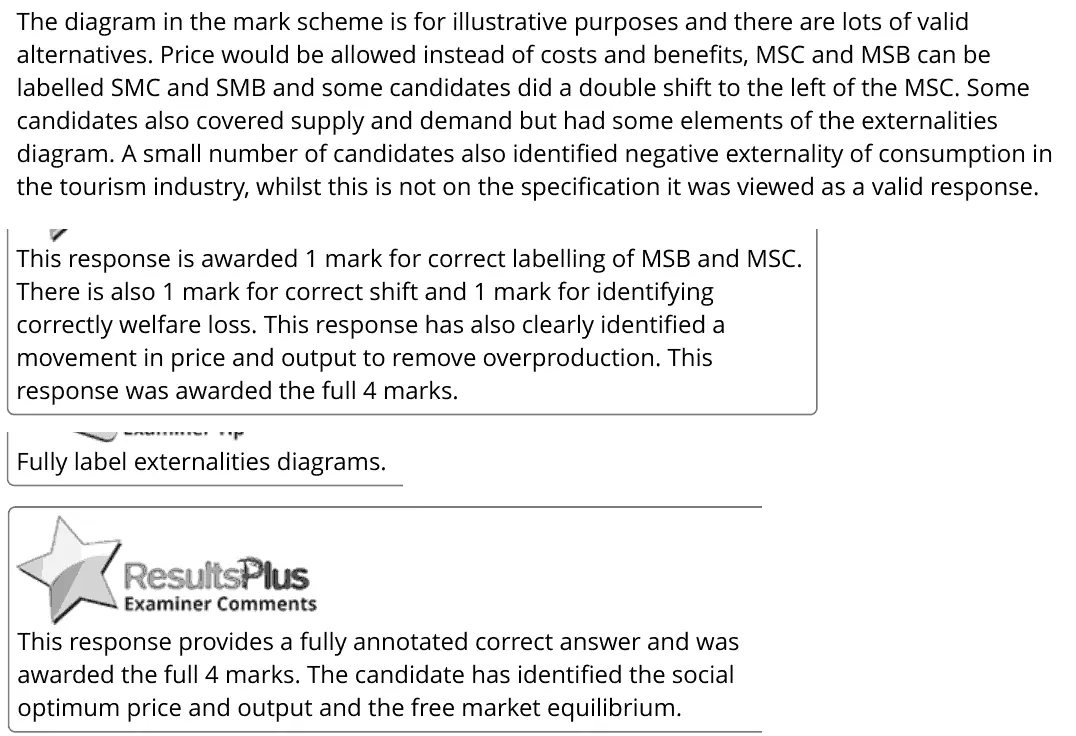
3(a) Market failure and externalities 4AO1=2,AO2=2Diagram
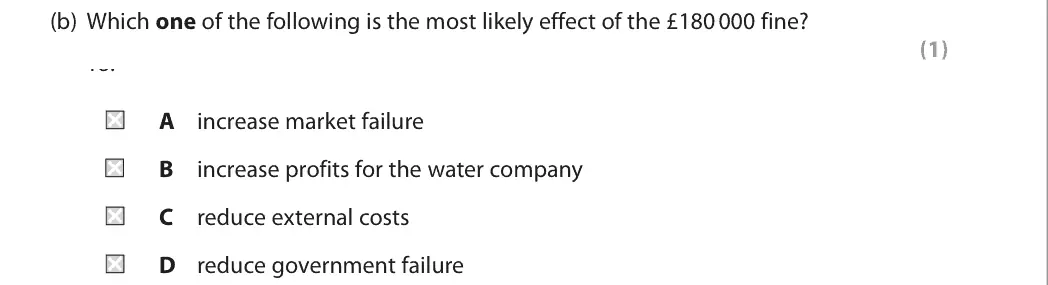
3(b) Government intervention in markets 1AO3=1Multiple choice
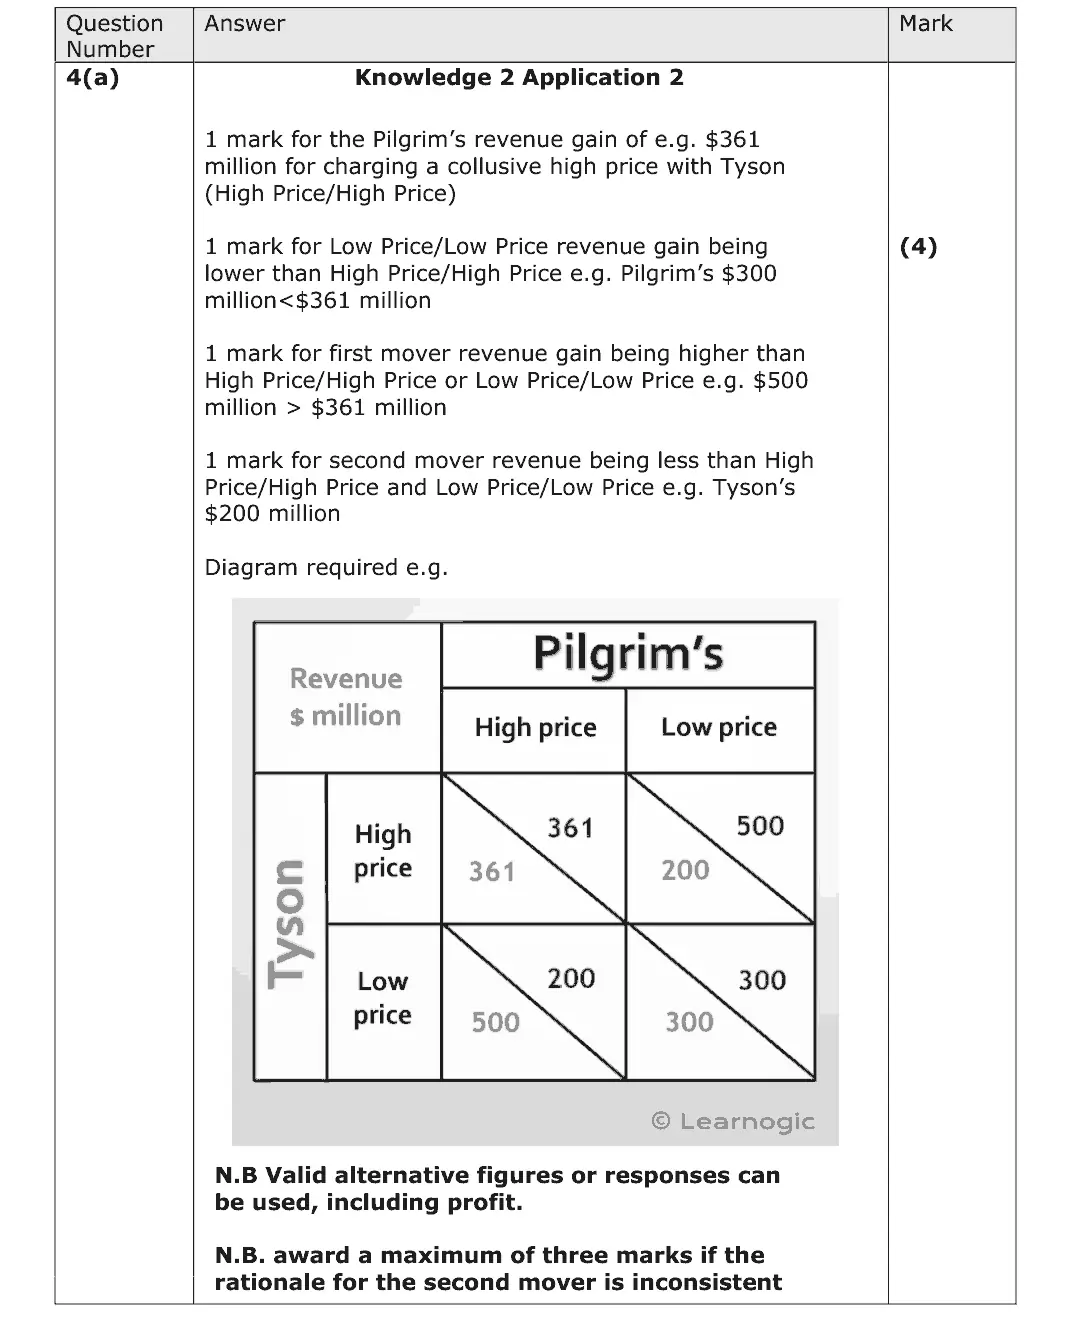
4(a) Oligopoly 4AO1=2,AO2=2Diagram
4(b) Oligopoly 1AO3=1Multiple choice
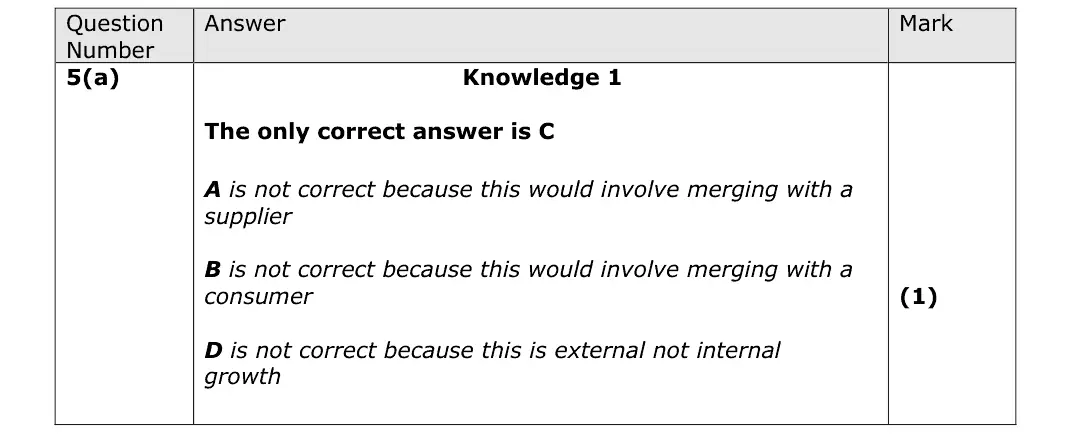
5(a) Business growth and business objectives 1AO1=1Multiple choice
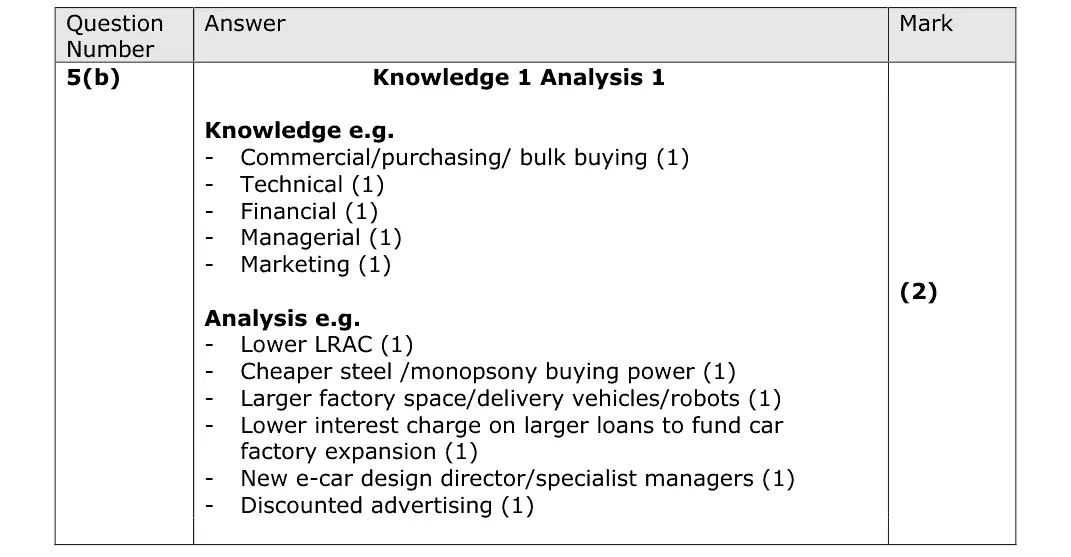
5(b) Revenues, costs and profits 2AO1=1,AO3=1Short answer
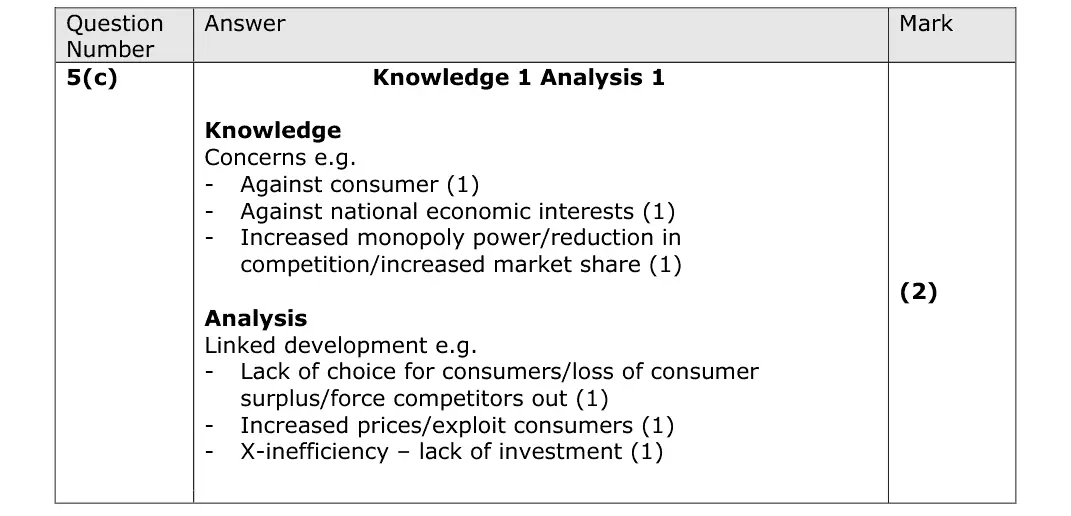
5(c) Government intervention: competition policy and regulation 2AO1=1,AO3=1Short answer
6(a) Oligopoly 5AO1=1,AO2=2,AO3=2Calculation
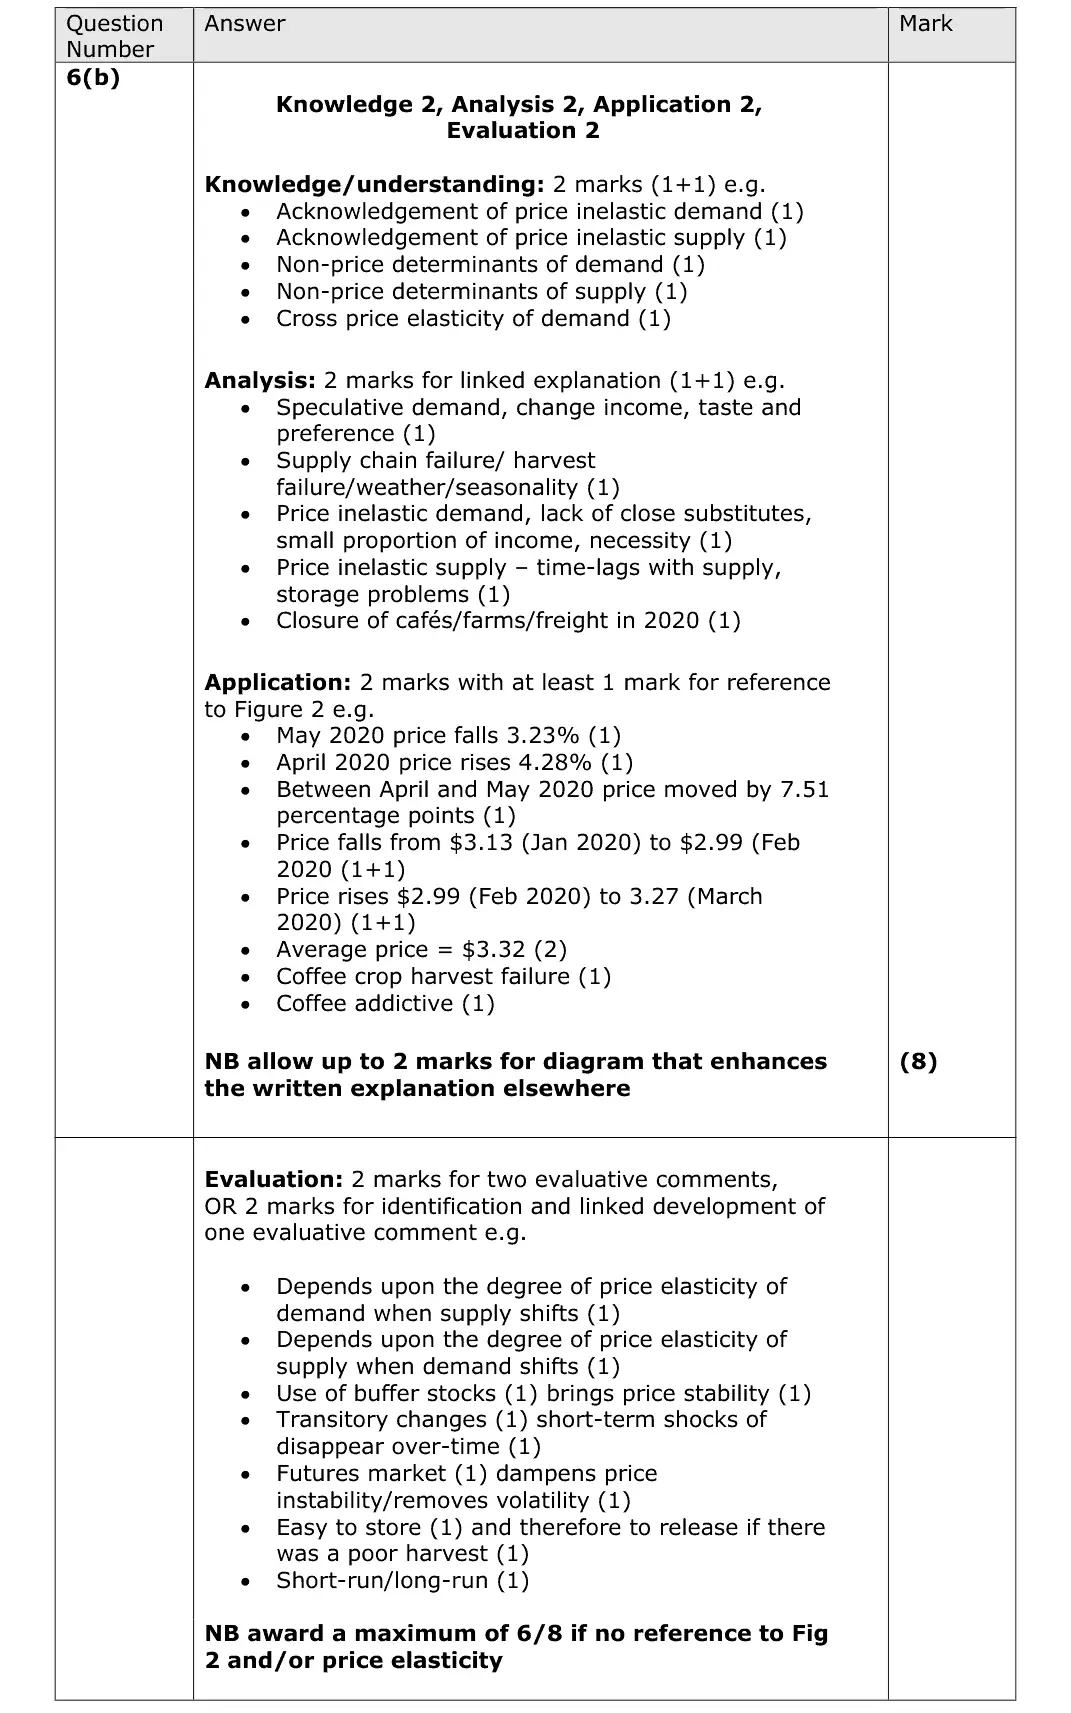
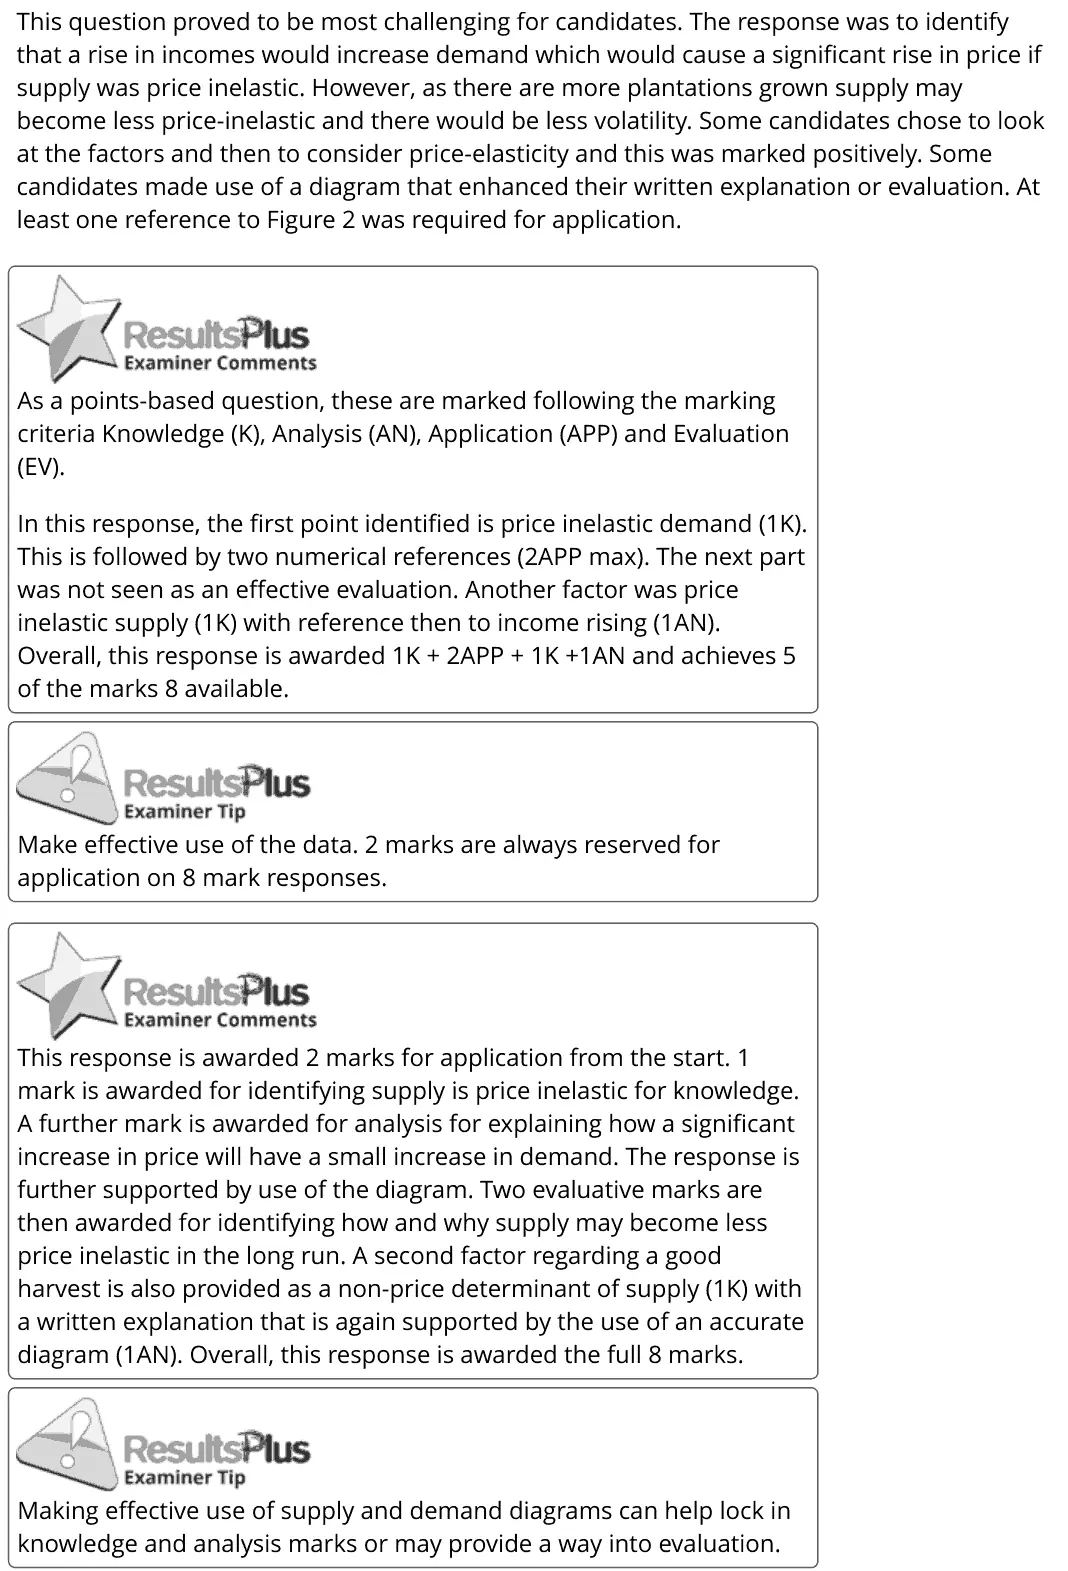
6(b) Price, income and cross elasticities of demand, Price elasticity of supply 8AO1=2,AO2=2,AO3=2,AO4=2Extended response
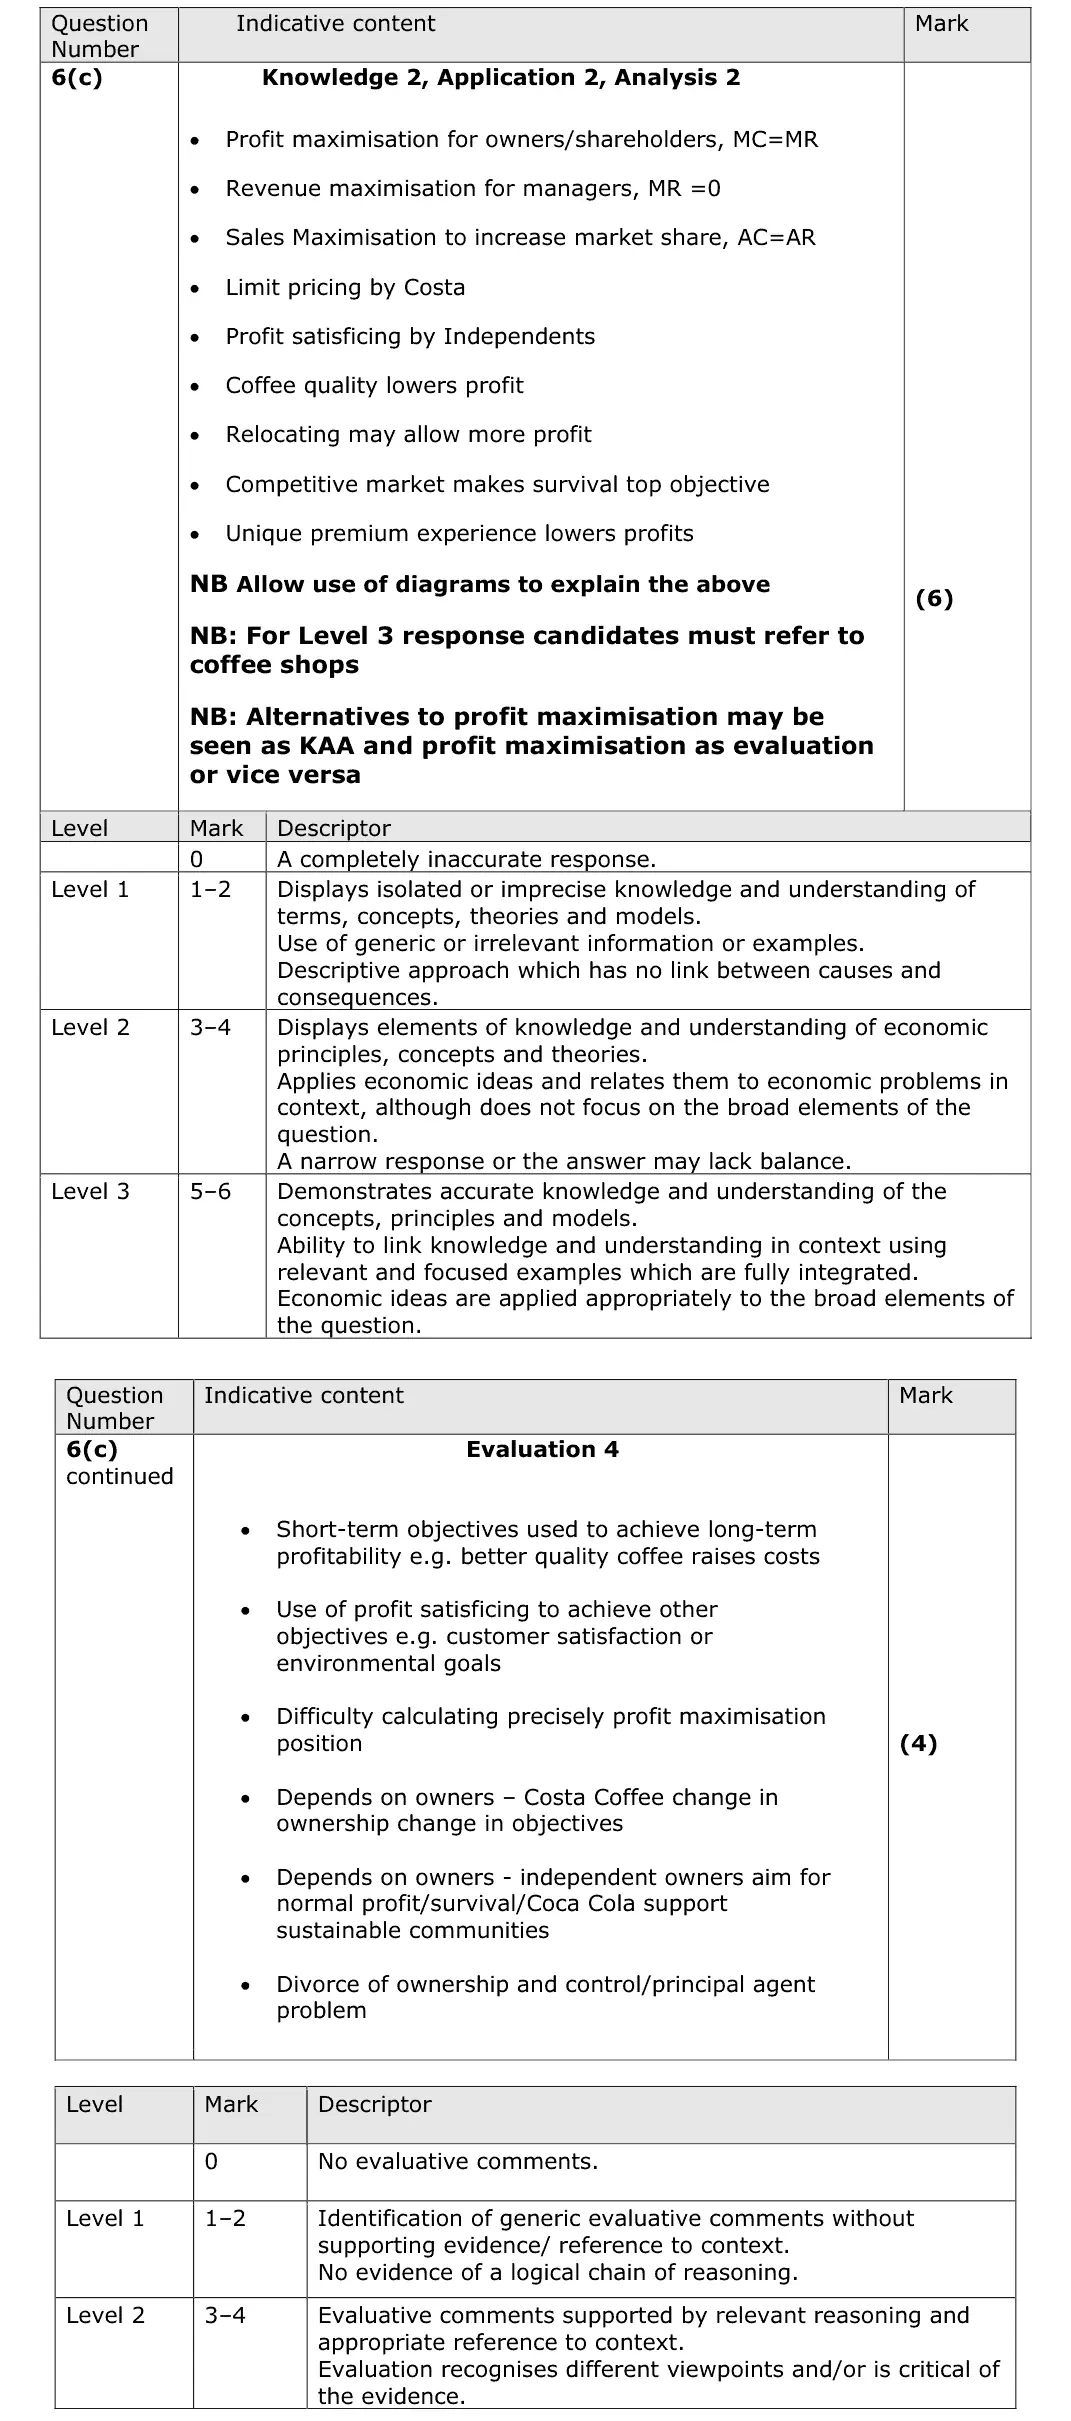
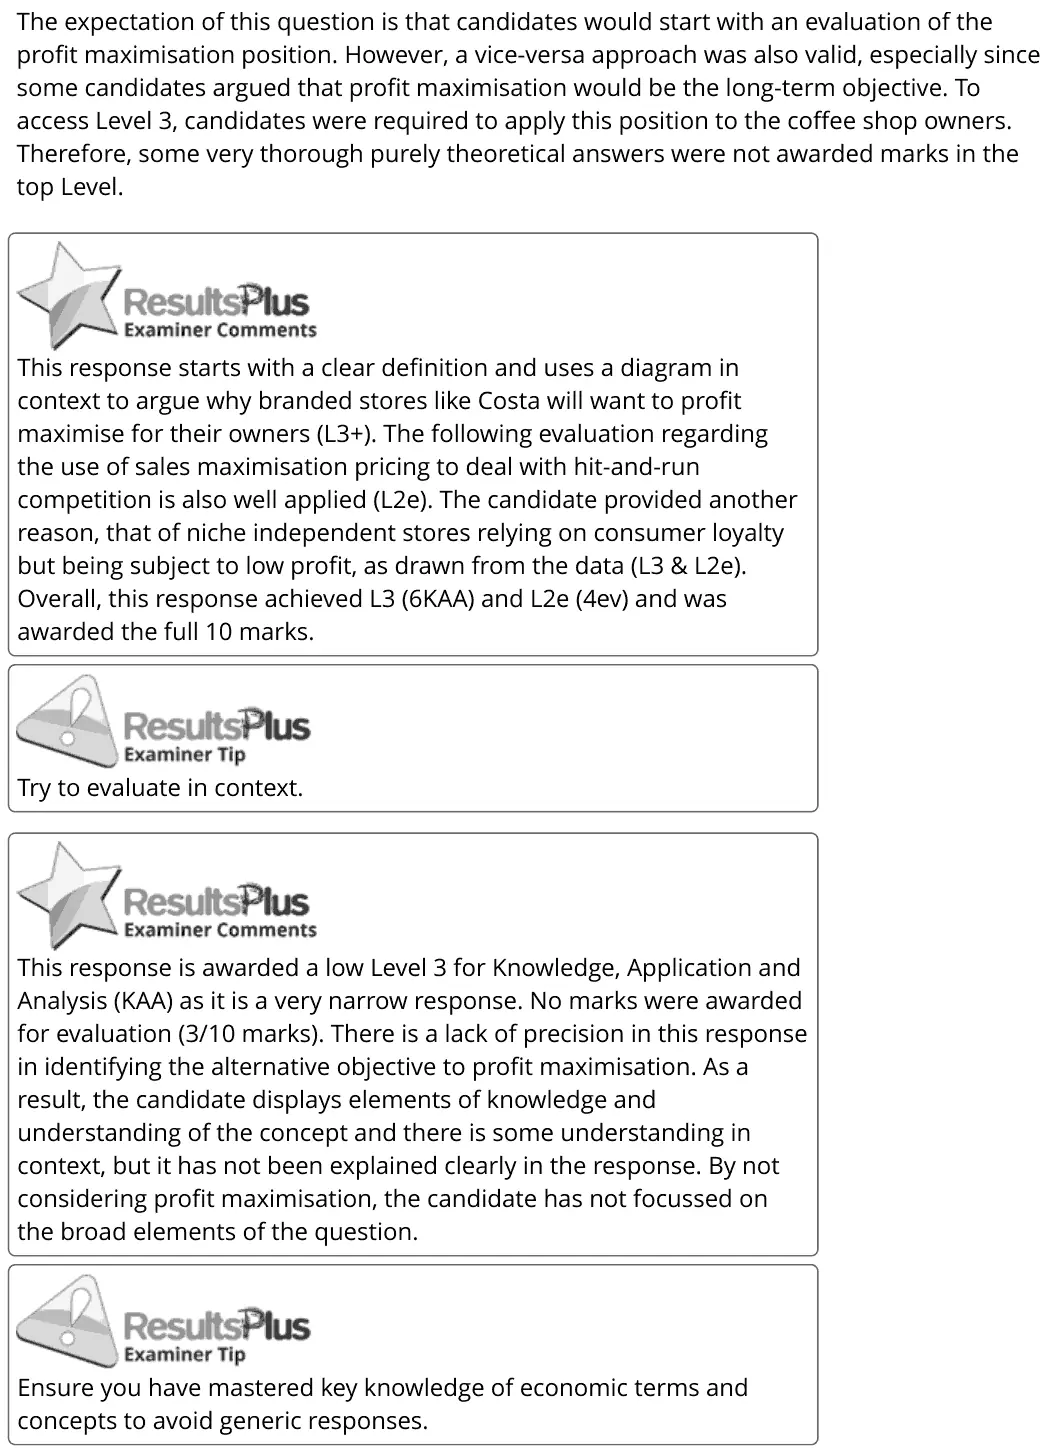
6(c) Business growth and business objectives 10AO1=2,AO2=2,AO3=2,AO4=4Extended response
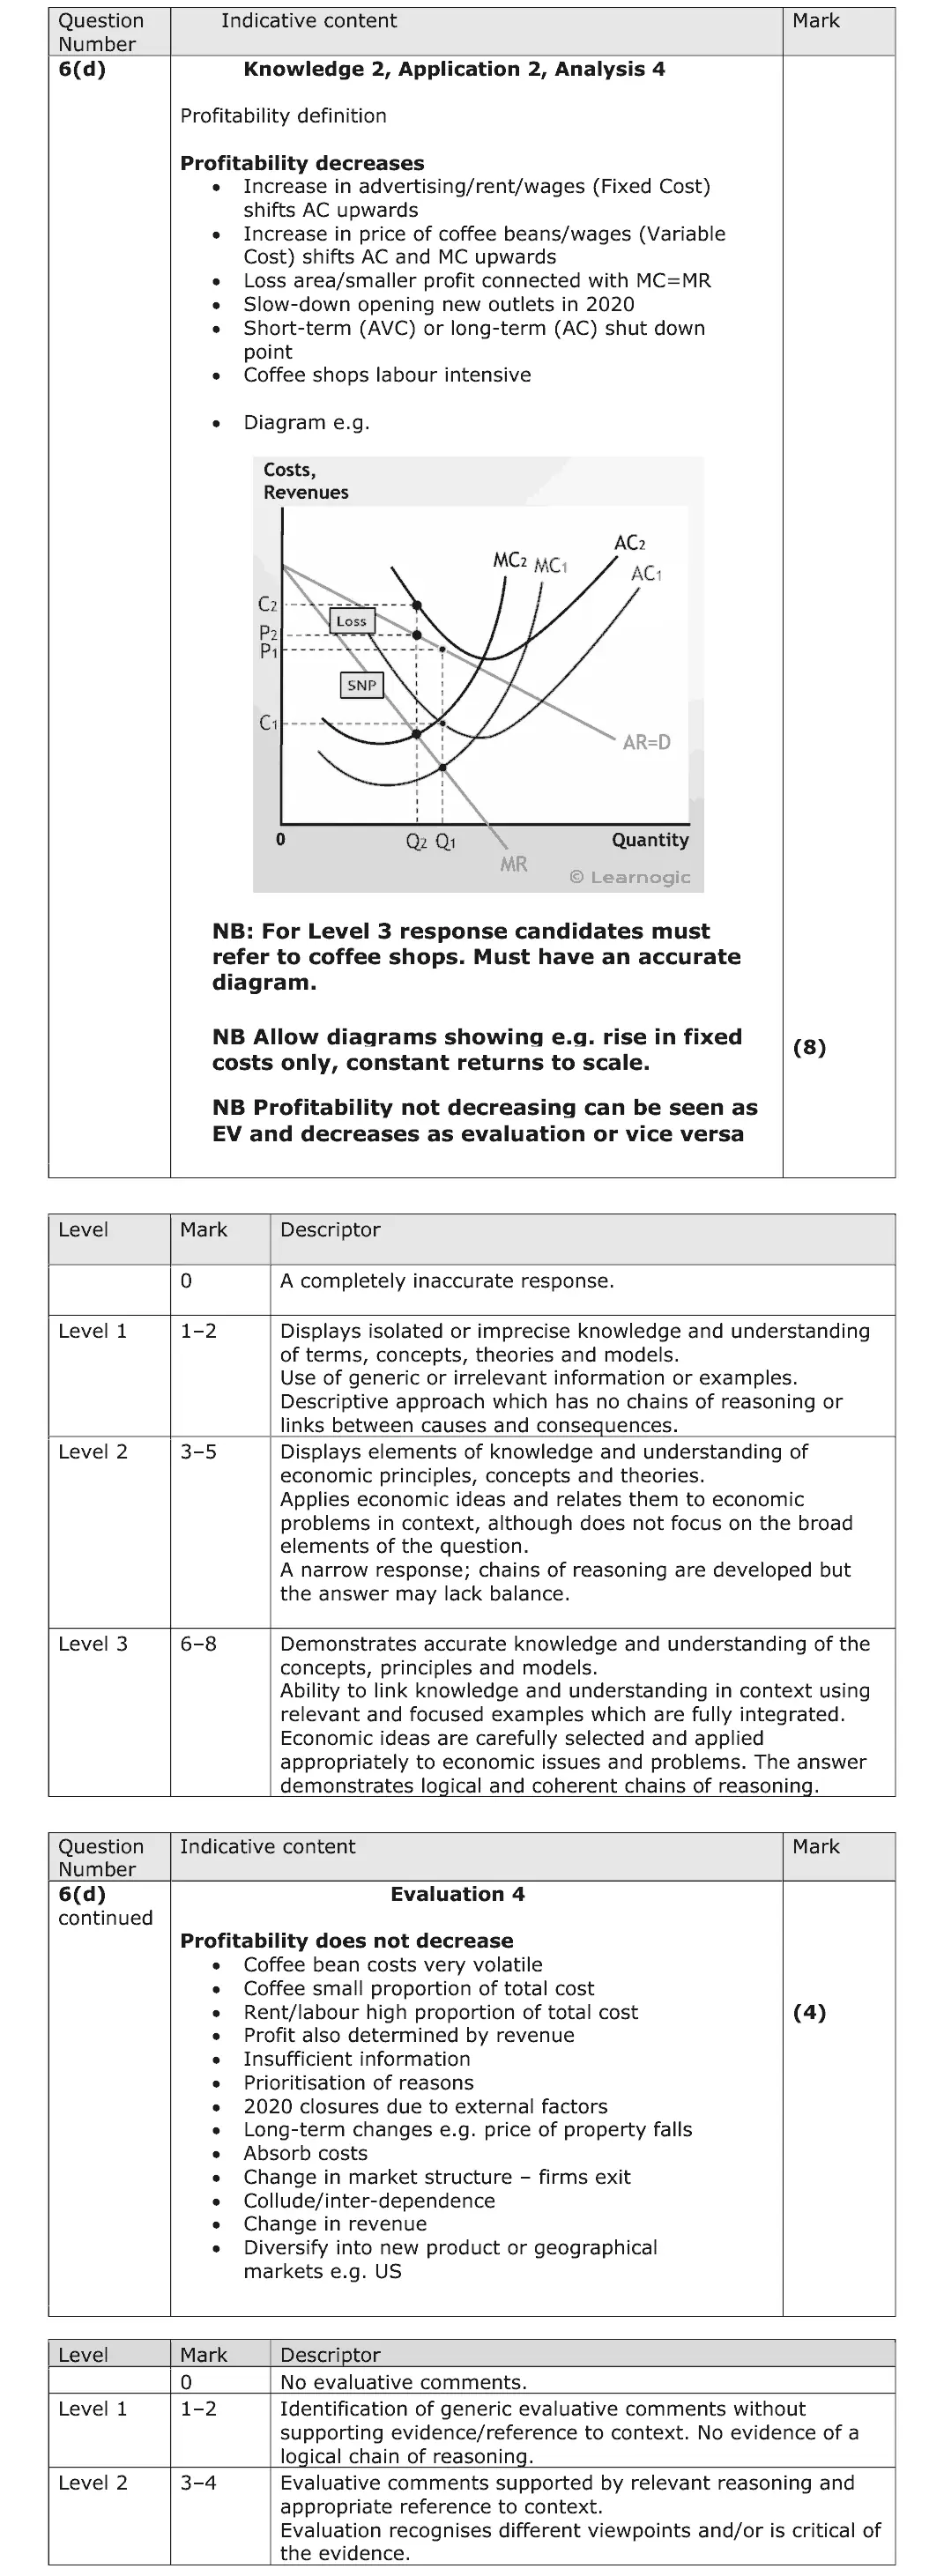
6(d) Revenues, costs and profits 12AO1=2,AO2=2,AO3=4,AO4=4Extended response
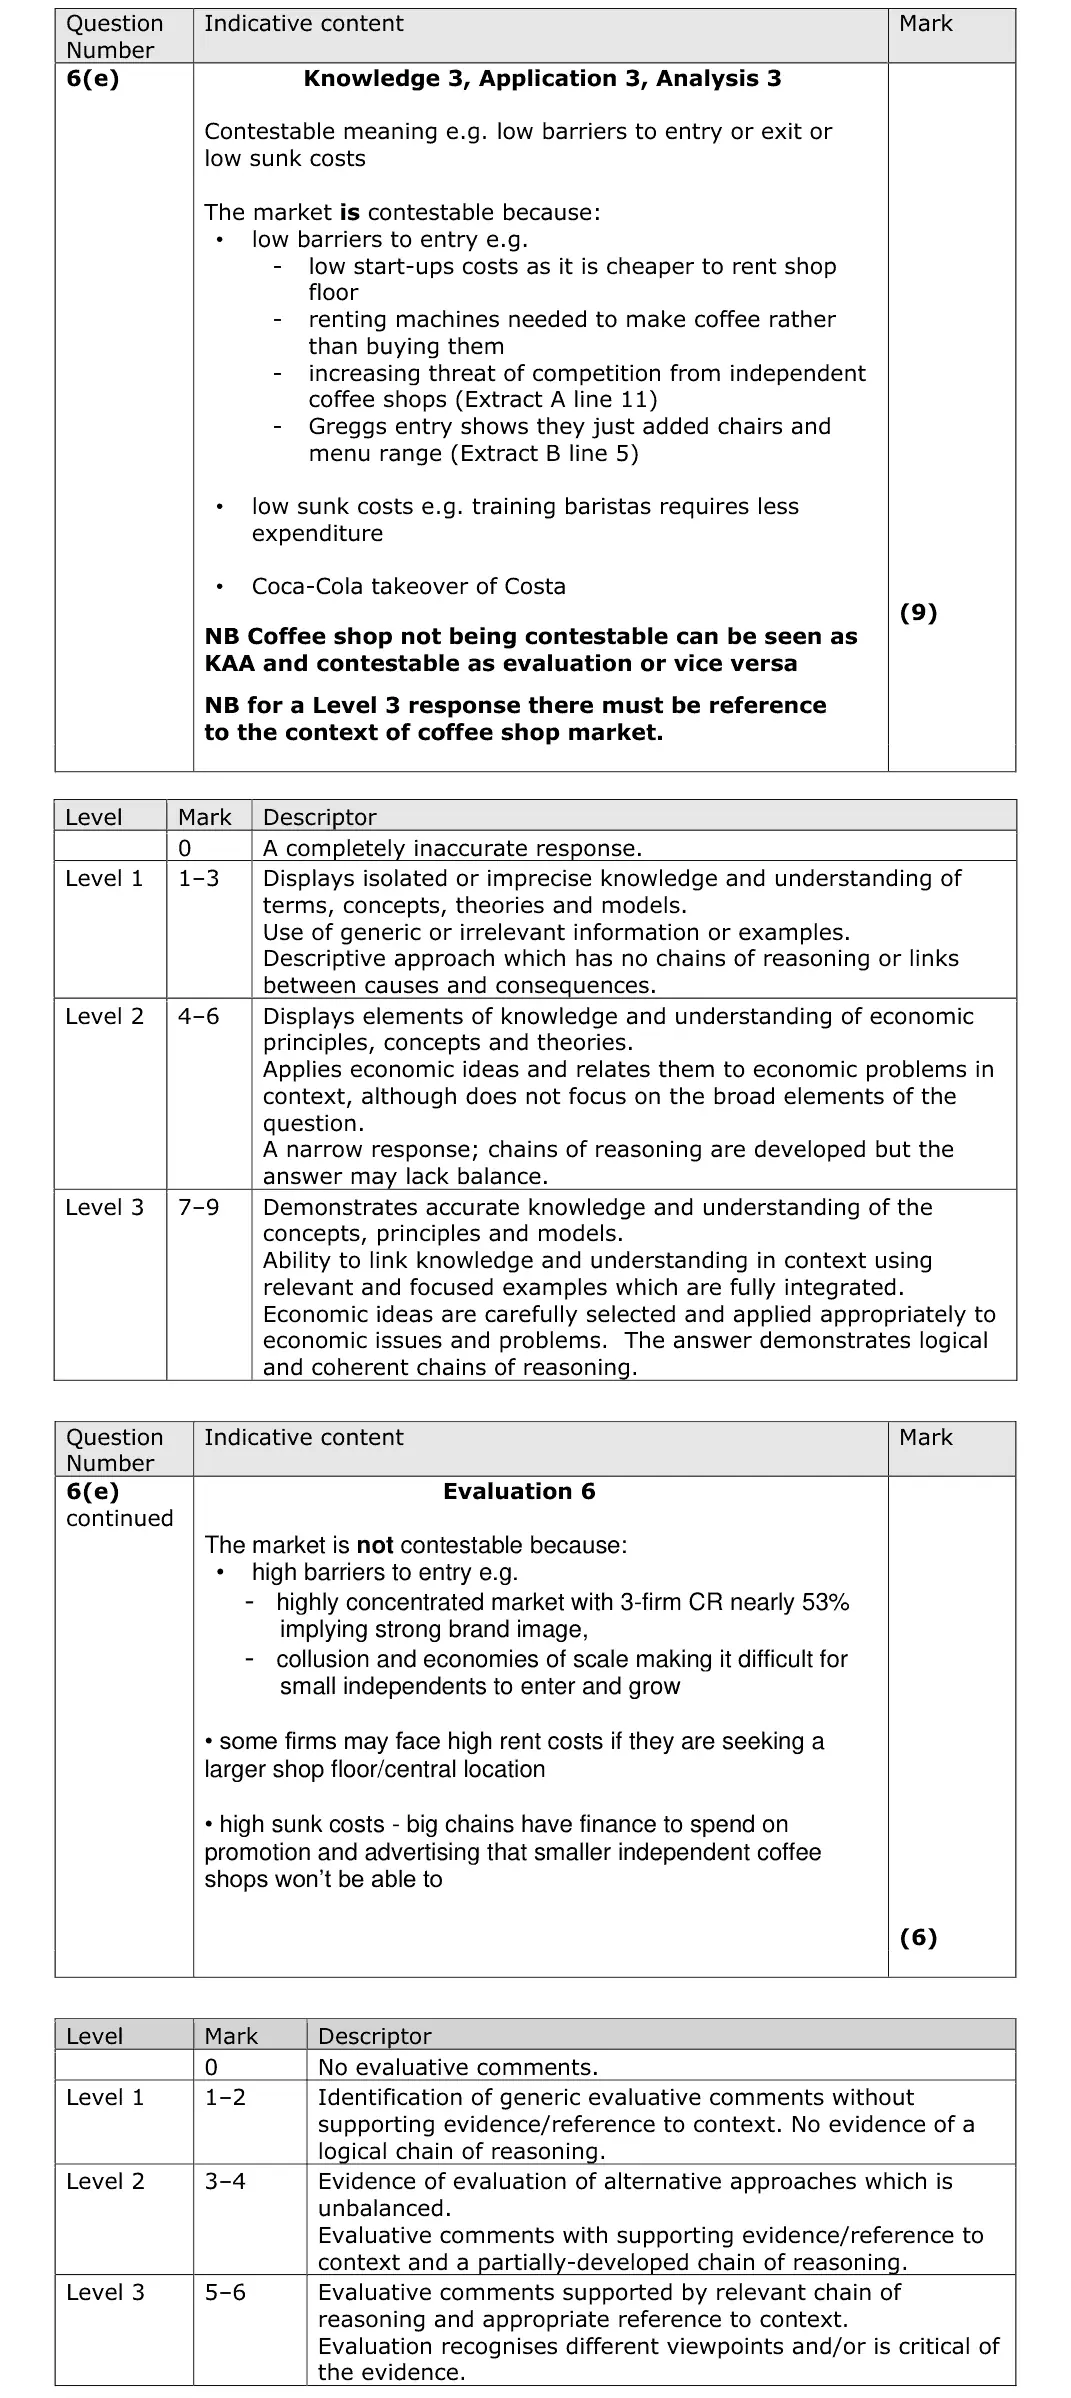
6(e) Monopsony and contestable markets 15AO1=3,AO2=3,AO3=3,AO4=6Extended response
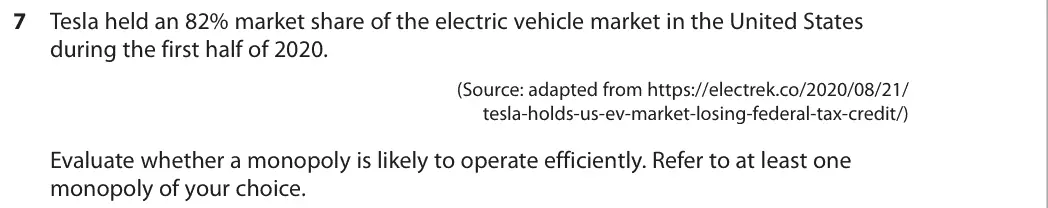
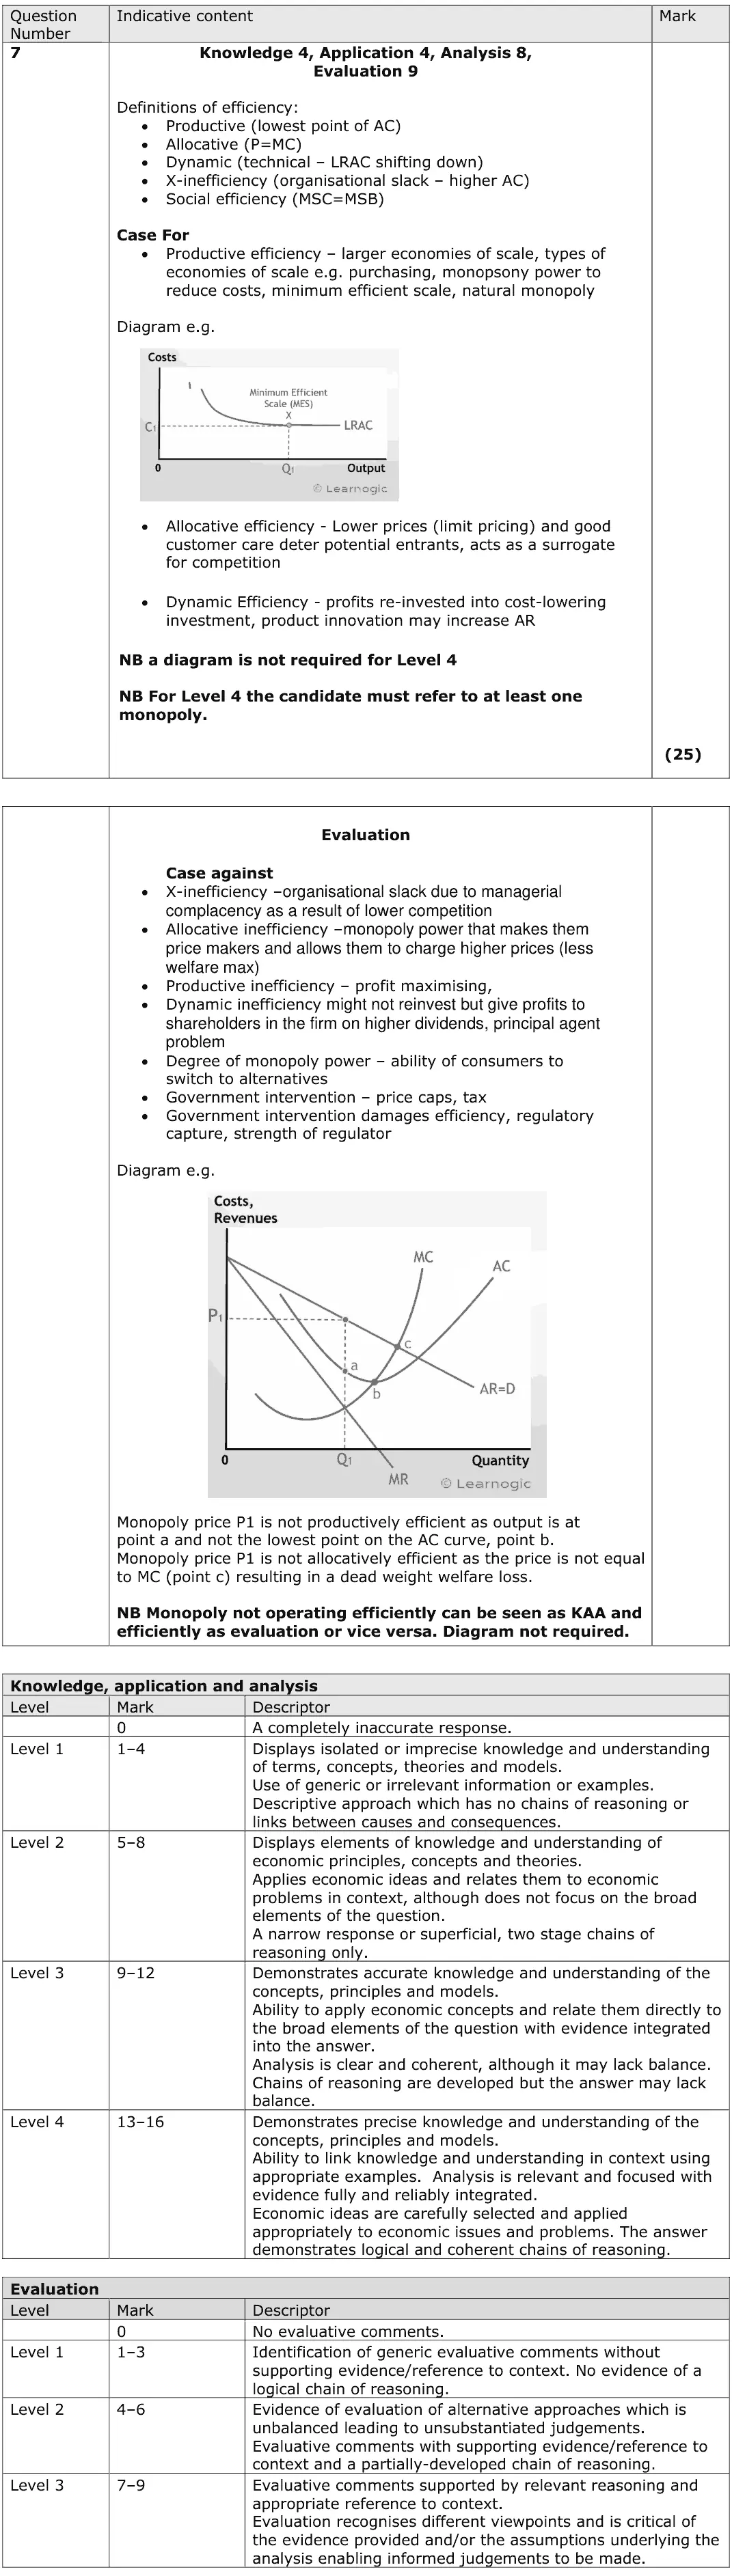
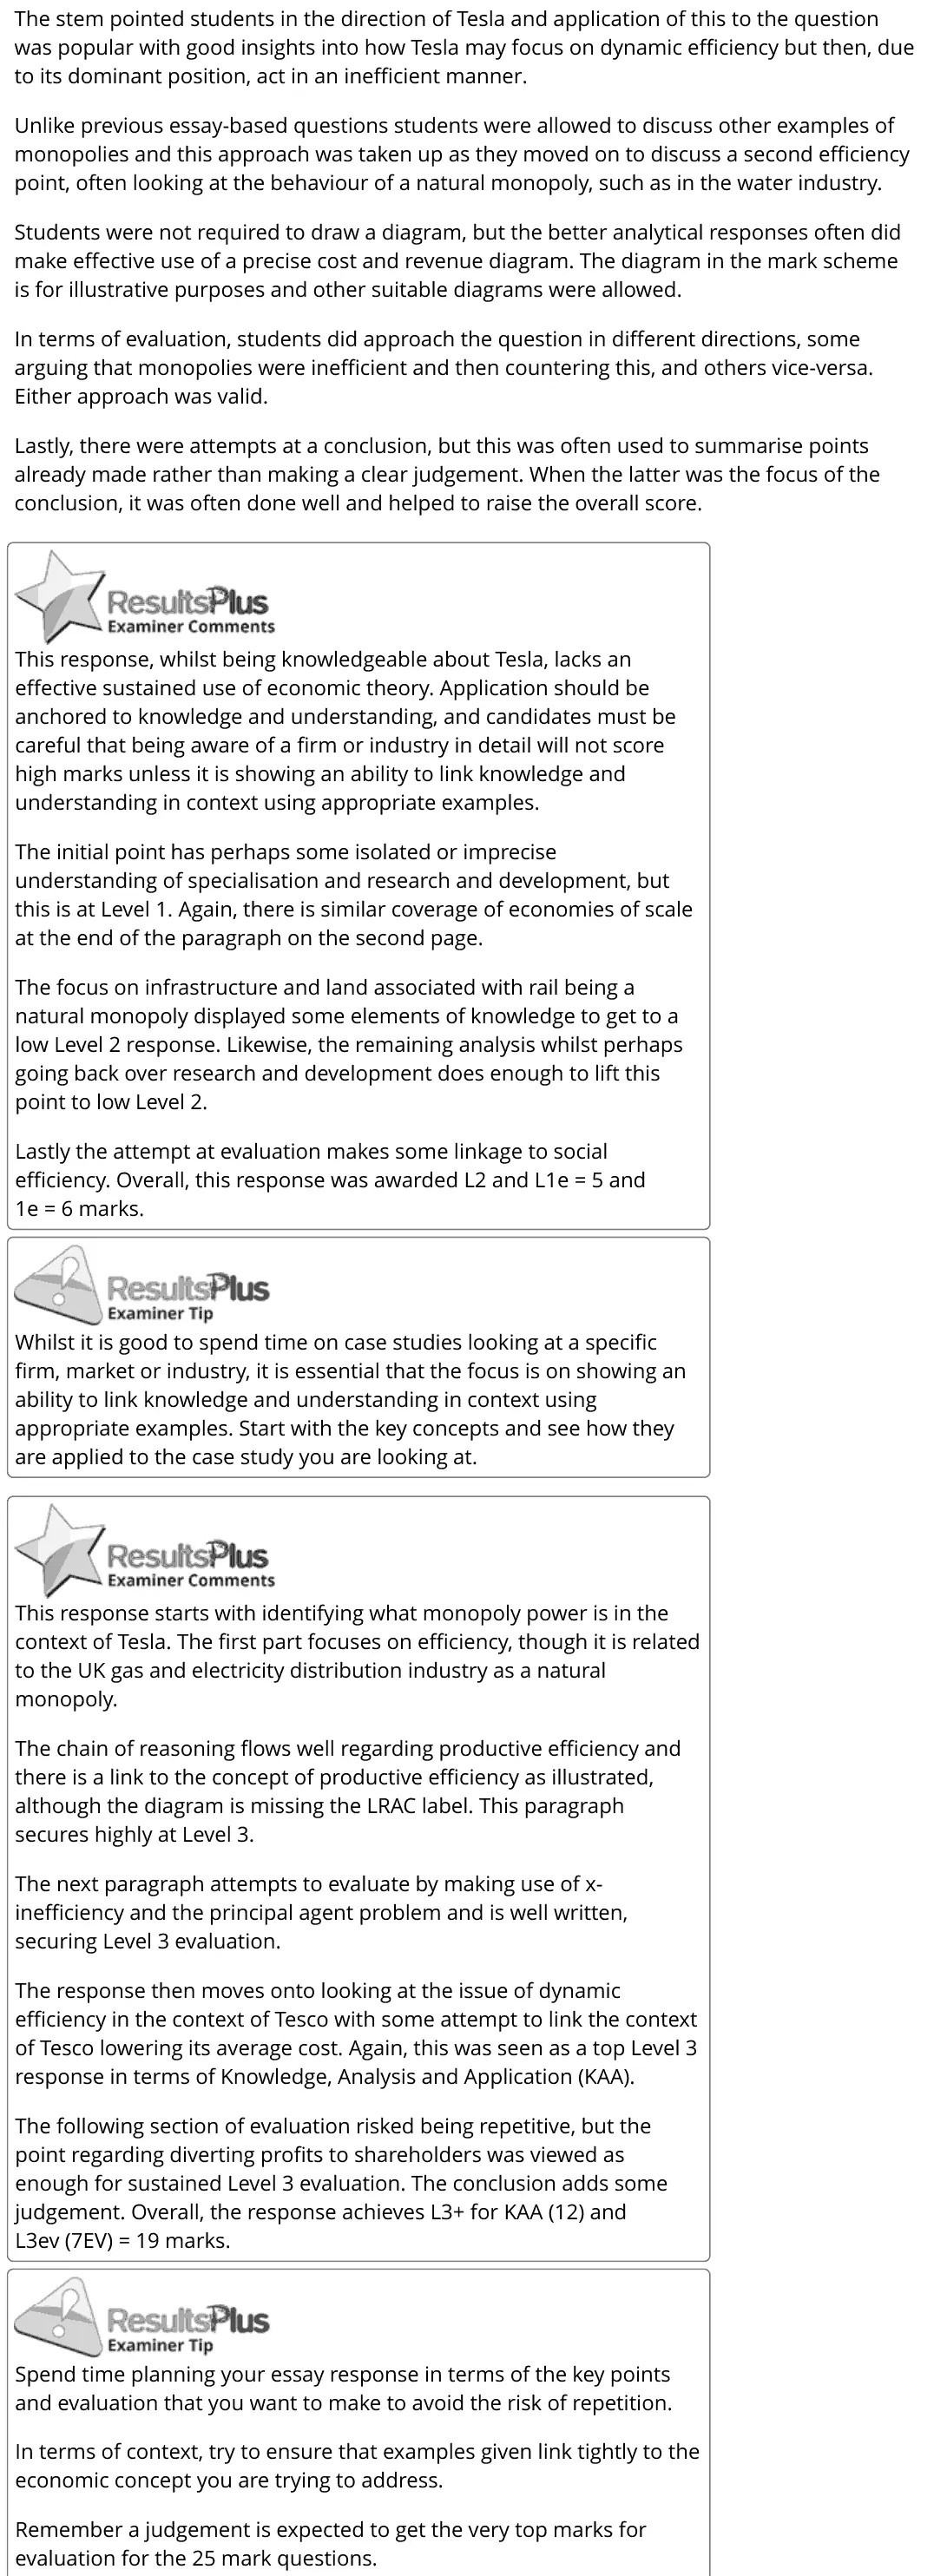
7 Monopoly, Market structures: efficiency, perfect and monopolistic competition 25AO1=4,AO2=4,AO3=8,AO4=9Essay
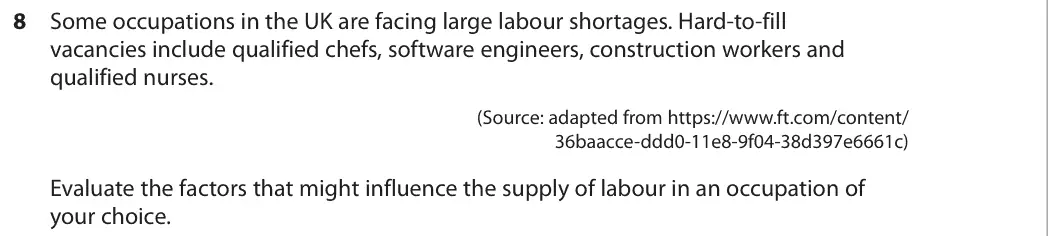
8 The labour market 25AO1=4,AO2=4,AO3=8,AO4=9Essay

The questions

1(a)1(b)2(a)2(b)2(c)3(a)3(b)4(a)4(b)5(a)5(b)5(c)6(a)6(b)6(c)6(d)6(e)78
June 2022 · Paper 1 · Q1(a) 1 mark AO3=1 Multiple choice supply and demand
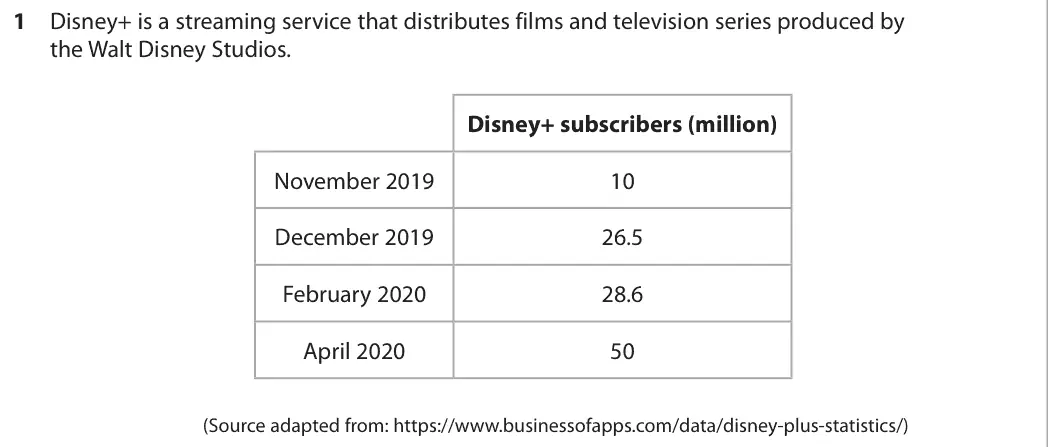
Data and extracts for question 11 Disney+ is a streaming service that distributes films and television series produced by the Walt Disney Studios. Disney+ subscribers (million) November 2019 10 December 2019 26.5 February 2020 28.6 April 2020 50 (Source adapted from: https://www.businessofapps.com/data/disney-plus-statistics/)
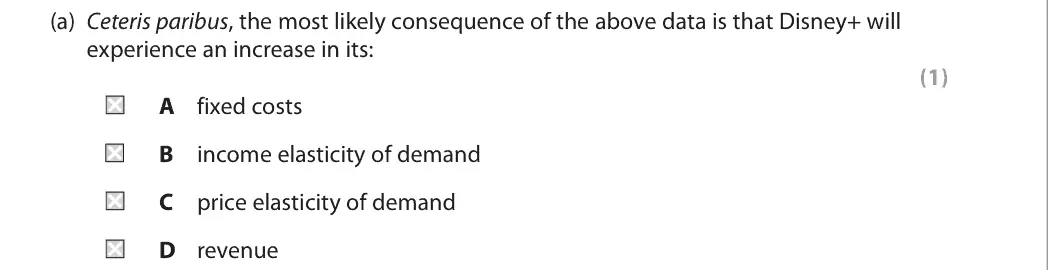
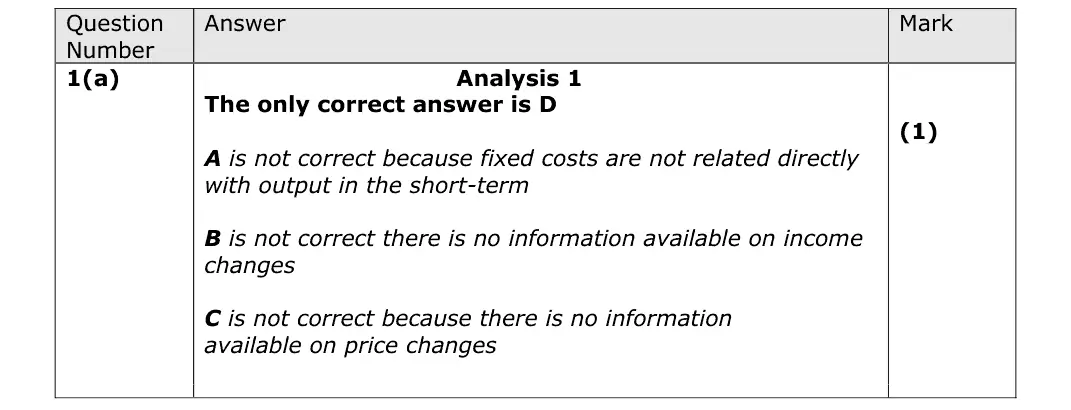
(a) Ceteris paribus, the most likely consequence of the above data is that Disney+ will experience an increase in its: (1) A fixed costs B income elasticity of demand C price elasticity of demand D revenue
June 2022 · Paper 1 · Q1(b) 4 marks AO1=2, AO2=2 Diagram supply and demand
Data and extracts for question 11 Disney+ is a streaming service that distributes films and television series produced by the Walt Disney Studios. Disney+ subscribers (million) November 2019 10 December 2019 26.5 February 2020 28.6 April 2020 50 (Source adapted from: https://www.businessofapps.com/data/disney-plus-statistics/)
(b) Draw a supply and demand diagram to show the likely effect of the change in the number of subscribers on the market equilibrium for Disney+ services. (4)
June 2022 · Paper 1 · Q2(a) 2 marks AO2=2 Calculation price elasticity of demand
Data and extracts for question 22 The table below shows data on the drinks market in Chile in 2017. Price elasticity of demand for sweetened drinks –1.37 Cross price elasticity of demand for bottled water +0.63 in response to a price change in sweetened drinks (Source: adapted from https://bmcpublichealth.biomedcentral.com/ articles/10.1186/s12889-017-4098-x)
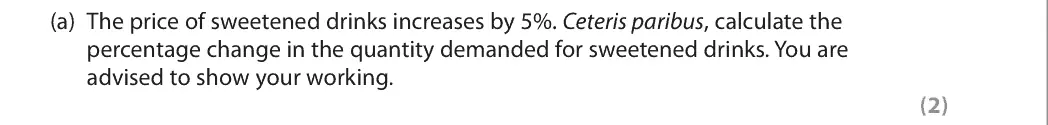
(a) The price of sweetened drinks increases by 5%. Ceteris paribus, calculate the percentage change in the quantity demanded for sweetened drinks. You are advised to show your working. (2)
June 2022 · Paper 1 · Q2(b) 2 marks AO2=2 Calculation price elasticity of demand
Data and extracts for question 22 The table below shows data on the drinks market in Chile in 2017. Price elasticity of demand for sweetened drinks –1.37 Cross price elasticity of demand for bottled water +0.63 in response to a price change in sweetened drinks (Source: adapted from https://bmcpublichealth.biomedcentral.com/ articles/10.1186/s12889-017-4098-x)
(b) The price of sweetened drinks increases by 5%. Ceteris paribus, calculate the percentage change in the quantity demanded for bottled water. You are advised to show your working. (2)
June 2022 · Paper 1 · Q2(c) 1 mark AO1=1 Multiple choice price elasticity of demand
Data and extracts for question 22 The table below shows data on the drinks market in Chile in 2017. Price elasticity of demand for sweetened drinks –1.37 Cross price elasticity of demand for bottled water +0.63 in response to a price change in sweetened drinks (Source: adapted from https://bmcpublichealth.biomedcentral.com/ articles/10.1186/s12889-017-4098-x)
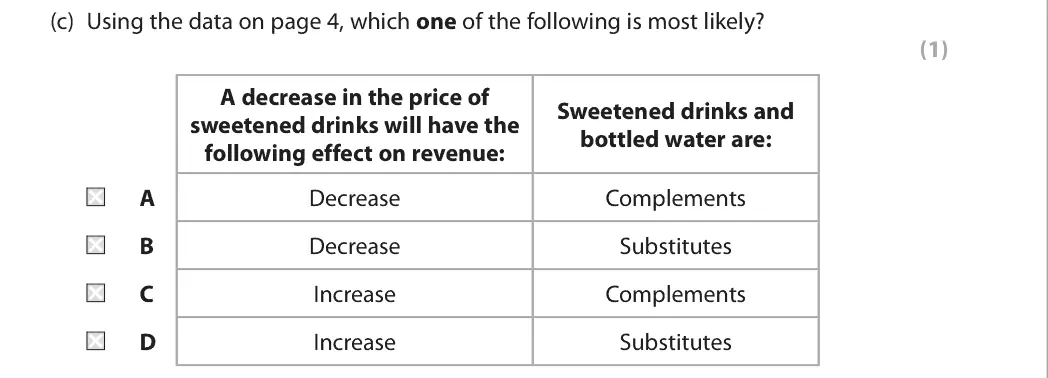
(c) Using the data on page 4, which one of the following is most likely? (1) A decrease in the price of Sweetened drinks and sweetened drinks will have the bottled water are: following effect on revenue: A Decrease Complements B Decrease Substitutes C Increase Complements D Increase Substitutes
June 2022 · Paper 1 · Q3(a) 4 marks AO1=2, AO2=2 Diagram externalities
Data and extracts for question 33 A company that provides drinking water and treats waste water has been fined £180 000 after an incident that killed about 2 500 fish. The charges relate to an illegal discharge of sewage from the waste water treatment plant that polluted nine kilometres of the River Severn, a popular tourist destination. (Source: adapted from https://www.leaderlive.co.uk/news/wrexham/ 19393552.water-company-fined-today-sewage-leaked-wrexham-river-killing-2-500-fish/)
(a) Draw an externalities diagram to show the likely impact of the sewage discharge on the local tourist industry. (4)
June 2022 · Paper 1 · Q3(b) 1 mark AO3=1 Multiple choice government intervention in markets
Data and extracts for question 33 A company that provides drinking water and treats waste water has been fined £180 000 after an incident that killed about 2 500 fish. The charges relate to an illegal discharge of sewage from the waste water treatment plant that polluted nine kilometres of the River Severn, a popular tourist destination. (Source: adapted from https://www.leaderlive.co.uk/news/wrexham/ 19393552.water-company-fined-today-sewage-leaked-wrexham-river-killing-2-500-fish/)
(b) Which one of the following is the most likely effect of the £180 000 fine? (1) To: A increase market failure B increase profits for the water company C reduce external costs D reduce government failure
June 2022 · Paper 1 · Q4(a) 4 marks AO1=2, AO2=2 Diagram oligopoly
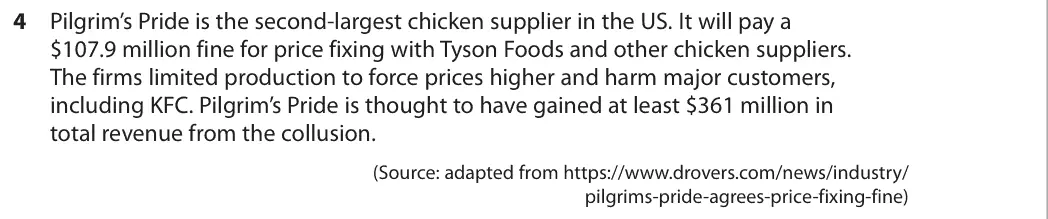
Data and extracts for question 44 Pilgrim’s Pride is the second-largest chicken supplier in the US. It will pay a $107.9 million fine for price fixing with Tyson Foods and other chicken suppliers. The firms limited production to force prices higher and harm major customers, including KFC. Pilgrim’s Pride is thought to have gained at least $361 million in total revenue from the collusion. (Source: adapted from https://www.drovers.com/news/industry/ pilgrims-pride-agrees-price-fixing-fine)
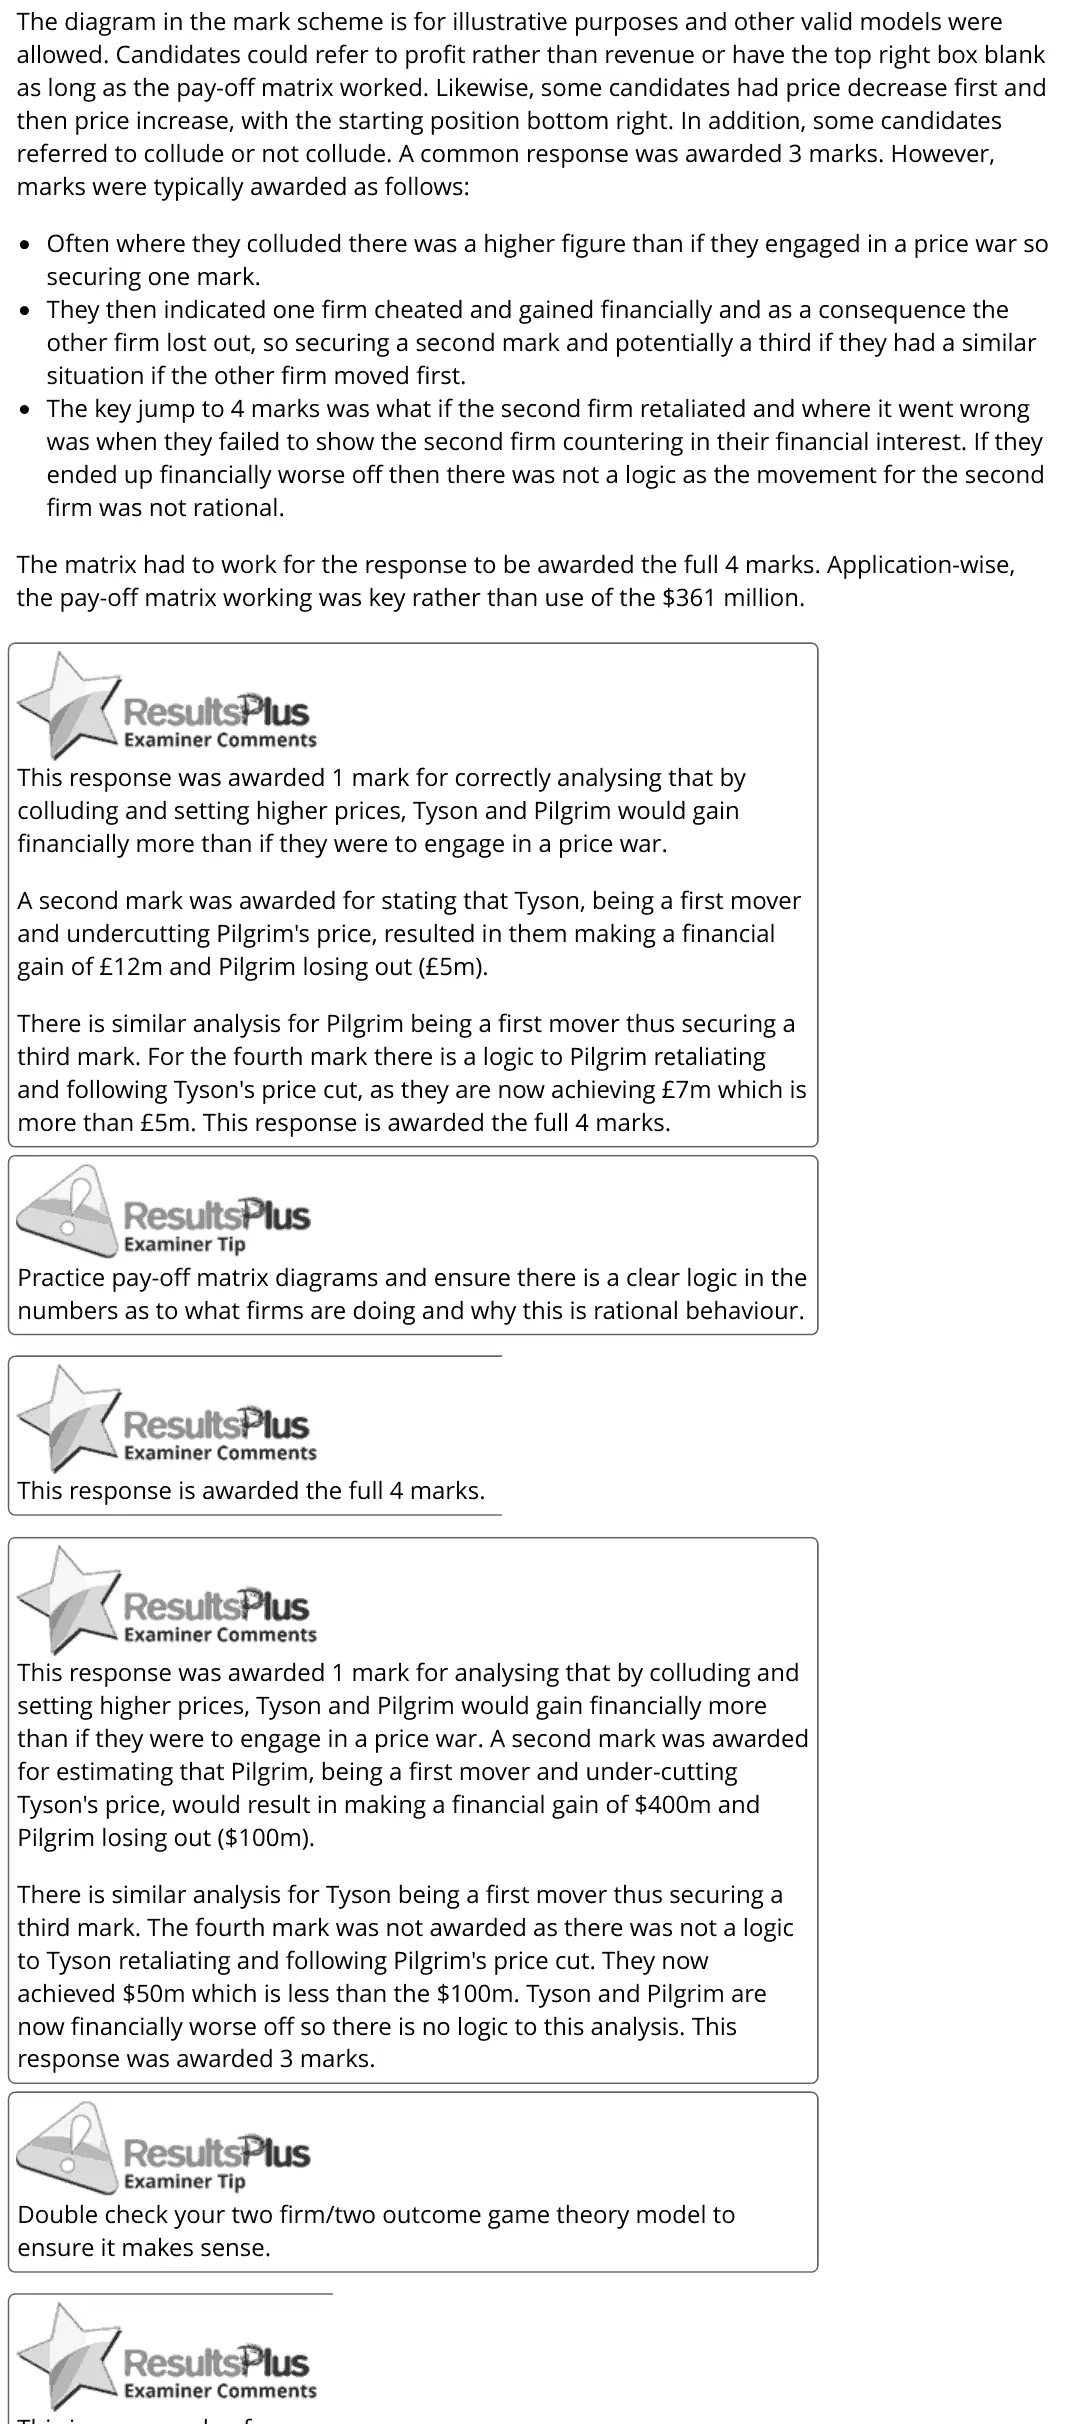
(a) Draw a simple two firm/two outcome game theory model to show why the chicken suppliers may have colluded. (4)
June 2022 · Paper 1 · Q4(b) 1 mark AO3=1 Multiple choice oligopoly
Data and extracts for question 44 Pilgrim’s Pride is the second-largest chicken supplier in the US. It will pay a $107.9 million fine for price fixing with Tyson Foods and other chicken suppliers. The firms limited production to force prices higher and harm major customers, including KFC. Pilgrim’s Pride is thought to have gained at least $361 million in total revenue from the collusion. (Source: adapted from https://www.drovers.com/news/industry/ pilgrims-pride-agrees-price-fixing-fine)
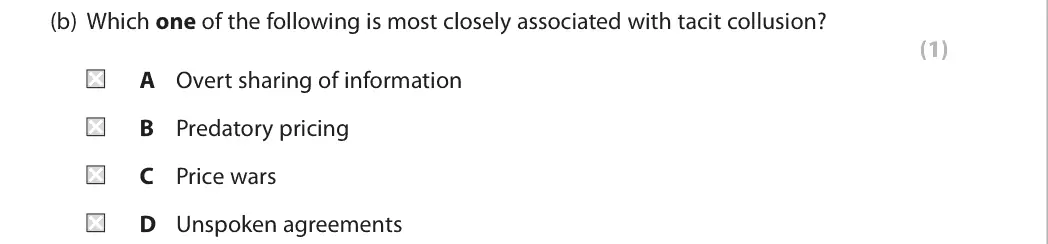
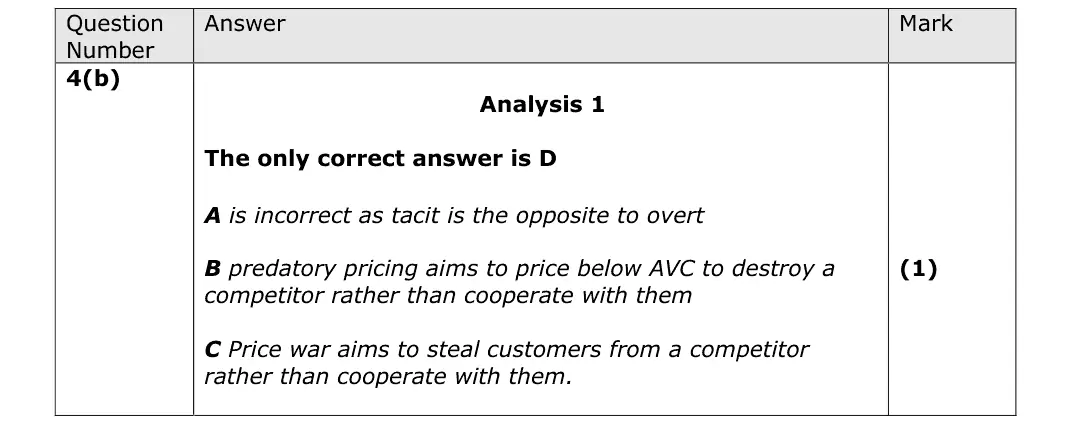
(b) Which one of the following is most closely associated with tacit collusion? (1) A Overt sharing of information B Predatory pricing C Price wars D Unspoken agreements
June 2022 · Paper 1 · Q5(a) 1 mark AO1=1 Multiple choice business growth and objectives
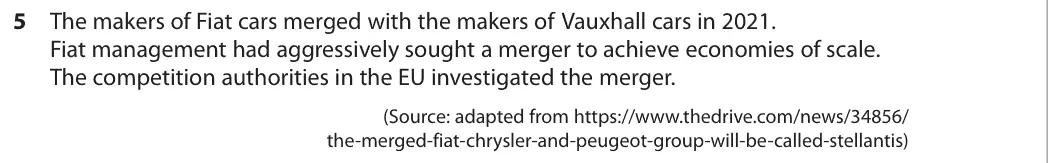
Data and extracts for question 55 The makers of Fiat cars merged with the makers of Vauxhall cars in 2021. Fiat management had aggressively sought a merger to achieve economies of scale. The competition authorities in the EU investigated the merger. (Source: adapted from https://www.thedrive.com/news/34856/ the-merged-fiat-chrysler-and-peugeot-group-will-be-called-stellantis)
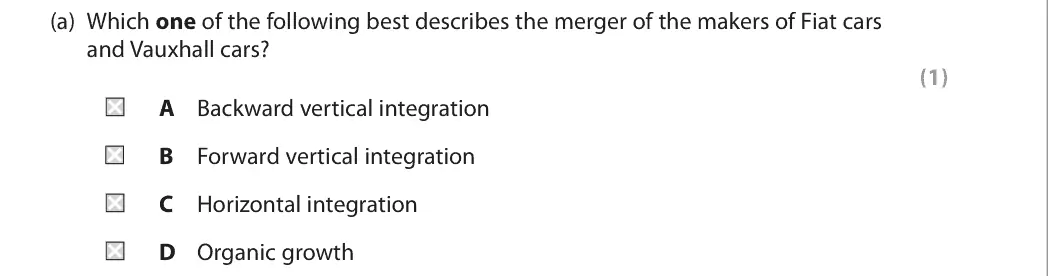
(a) Which one of the following best describes the merger of the makers of Fiat cars and Vauxhall cars? (1) A Backward vertical integration B Forward vertical integration C Horizontal integration D Organic growth
June 2022 · Paper 1 · Q5(b) 2 marks AO1=1, AO3=1 Short answer revenues costs and profits
Data and extracts for question 55 The makers of Fiat cars merged with the makers of Vauxhall cars in 2021. Fiat management had aggressively sought a merger to achieve economies of scale. The competition authorities in the EU investigated the merger. (Source: adapted from https://www.thedrive.com/news/34856/ the-merged-fiat-chrysler-and-peugeot-group-will-be-called-stellantis)
(b) Explain one type of internal economies of scale that the newly merged car company may achieve. (2)
June 2022 · Paper 1 · Q5(c) 2 marks AO1=1, AO3=1 Short answer competition policy and regulation
Data and extracts for question 55 The makers of Fiat cars merged with the makers of Vauxhall cars in 2021. Fiat management had aggressively sought a merger to achieve economies of scale. The competition authorities in the EU investigated the merger. (Source: adapted from https://www.thedrive.com/news/34856/ the-merged-fiat-chrysler-and-peugeot-group-will-be-called-stellantis)
(c) Explain one likely concern the EU competition authorities may have had about the merger. (2)
June 2022 · Paper 1 · Q6(a) 5 marks AO1=1, AO2=2, AO3=2 Calculation oligopoly
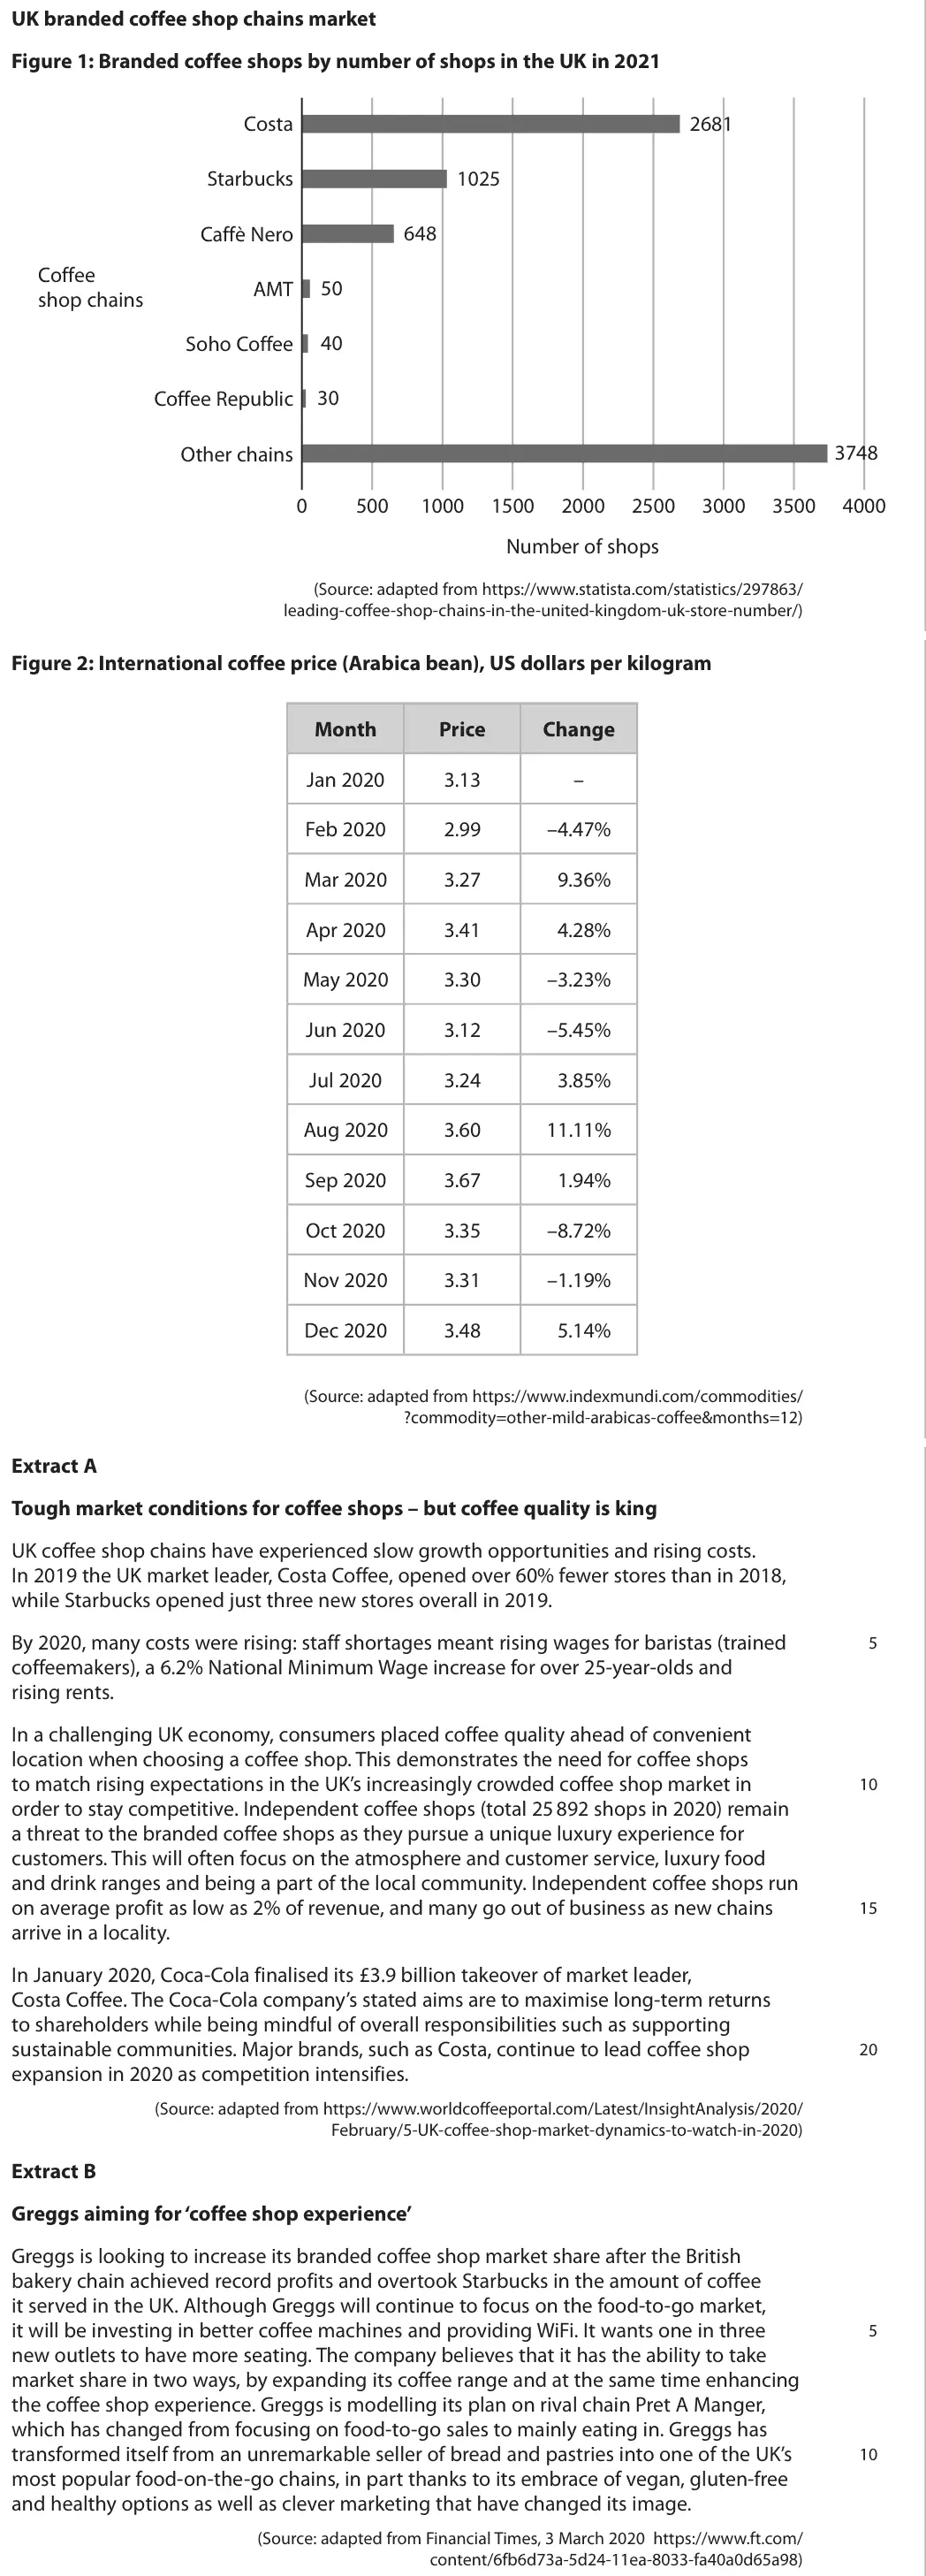
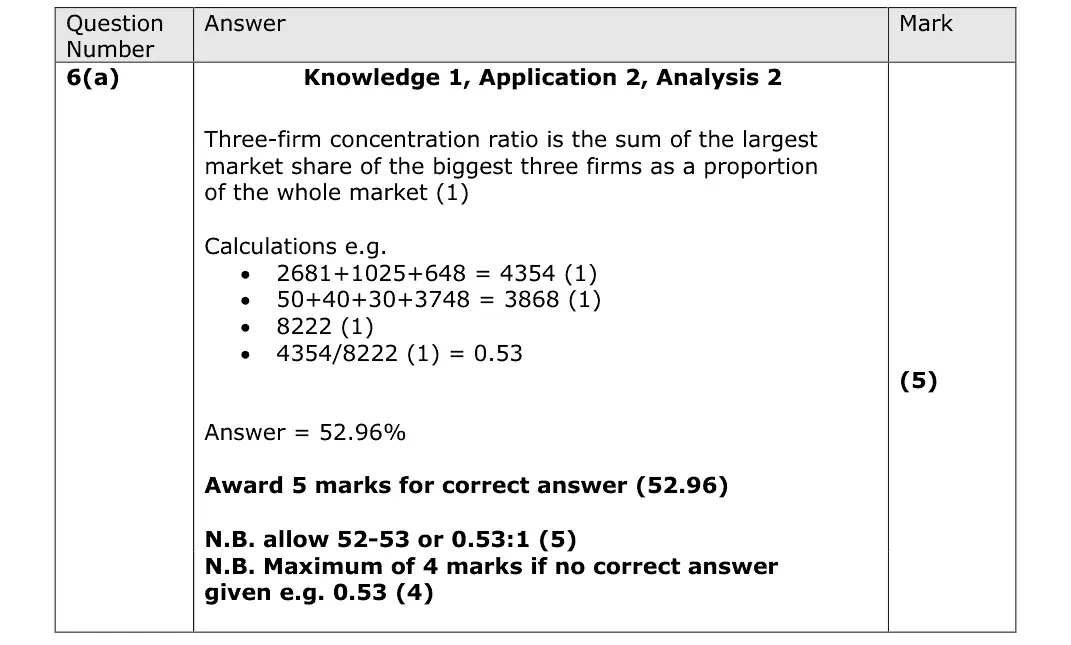
Data and extracts for question 6UK branded coffee shop chains market Figure 1: Branded coffee shops by number of shops in the UK in 2021 Costa 2681 Starbucks 1025 Caffè Nero 648 Coffee 50 AMT shop chains 40 Soho Coffee 30 Coffee Republic 3748 Other chains 0 500 1000 1500 2000 2500 3000 3500 4000 Number of shops (Source: adapted from https://www.statista.com/statistics/297863/ leading-coffee-shop-chains-in-the-united-kingdom-uk-store-number/) Figure 2: International coffee price (Arabica bean), US dollars per kilogram Month Price Change Jan 2020 3.13 – Feb 2020 2.99 –4.47% Mar 2020 3.27 9.36% Apr 2020 3.41 4.28% May 2020 3.30 –3.23% Jun 2020 3.12 –5.45% Jul 2020 3.24 3.85% Aug 2020 3.60 11.11% Sep 2020 3.67 1.94% Oct 2020 3.35 –8.72% Nov 2020 3.31 –1.19% Dec 2020 3.48 5.14% (Source: adapted from https://www.indexmundi.com/commodities/ ?commodity=other-mild-arabicas-coffee&months=12) Extract A Tough market conditions for coffee shops – but coffee quality is king UK coffee shop chains have experienced slow growth opportunities and rising costs. In 2019 the UK market leader, Costa Coffee, opened over 60% fewer stores than in 2018, while Starbucks opened just three new stores overall in 2019. By 2020, many costs were rising: staff shortages meant rising wages for baristas (trained 5 coffeemakers), a 6.2% National Minimum Wage increase for over 25-year-olds and rising rents. In a challenging UK economy, consumers placed coffee quality ahead of convenient location when choosing a coffee shop. This demonstrates the need for coffee shops to match rising expectations in the UK’s increasingly crowded coffee shop market in 10 order to stay competitive. Independent coffee shops (total 25 892 shops in 2020) remain a threat to the branded coffee shops as they pursue a unique luxury experience for customers. This will often focus on the atmosphere and customer service, luxury food and drink ranges and being a part of the local community. Independent coffee shops run on average profit as low as 2% of revenue, and many go out of business as new chains 15 arrive in a locality. In January 2020, Coca-Cola finalised its £3.9 billion takeover of market leader, Costa Coffee. The Coca-Cola company’s stated aims are to maximise long-term returns to shareholders while being mindful of overall responsibilities such as supporting sustainable communities. Major brands, such as Costa, continue to lead coffee shop 20 expansion in 2020 as competition intensifies. (Source: adapted from https://www.worldcoffeeportal.com/Latest/InsightAnalysis/2020/ February/5-UK-coffee-shop-market-dynamics-to-watch-in-2020) Extract B Greggs aiming for ‘coffee shop experience’ Greggs is looking to increase its branded coffee shop market share after the British bakery chain achieved record profits and overtook Starbucks in the amount of coffee it served in the UK. Although Greggs will continue to focus on the food-to-go market, it will be investing in better coffee machines and providing WiFi. It wants one in three 5 new outlets to have more seating. The company believes that it has the ability to take market share in two ways, by expanding its coffee range and at the same time enhancing the coffee shop experience. Greggs is modelling its plan on rival chain Pret A Manger, which has changed from focusing on food-to-go sales to mainly eating in. Greggs has transformed itself from an unremarkable seller of bread and pastries into one of the UK’s 10 most popular food-on-the-go chains, in part thanks to its embrace of vegan, gluten-free and healthy options as well as clever marketing that have changed its image. (Source: adapted from Financial Times, 3 March 2020 https://www.ft.com/ content/6fb6d73a-5d24-11ea-8033-fa40a0d65a98)
(a) With reference to Figure 1, calculate the three-firm concentration ratio for branded coffee shop chains. (5)
June 2022 · Paper 1 · Q6(b) 8 marks AO1=2, AO2=2, AO3=2, AO4=2 8-mark response Hard price elasticity of demandelasticity of supply
Data and extracts for question 6UK branded coffee shop chains market Figure 1: Branded coffee shops by number of shops in the UK in 2021 Costa 2681 Starbucks 1025 Caffè Nero 648 Coffee 50 AMT shop chains 40 Soho Coffee 30 Coffee Republic 3748 Other chains 0 500 1000 1500 2000 2500 3000 3500 4000 Number of shops (Source: adapted from https://www.statista.com/statistics/297863/ leading-coffee-shop-chains-in-the-united-kingdom-uk-store-number/) Figure 2: International coffee price (Arabica bean), US dollars per kilogram Month Price Change Jan 2020 3.13 – Feb 2020 2.99 –4.47% Mar 2020 3.27 9.36% Apr 2020 3.41 4.28% May 2020 3.30 –3.23% Jun 2020 3.12 –5.45% Jul 2020 3.24 3.85% Aug 2020 3.60 11.11% Sep 2020 3.67 1.94% Oct 2020 3.35 –8.72% Nov 2020 3.31 –1.19% Dec 2020 3.48 5.14% (Source: adapted from https://www.indexmundi.com/commodities/ ?commodity=other-mild-arabicas-coffee&months=12) Extract A Tough market conditions for coffee shops – but coffee quality is king UK coffee shop chains have experienced slow growth opportunities and rising costs. In 2019 the UK market leader, Costa Coffee, opened over 60% fewer stores than in 2018, while Starbucks opened just three new stores overall in 2019. By 2020, many costs were rising: staff shortages meant rising wages for baristas (trained 5 coffeemakers), a 6.2% National Minimum Wage increase for over 25-year-olds and rising rents. In a challenging UK economy, consumers placed coffee quality ahead of convenient location when choosing a coffee shop. This demonstrates the need for coffee shops to match rising expectations in the UK’s increasingly crowded coffee shop market in 10 order to stay competitive. Independent coffee shops (total 25 892 shops in 2020) remain a threat to the branded coffee shops as they pursue a unique luxury experience for customers. This will often focus on the atmosphere and customer service, luxury food and drink ranges and being a part of the local community. Independent coffee shops run on average profit as low as 2% of revenue, and many go out of business as new chains 15 arrive in a locality. In January 2020, Coca-Cola finalised its £3.9 billion takeover of market leader, Costa Coffee. The Coca-Cola company’s stated aims are to maximise long-term returns to shareholders while being mindful of overall responsibilities such as supporting sustainable communities. Major brands, such as Costa, continue to lead coffee shop 20 expansion in 2020 as competition intensifies. (Source: adapted from https://www.worldcoffeeportal.com/Latest/InsightAnalysis/2020/ February/5-UK-coffee-shop-market-dynamics-to-watch-in-2020) Extract B Greggs aiming for ‘coffee shop experience’ Greggs is looking to increase its branded coffee shop market share after the British bakery chain achieved record profits and overtook Starbucks in the amount of coffee it served in the UK. Although Greggs will continue to focus on the food-to-go market, it will be investing in better coffee machines and providing WiFi. It wants one in three 5 new outlets to have more seating. The company believes that it has the ability to take market share in two ways, by expanding its coffee range and at the same time enhancing the coffee shop experience. Greggs is modelling its plan on rival chain Pret A Manger, which has changed from focusing on food-to-go sales to mainly eating in. Greggs has transformed itself from an unremarkable seller of bread and pastries into one of the UK’s 10 most popular food-on-the-go chains, in part thanks to its embrace of vegan, gluten-free and healthy options as well as clever marketing that have changed its image. (Source: adapted from Financial Times, 3 March 2020 https://www.ft.com/ content/6fb6d73a-5d24-11ea-8033-fa40a0d65a98)
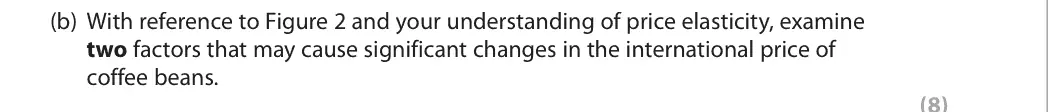
(b) With reference to Figure 2 and your understanding of price elasticity, examine two factors that may cause significant changes in the international price of coffee beans. (8)
June 2022 · Paper 1 · Q6(c) 10 marks AO1=2, AO2=2, AO3=2, AO4=4 10-mark response business growth and objectives
Data and extracts for question 6UK branded coffee shop chains market Figure 1: Branded coffee shops by number of shops in the UK in 2021 Costa 2681 Starbucks 1025 Caffè Nero 648 Coffee 50 AMT shop chains 40 Soho Coffee 30 Coffee Republic 3748 Other chains 0 500 1000 1500 2000 2500 3000 3500 4000 Number of shops (Source: adapted from https://www.statista.com/statistics/297863/ leading-coffee-shop-chains-in-the-united-kingdom-uk-store-number/) Figure 2: International coffee price (Arabica bean), US dollars per kilogram Month Price Change Jan 2020 3.13 – Feb 2020 2.99 –4.47% Mar 2020 3.27 9.36% Apr 2020 3.41 4.28% May 2020 3.30 –3.23% Jun 2020 3.12 –5.45% Jul 2020 3.24 3.85% Aug 2020 3.60 11.11% Sep 2020 3.67 1.94% Oct 2020 3.35 –8.72% Nov 2020 3.31 –1.19% Dec 2020 3.48 5.14% (Source: adapted from https://www.indexmundi.com/commodities/ ?commodity=other-mild-arabicas-coffee&months=12) Extract A Tough market conditions for coffee shops – but coffee quality is king UK coffee shop chains have experienced slow growth opportunities and rising costs. In 2019 the UK market leader, Costa Coffee, opened over 60% fewer stores than in 2018, while Starbucks opened just three new stores overall in 2019. By 2020, many costs were rising: staff shortages meant rising wages for baristas (trained 5 coffeemakers), a 6.2% National Minimum Wage increase for over 25-year-olds and rising rents. In a challenging UK economy, consumers placed coffee quality ahead of convenient location when choosing a coffee shop. This demonstrates the need for coffee shops to match rising expectations in the UK’s increasingly crowded coffee shop market in 10 order to stay competitive. Independent coffee shops (total 25 892 shops in 2020) remain a threat to the branded coffee shops as they pursue a unique luxury experience for customers. This will often focus on the atmosphere and customer service, luxury food and drink ranges and being a part of the local community. Independent coffee shops run on average profit as low as 2% of revenue, and many go out of business as new chains 15 arrive in a locality. In January 2020, Coca-Cola finalised its £3.9 billion takeover of market leader, Costa Coffee. The Coca-Cola company’s stated aims are to maximise long-term returns to shareholders while being mindful of overall responsibilities such as supporting sustainable communities. Major brands, such as Costa, continue to lead coffee shop 20 expansion in 2020 as competition intensifies. (Source: adapted from https://www.worldcoffeeportal.com/Latest/InsightAnalysis/2020/ February/5-UK-coffee-shop-market-dynamics-to-watch-in-2020) Extract B Greggs aiming for ‘coffee shop experience’ Greggs is looking to increase its branded coffee shop market share after the British bakery chain achieved record profits and overtook Starbucks in the amount of coffee it served in the UK. Although Greggs will continue to focus on the food-to-go market, it will be investing in better coffee machines and providing WiFi. It wants one in three 5 new outlets to have more seating. The company believes that it has the ability to take market share in two ways, by expanding its coffee range and at the same time enhancing the coffee shop experience. Greggs is modelling its plan on rival chain Pret A Manger, which has changed from focusing on food-to-go sales to mainly eating in. Greggs has transformed itself from an unremarkable seller of bread and pastries into one of the UK’s 10 most popular food-on-the-go chains, in part thanks to its embrace of vegan, gluten-free and healthy options as well as clever marketing that have changed its image. (Source: adapted from Financial Times, 3 March 2020 https://www.ft.com/ content/6fb6d73a-5d24-11ea-8033-fa40a0d65a98)
(c) Profit maximisation is assumed to be the business objective of most firms. With reference to Extract A, assess whether this is the case for coffee shop owners. (10)
June 2022 · Paper 1 · Q6(d) 12 marks AO1=2, AO2=2, AO3=4, AO4=4 12-mark response revenues costs and profits
Data and extracts for question 6UK branded coffee shop chains market Figure 1: Branded coffee shops by number of shops in the UK in 2021 Costa 2681 Starbucks 1025 Caffè Nero 648 Coffee 50 AMT shop chains 40 Soho Coffee 30 Coffee Republic 3748 Other chains 0 500 1000 1500 2000 2500 3000 3500 4000 Number of shops (Source: adapted from https://www.statista.com/statistics/297863/ leading-coffee-shop-chains-in-the-united-kingdom-uk-store-number/) Figure 2: International coffee price (Arabica bean), US dollars per kilogram Month Price Change Jan 2020 3.13 – Feb 2020 2.99 –4.47% Mar 2020 3.27 9.36% Apr 2020 3.41 4.28% May 2020 3.30 –3.23% Jun 2020 3.12 –5.45% Jul 2020 3.24 3.85% Aug 2020 3.60 11.11% Sep 2020 3.67 1.94% Oct 2020 3.35 –8.72% Nov 2020 3.31 –1.19% Dec 2020 3.48 5.14% (Source: adapted from https://www.indexmundi.com/commodities/ ?commodity=other-mild-arabicas-coffee&months=12) Extract A Tough market conditions for coffee shops – but coffee quality is king UK coffee shop chains have experienced slow growth opportunities and rising costs. In 2019 the UK market leader, Costa Coffee, opened over 60% fewer stores than in 2018, while Starbucks opened just three new stores overall in 2019. By 2020, many costs were rising: staff shortages meant rising wages for baristas (trained 5 coffeemakers), a 6.2% National Minimum Wage increase for over 25-year-olds and rising rents. In a challenging UK economy, consumers placed coffee quality ahead of convenient location when choosing a coffee shop. This demonstrates the need for coffee shops to match rising expectations in the UK’s increasingly crowded coffee shop market in 10 order to stay competitive. Independent coffee shops (total 25 892 shops in 2020) remain a threat to the branded coffee shops as they pursue a unique luxury experience for customers. This will often focus on the atmosphere and customer service, luxury food and drink ranges and being a part of the local community. Independent coffee shops run on average profit as low as 2% of revenue, and many go out of business as new chains 15 arrive in a locality. In January 2020, Coca-Cola finalised its £3.9 billion takeover of market leader, Costa Coffee. The Coca-Cola company’s stated aims are to maximise long-term returns to shareholders while being mindful of overall responsibilities such as supporting sustainable communities. Major brands, such as Costa, continue to lead coffee shop 20 expansion in 2020 as competition intensifies. (Source: adapted from https://www.worldcoffeeportal.com/Latest/InsightAnalysis/2020/ February/5-UK-coffee-shop-market-dynamics-to-watch-in-2020) Extract B Greggs aiming for ‘coffee shop experience’ Greggs is looking to increase its branded coffee shop market share after the British bakery chain achieved record profits and overtook Starbucks in the amount of coffee it served in the UK. Although Greggs will continue to focus on the food-to-go market, it will be investing in better coffee machines and providing WiFi. It wants one in three 5 new outlets to have more seating. The company believes that it has the ability to take market share in two ways, by expanding its coffee range and at the same time enhancing the coffee shop experience. Greggs is modelling its plan on rival chain Pret A Manger, which has changed from focusing on food-to-go sales to mainly eating in. Greggs has transformed itself from an unremarkable seller of bread and pastries into one of the UK’s 10 most popular food-on-the-go chains, in part thanks to its embrace of vegan, gluten-free and healthy options as well as clever marketing that have changed its image. (Source: adapted from Financial Times, 3 March 2020 https://www.ft.com/ content/6fb6d73a-5d24-11ea-8033-fa40a0d65a98)
(d) Using a cost and revenue diagram, discuss the likely impact of ‘rising costs’ for coffee shops on their profitability (Extract A, line 2). (12)
June 2022 · Paper 1 · Q6(e) 15 marks AO1=3, AO2=3, AO3=3, AO4=6 15-mark response monopsony and contestability
Data and extracts for question 6UK branded coffee shop chains market Figure 1: Branded coffee shops by number of shops in the UK in 2021 Costa 2681 Starbucks 1025 Caffè Nero 648 Coffee 50 AMT shop chains 40 Soho Coffee 30 Coffee Republic 3748 Other chains 0 500 1000 1500 2000 2500 3000 3500 4000 Number of shops (Source: adapted from https://www.statista.com/statistics/297863/ leading-coffee-shop-chains-in-the-united-kingdom-uk-store-number/) Figure 2: International coffee price (Arabica bean), US dollars per kilogram Month Price Change Jan 2020 3.13 – Feb 2020 2.99 –4.47% Mar 2020 3.27 9.36% Apr 2020 3.41 4.28% May 2020 3.30 –3.23% Jun 2020 3.12 –5.45% Jul 2020 3.24 3.85% Aug 2020 3.60 11.11% Sep 2020 3.67 1.94% Oct 2020 3.35 –8.72% Nov 2020 3.31 –1.19% Dec 2020 3.48 5.14% (Source: adapted from https://www.indexmundi.com/commodities/ ?commodity=other-mild-arabicas-coffee&months=12) Extract A Tough market conditions for coffee shops – but coffee quality is king UK coffee shop chains have experienced slow growth opportunities and rising costs. In 2019 the UK market leader, Costa Coffee, opened over 60% fewer stores than in 2018, while Starbucks opened just three new stores overall in 2019. By 2020, many costs were rising: staff shortages meant rising wages for baristas (trained 5 coffeemakers), a 6.2% National Minimum Wage increase for over 25-year-olds and rising rents. In a challenging UK economy, consumers placed coffee quality ahead of convenient location when choosing a coffee shop. This demonstrates the need for coffee shops to match rising expectations in the UK’s increasingly crowded coffee shop market in 10 order to stay competitive. Independent coffee shops (total 25 892 shops in 2020) remain a threat to the branded coffee shops as they pursue a unique luxury experience for customers. This will often focus on the atmosphere and customer service, luxury food and drink ranges and being a part of the local community. Independent coffee shops run on average profit as low as 2% of revenue, and many go out of business as new chains 15 arrive in a locality. In January 2020, Coca-Cola finalised its £3.9 billion takeover of market leader, Costa Coffee. The Coca-Cola company’s stated aims are to maximise long-term returns to shareholders while being mindful of overall responsibilities such as supporting sustainable communities. Major brands, such as Costa, continue to lead coffee shop 20 expansion in 2020 as competition intensifies. (Source: adapted from https://www.worldcoffeeportal.com/Latest/InsightAnalysis/2020/ February/5-UK-coffee-shop-market-dynamics-to-watch-in-2020) Extract B Greggs aiming for ‘coffee shop experience’ Greggs is looking to increase its branded coffee shop market share after the British bakery chain achieved record profits and overtook Starbucks in the amount of coffee it served in the UK. Although Greggs will continue to focus on the food-to-go market, it will be investing in better coffee machines and providing WiFi. It wants one in three 5 new outlets to have more seating. The company believes that it has the ability to take market share in two ways, by expanding its coffee range and at the same time enhancing the coffee shop experience. Greggs is modelling its plan on rival chain Pret A Manger, which has changed from focusing on food-to-go sales to mainly eating in. Greggs has transformed itself from an unremarkable seller of bread and pastries into one of the UK’s 10 most popular food-on-the-go chains, in part thanks to its embrace of vegan, gluten-free and healthy options as well as clever marketing that have changed its image. (Source: adapted from Financial Times, 3 March 2020 https://www.ft.com/ content/6fb6d73a-5d24-11ea-8033-fa40a0d65a98)
(e) With reference to the information provided, discuss whether the coffee shop market is contestable. (15)
June 2022 · Paper 1 · Q7 25 marks AO1=4, AO2=4, AO3=8, AO4=9 25-mark essay Either/or monopolymarket structures and efficiency
7 Tesla held an 82% market share of the electric vehicle market in the United States during the first half of 2020. (Source: adapted from https://electrek.co/2020/08/21/ tesla-holds-us-ev-market-losing-federal-tax-credit/) Evaluate whether a monopoly is likely to operate efficiently. Refer to at least one monopoly of your choice.
June 2022 · Paper 1 · Q8 25 marks AO1=4, AO2=4, AO3=8, AO4=9 25-mark essay Either/or labour market
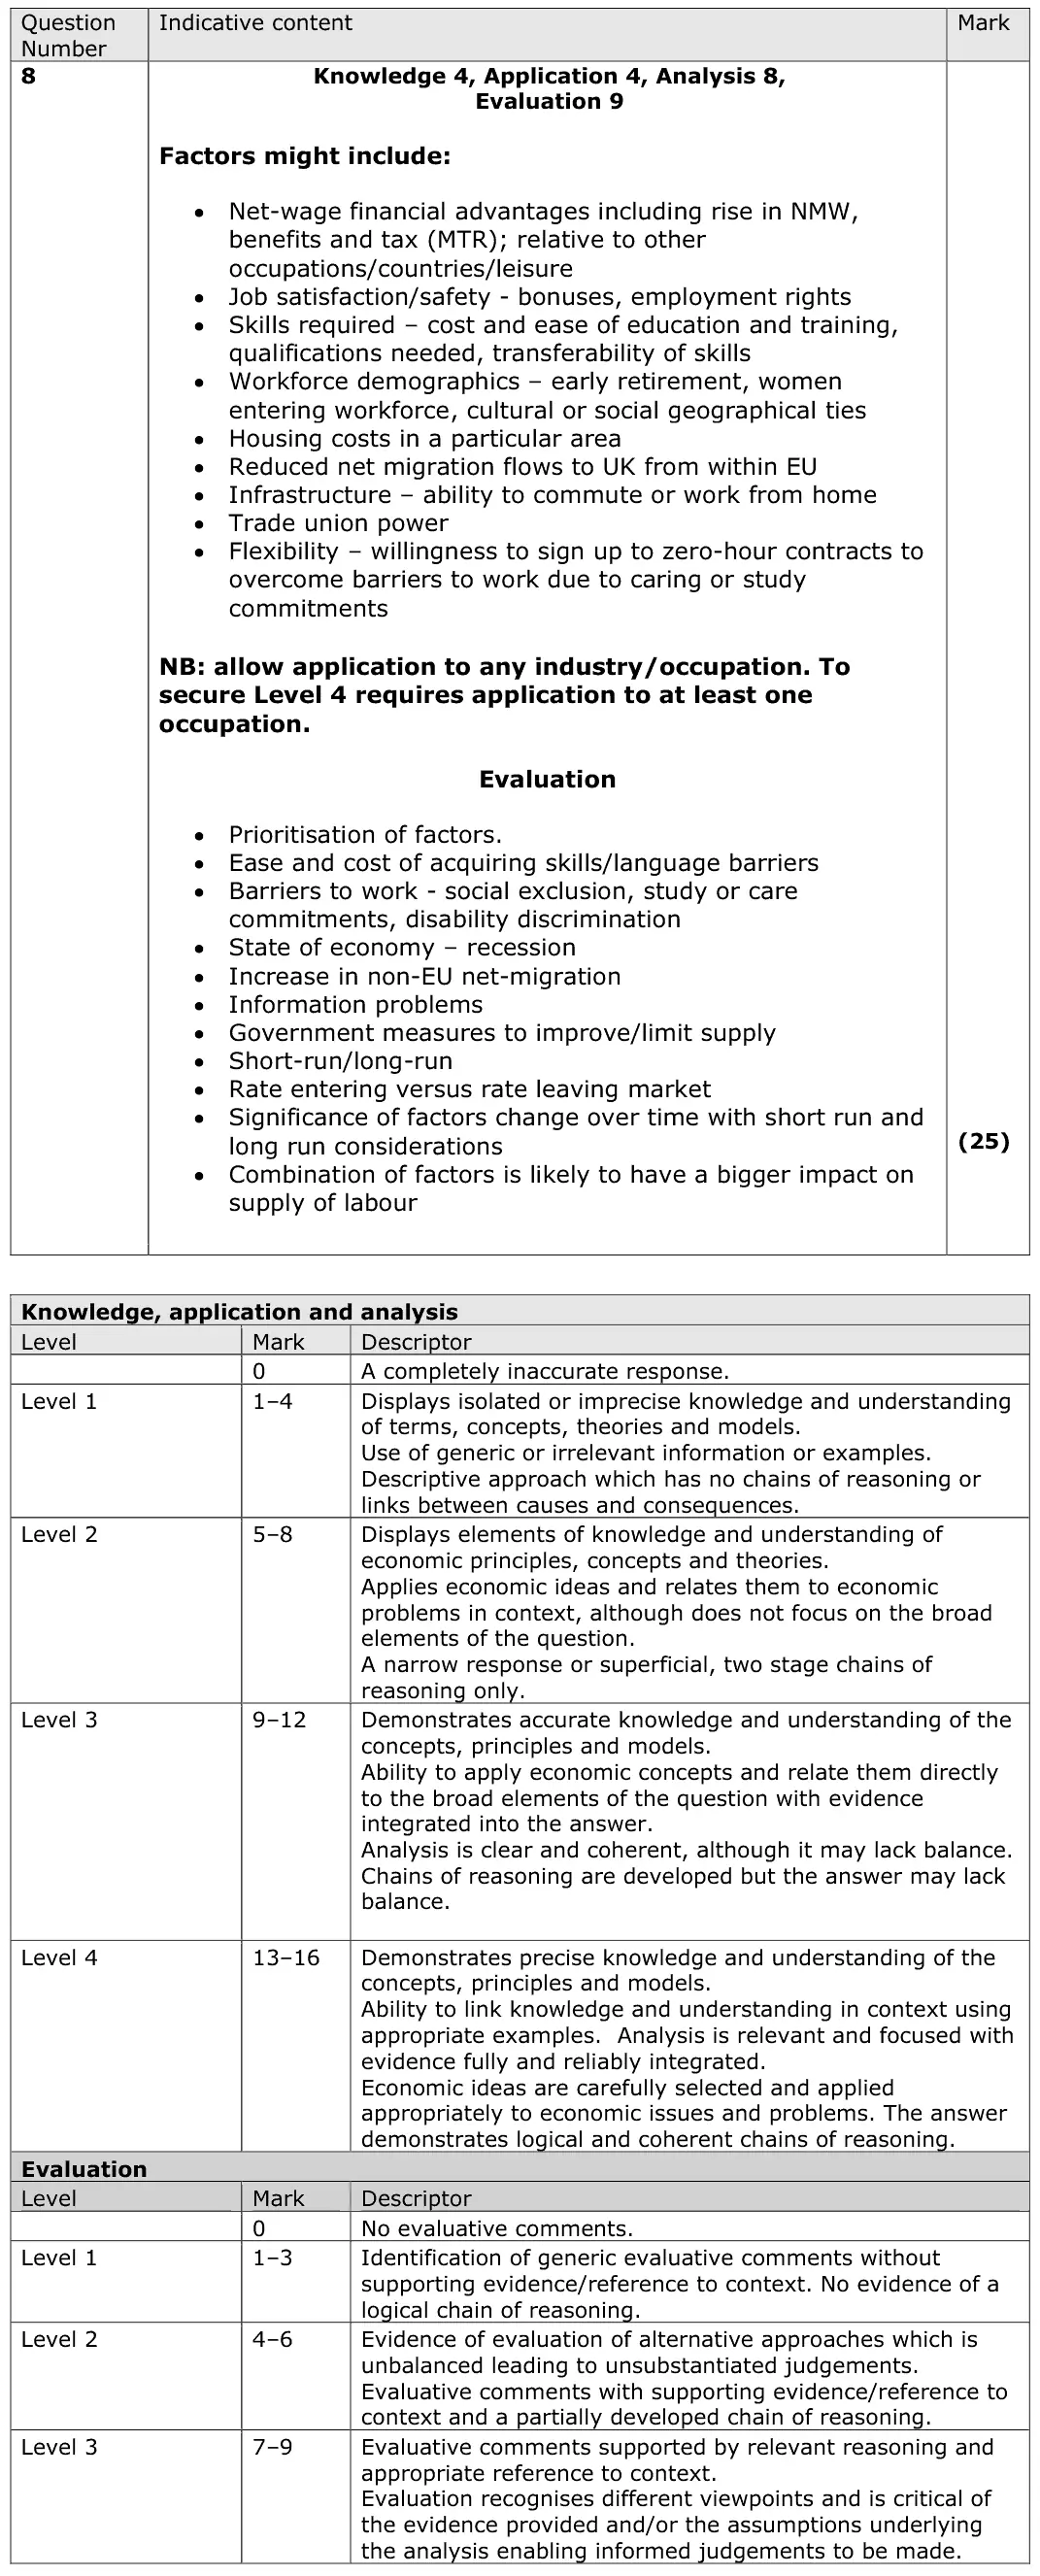
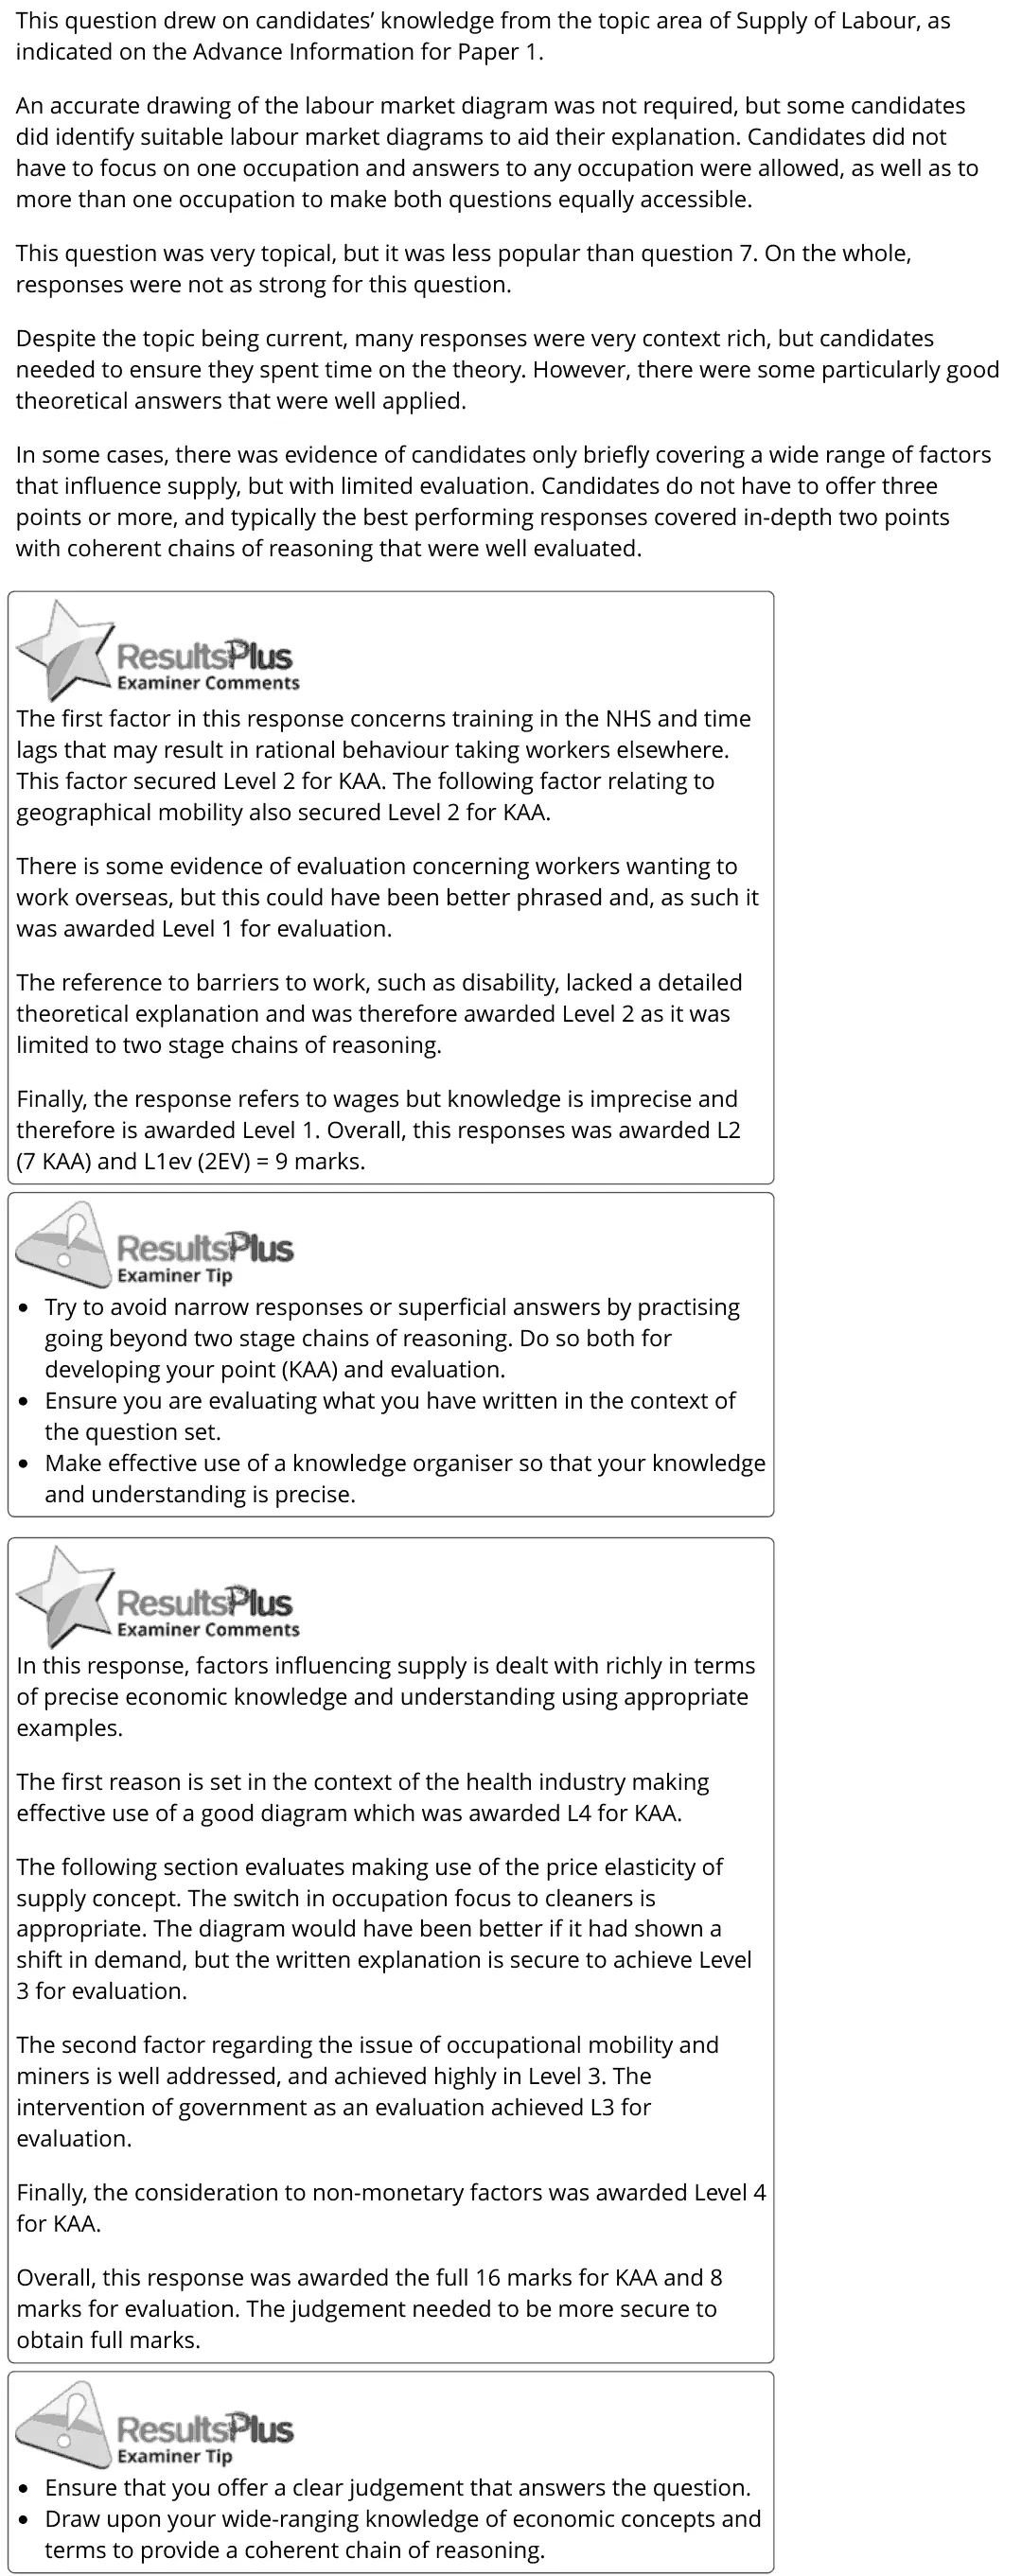
8 Some occupations in the UK are facing large labour shortages. Hard-to-fill vacancies include qualified chefs, software engineers, construction workers and qualified nurses. (Source: adapted from https://www.ft.com/content/ 36baacce-ddd0-11e8-9f04-38d397e6661c) Evaluate the factors that might influence the supply of labour in an occupation of your choice.

Work with an Edexcel economics tutor

Want a paper marked and gone through with you? Message us.

Prefer email? Send an enquiry

If you are under 18, please include a parent's contact details. Enquiries go to enquiries@economicsaleveltutor.com and are deleted once handled. All tutoring is online.