June 2016: AS Paper 2

80 marks · 20 question parts · Paper, mark scheme and report on Pearson's site

Question by question

QTopicMarksAOType
1(a) The circular flow, national income and the multiplier 1AO1=1Definition
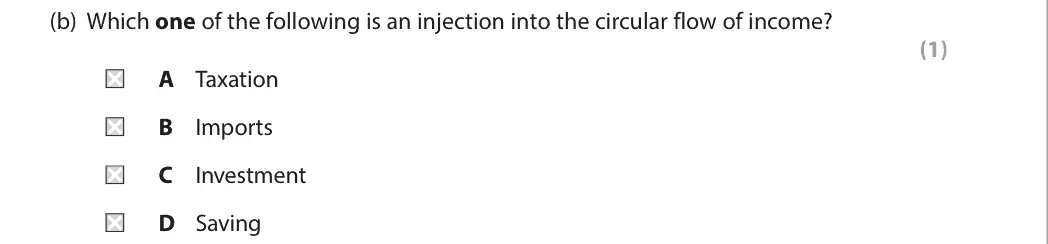
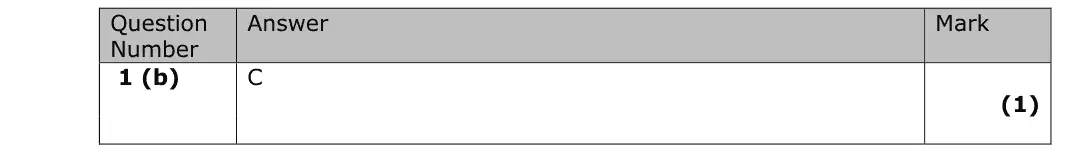
1(b) The circular flow, national income and the multiplier 1Multiple choice
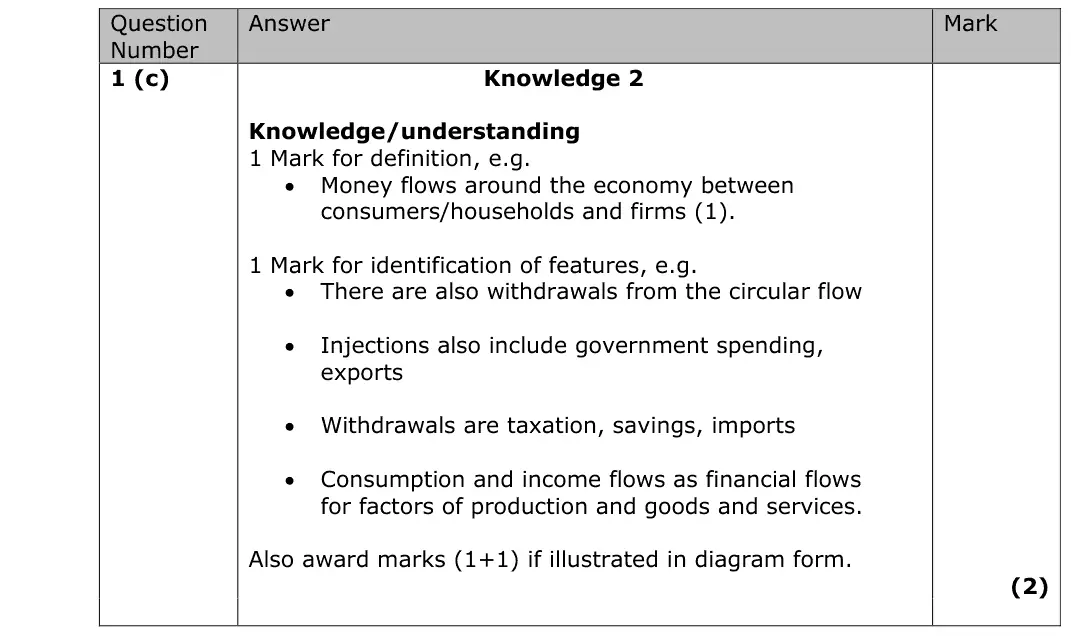
1(c) The circular flow, national income and the multiplier 2AO1=2Definition
2(a) Measuring economic growth: GDP, GNI and living standards 2AO1=2Definition
2(b) Measuring economic growth: GDP, GNI and living standards 1Multiple choice
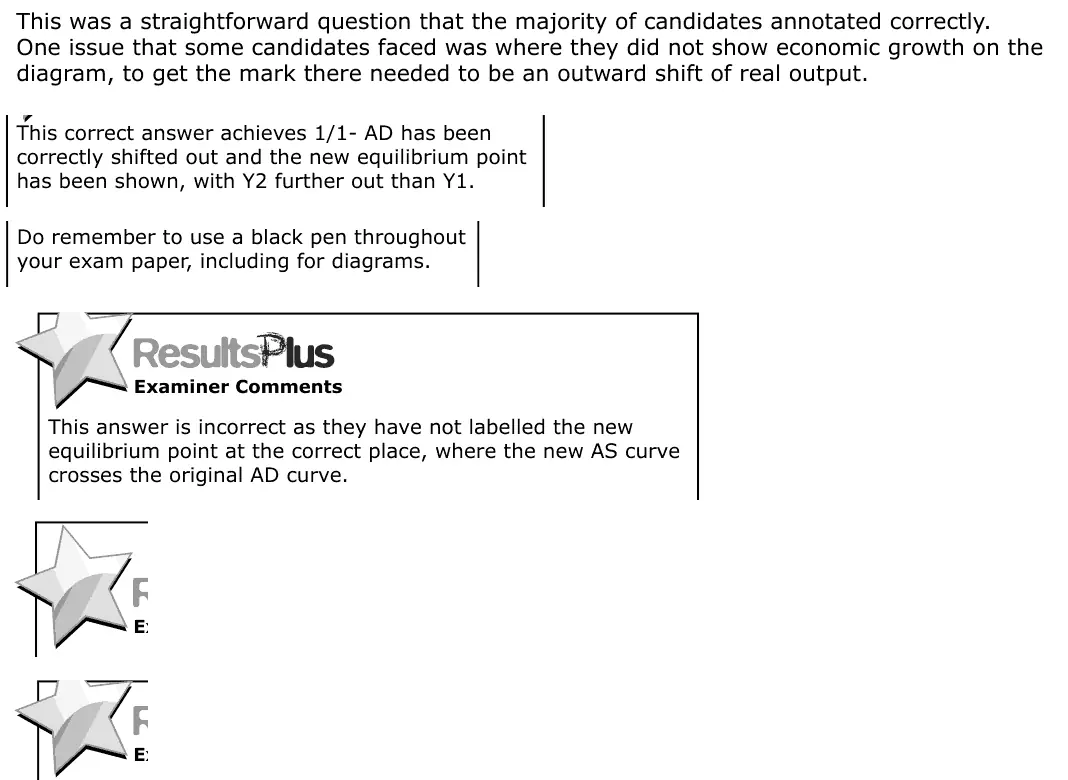
2(c) Economic growth, output gaps and the trade cycle, The circular flow, national income and the multiplier 1AO1=1Diagram
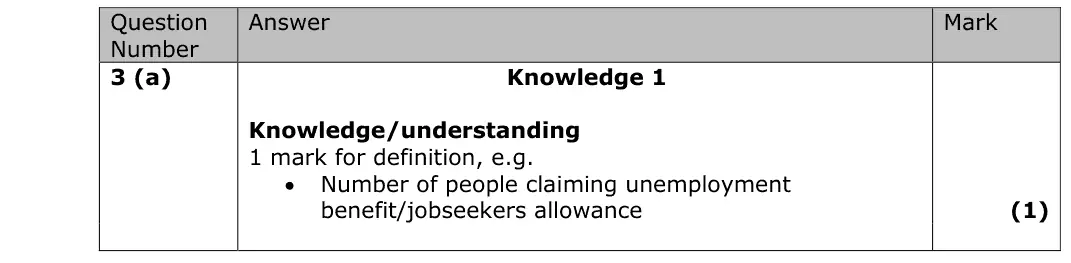
3(a) Employment and unemployment 1AO1=1Definition
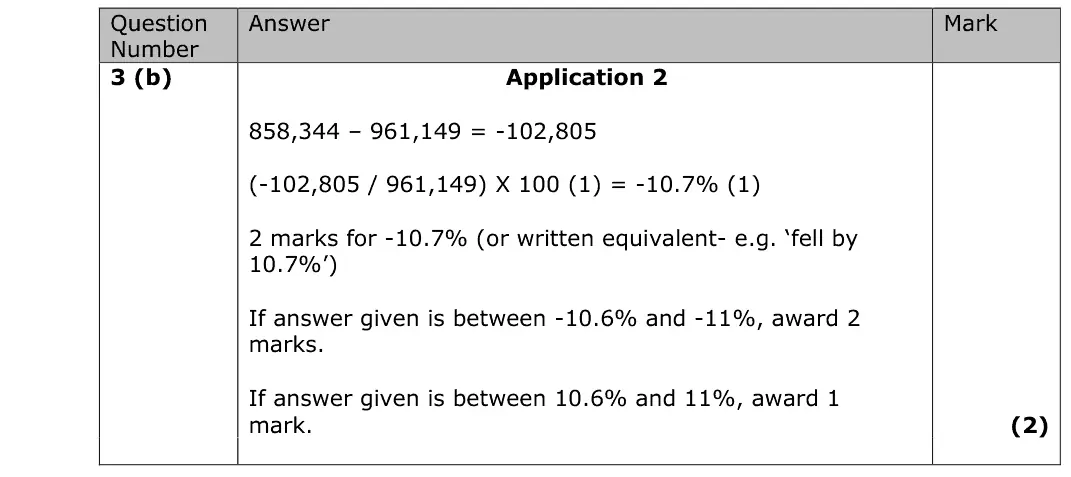
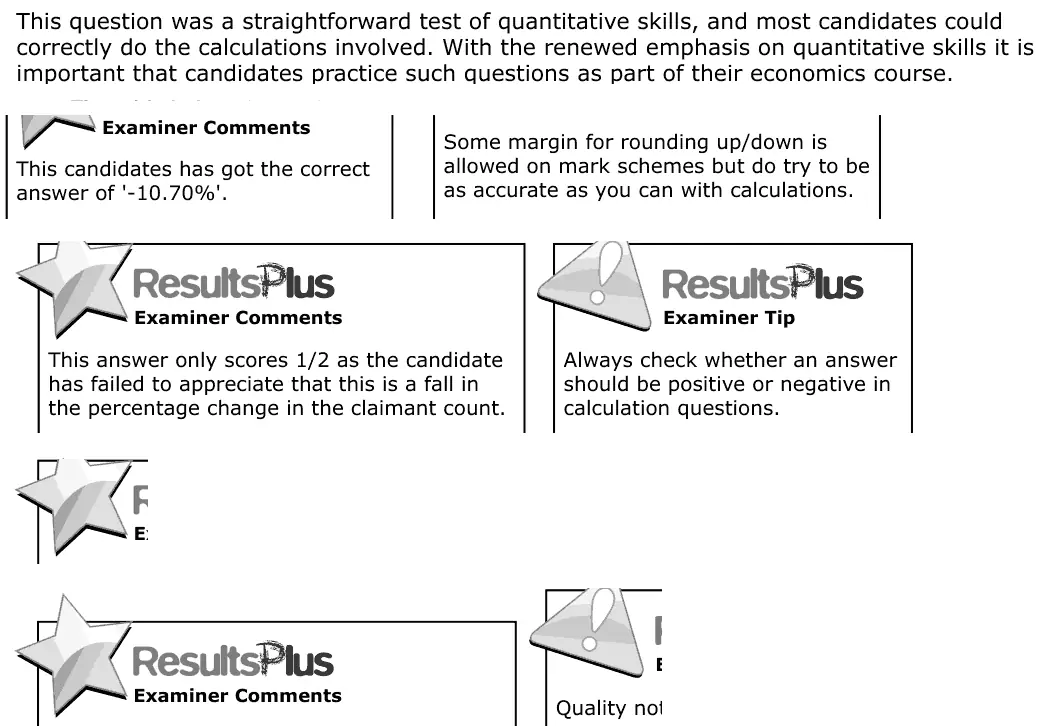
3(b) Employment and unemployment 2AO2=2Calculation
3(c) Employment and unemployment 1Multiple choice
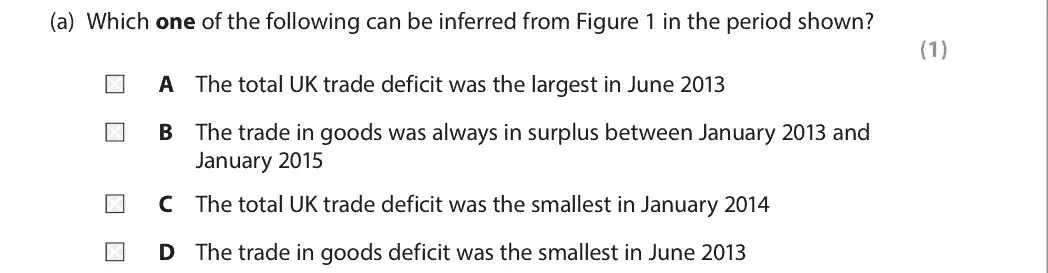
4(a) The balance of payments 1Multiple choice
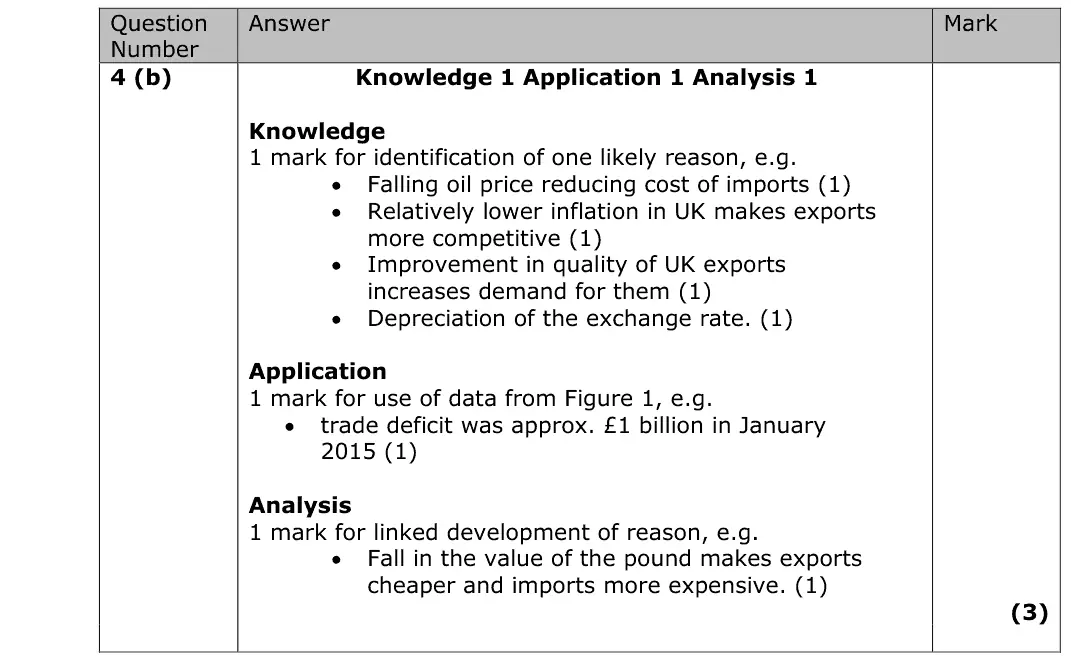
4(b) The balance of payments, Aggregate demand 3AO1=1,AO2=1,AO3=1Short answer
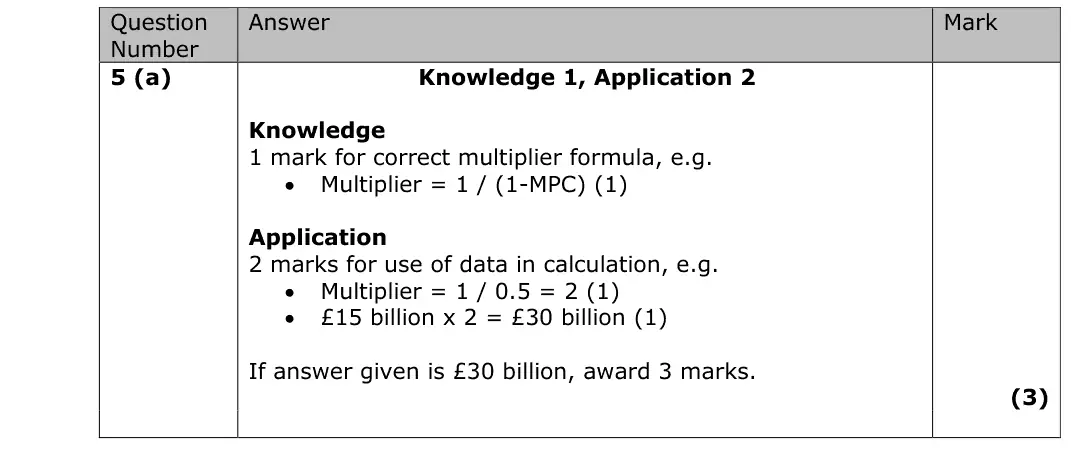
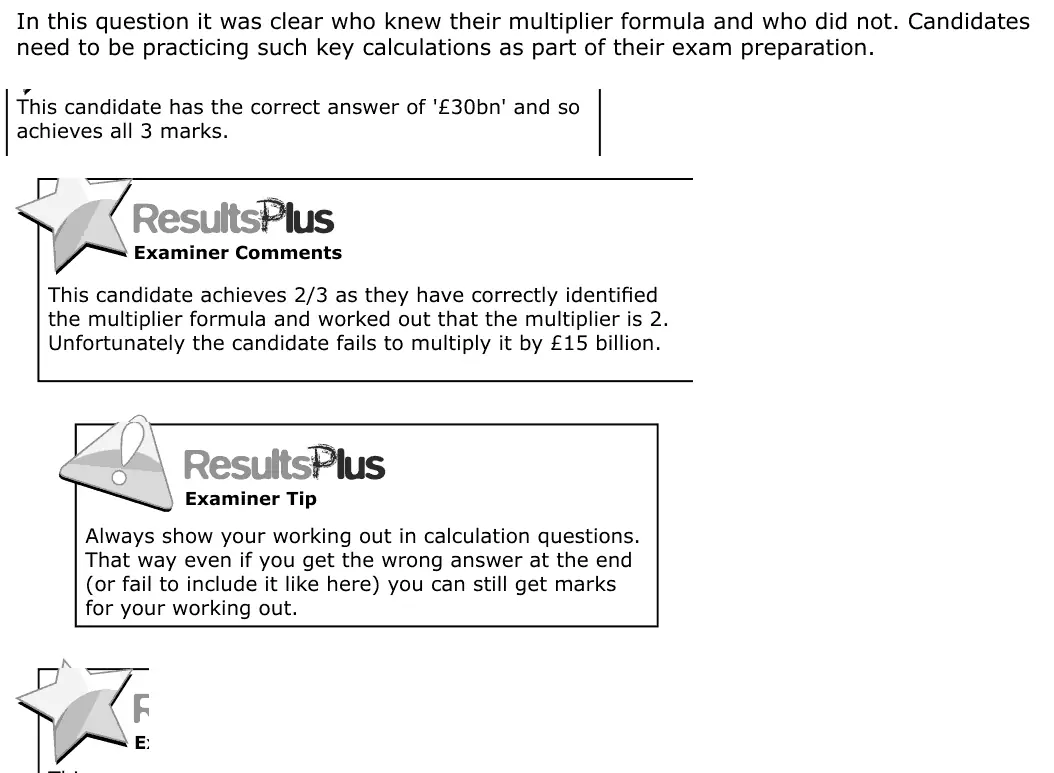
5(a) The circular flow, national income and the multiplier 3AO1=1,AO2=2Calculation
5(b) Aggregate supply 1Multiple choice
6(a) Measuring economic growth: GDP, GNI and living standards 4AO1=2,AO2=2Short answer
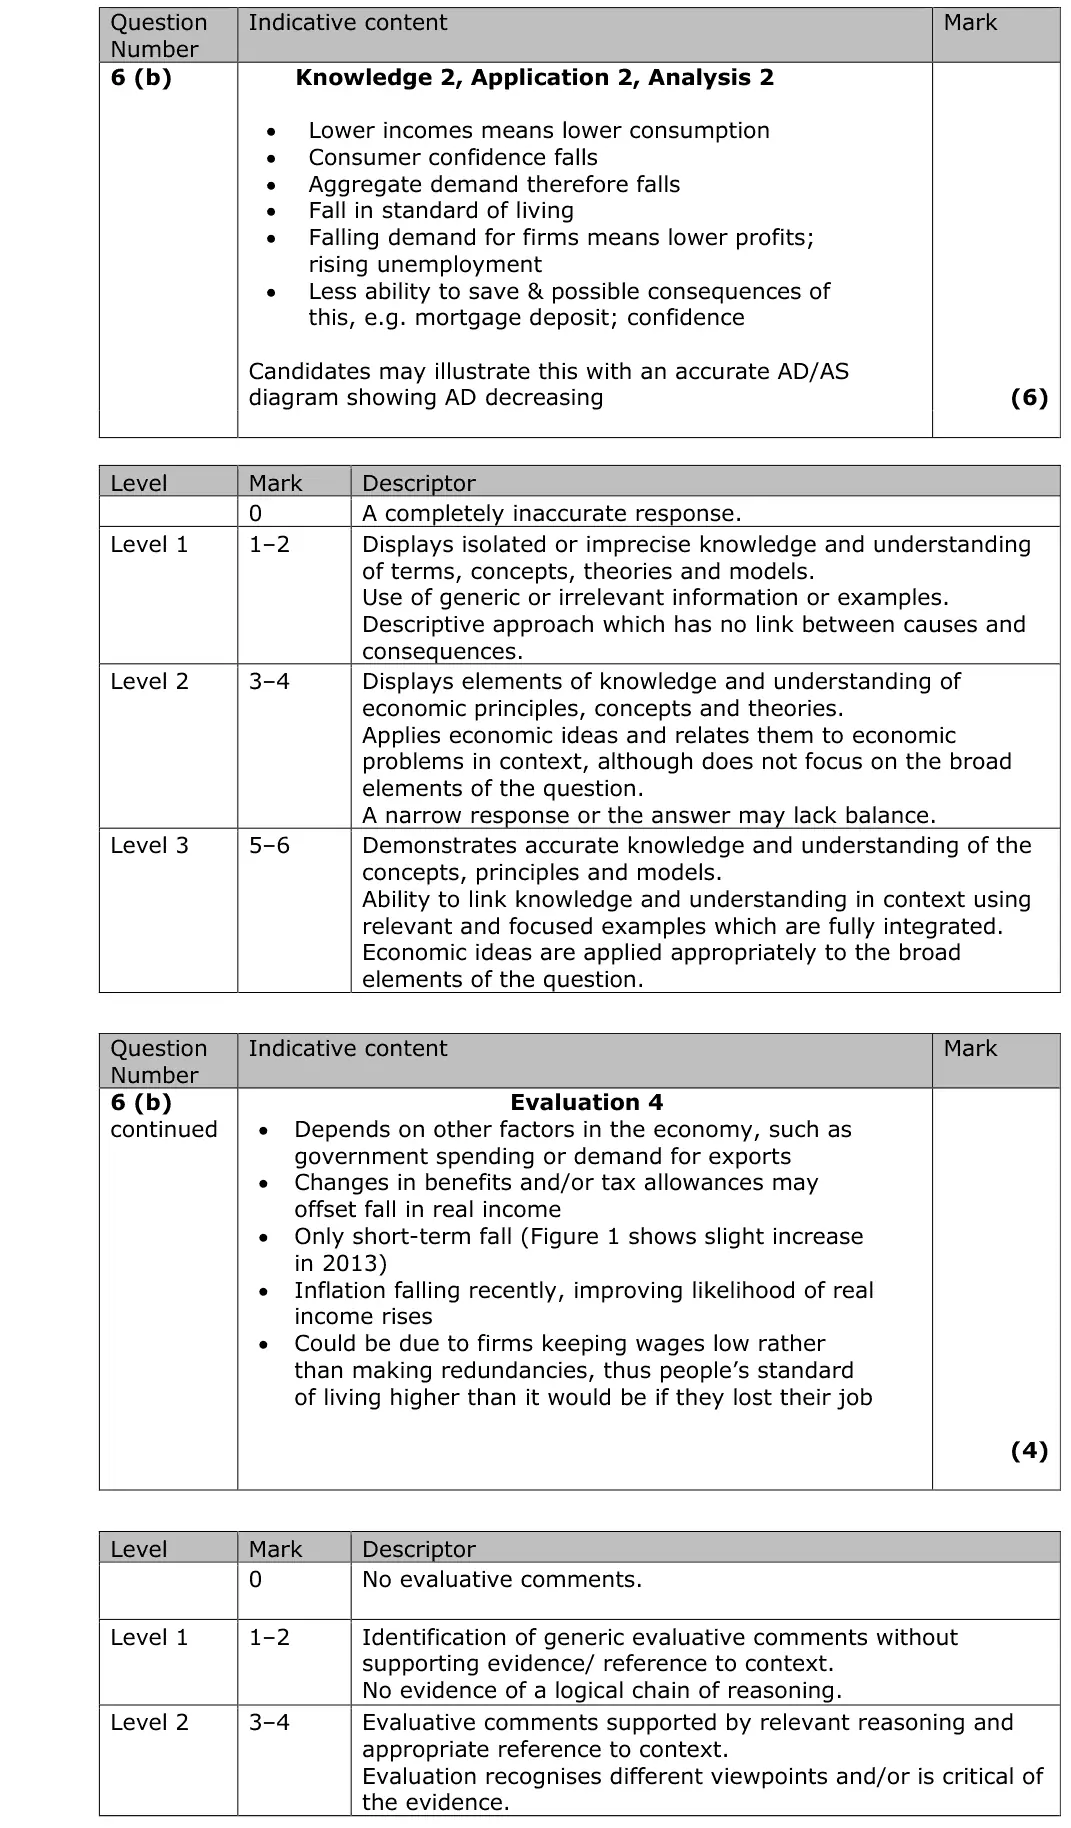
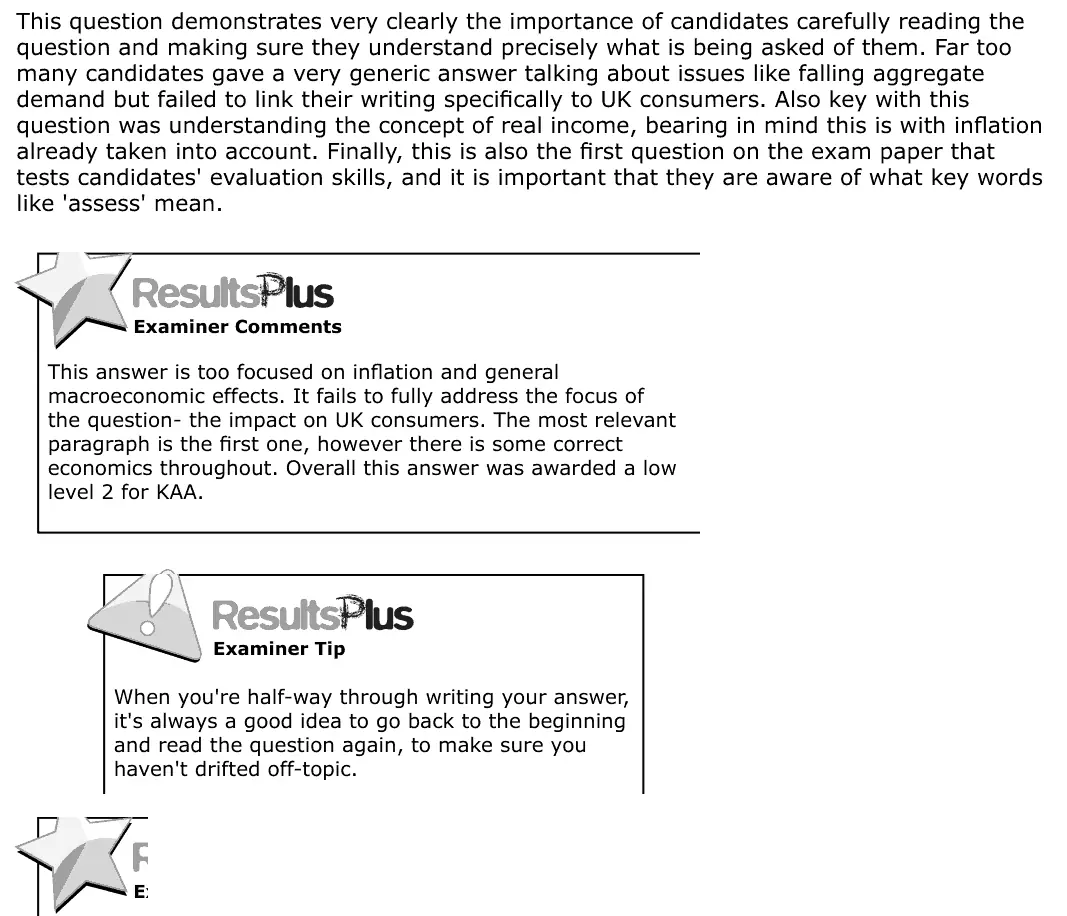
6(b) Aggregate demand 10AO1=2,AO2=2,AO3=2,AO4=4Extended response
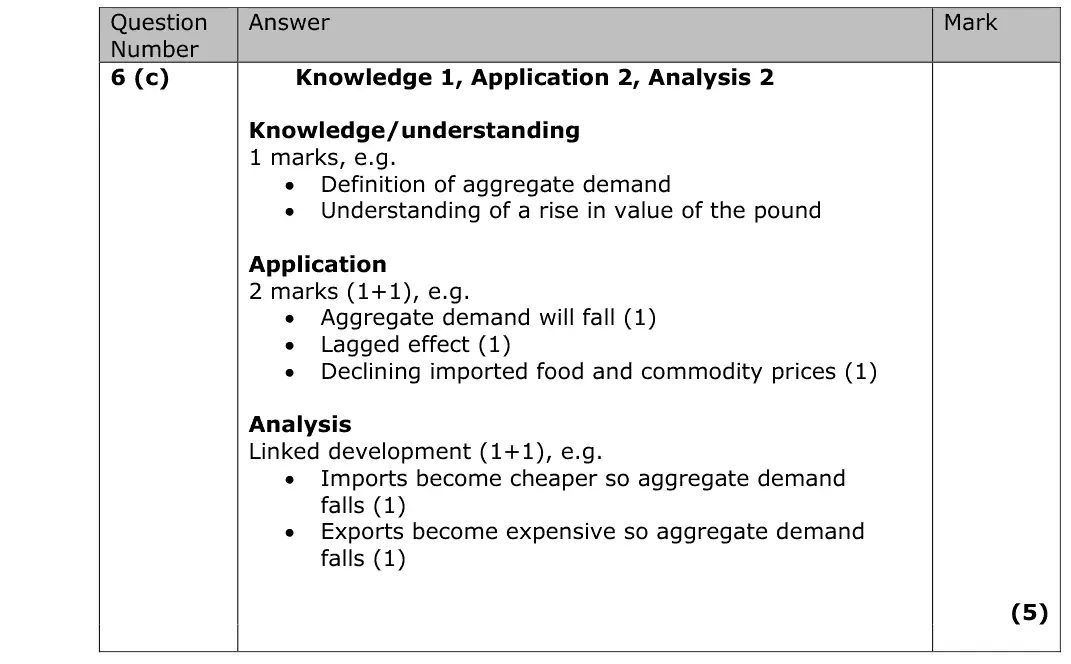
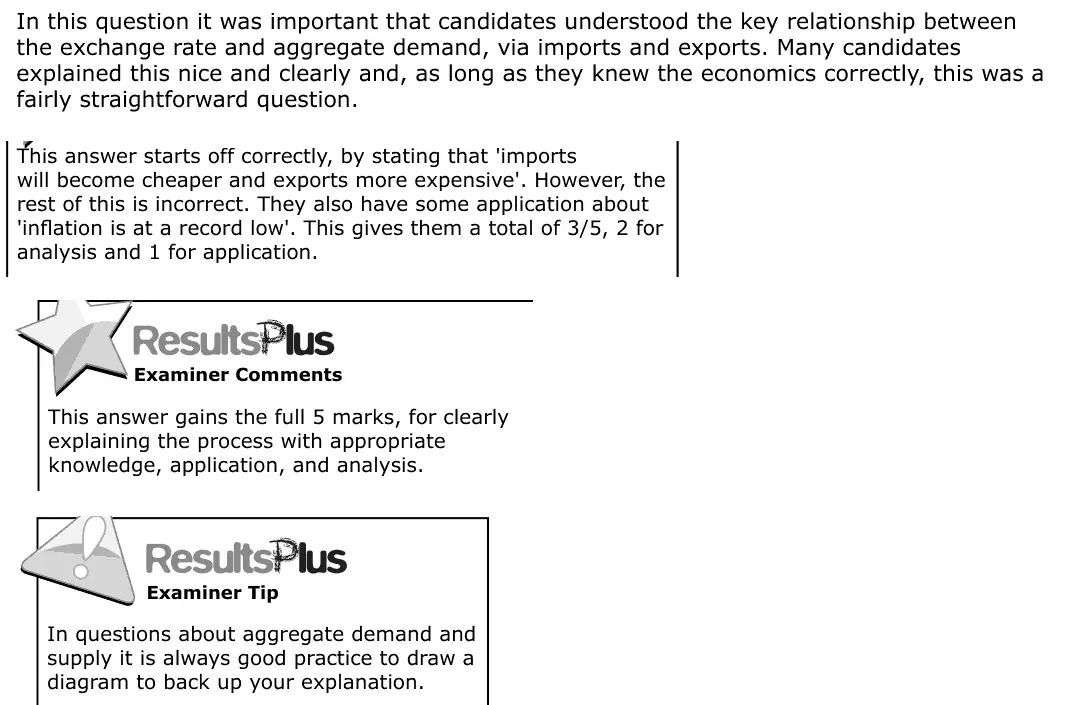
6(c) Aggregate demand 5AO1=1,AO2=2,AO3=2Short answer
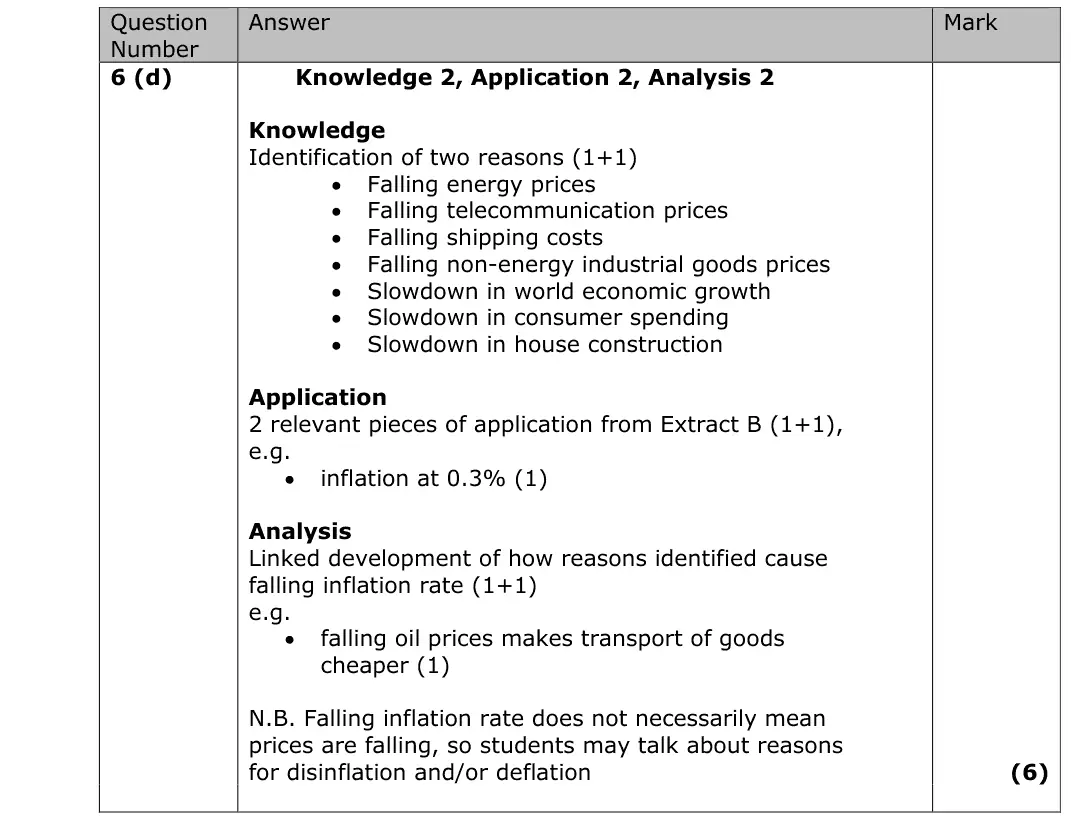
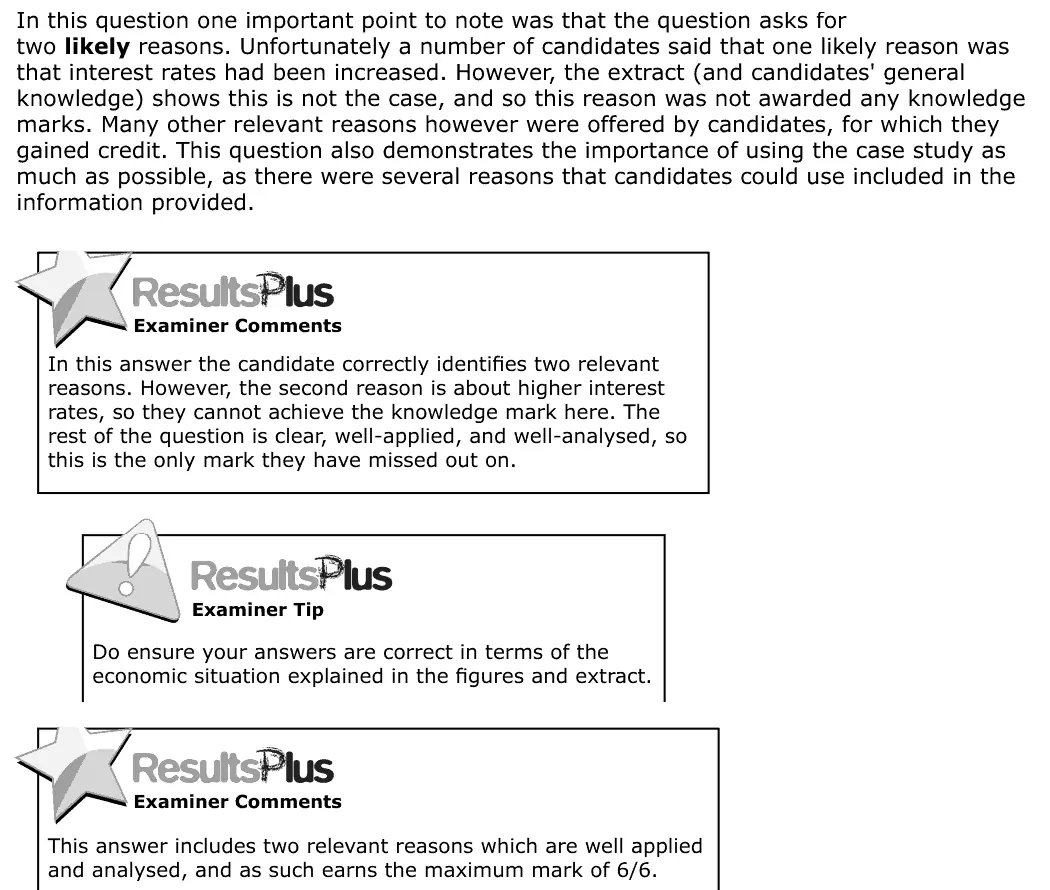
6(d) Inflation 6AO1=2,AO2=2,AO3=2Short answer
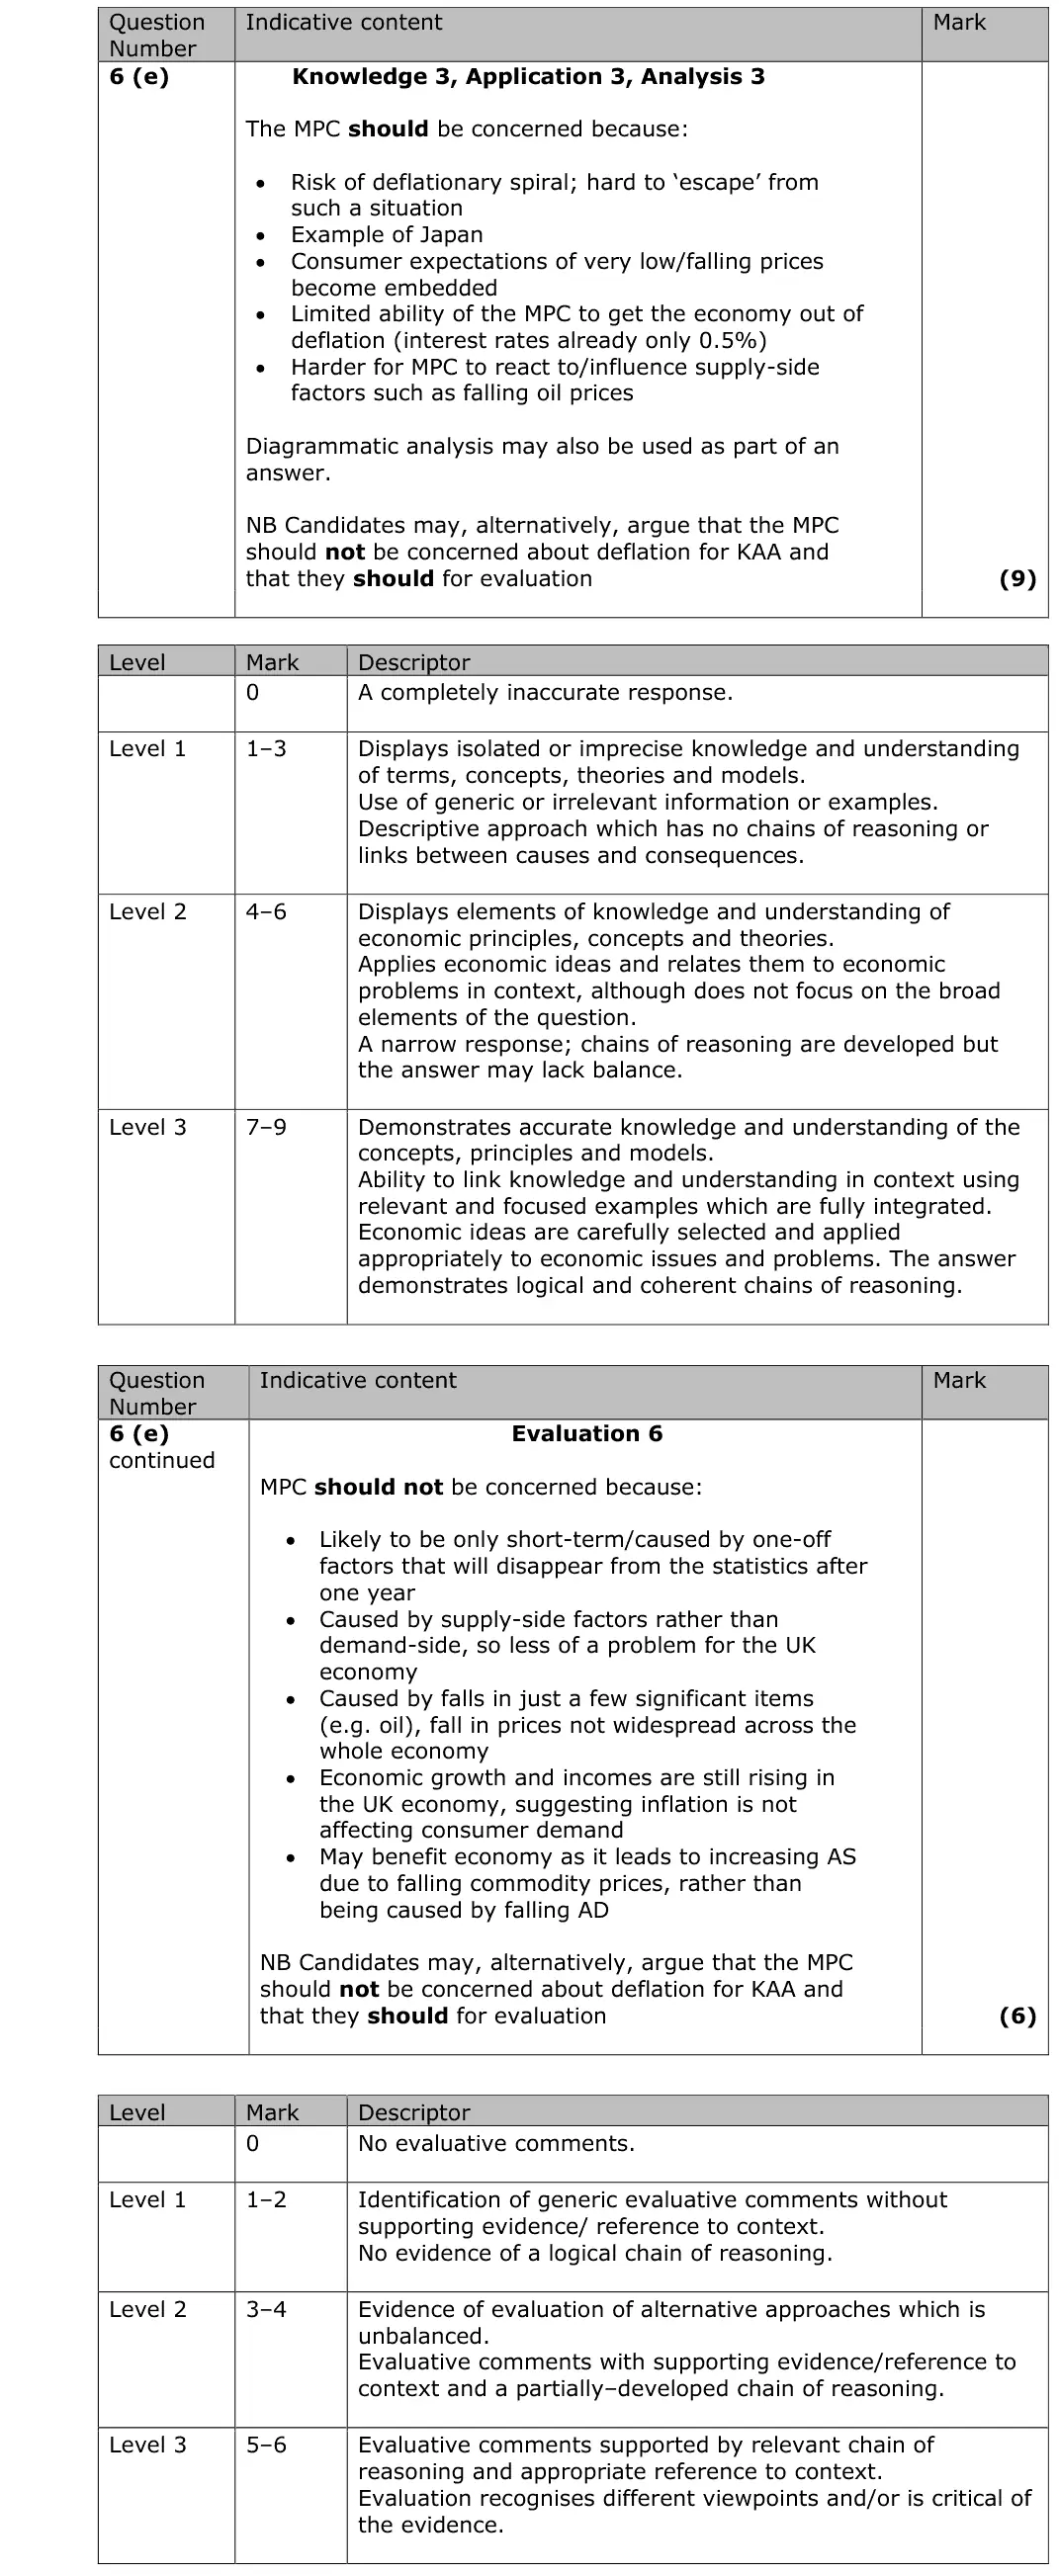
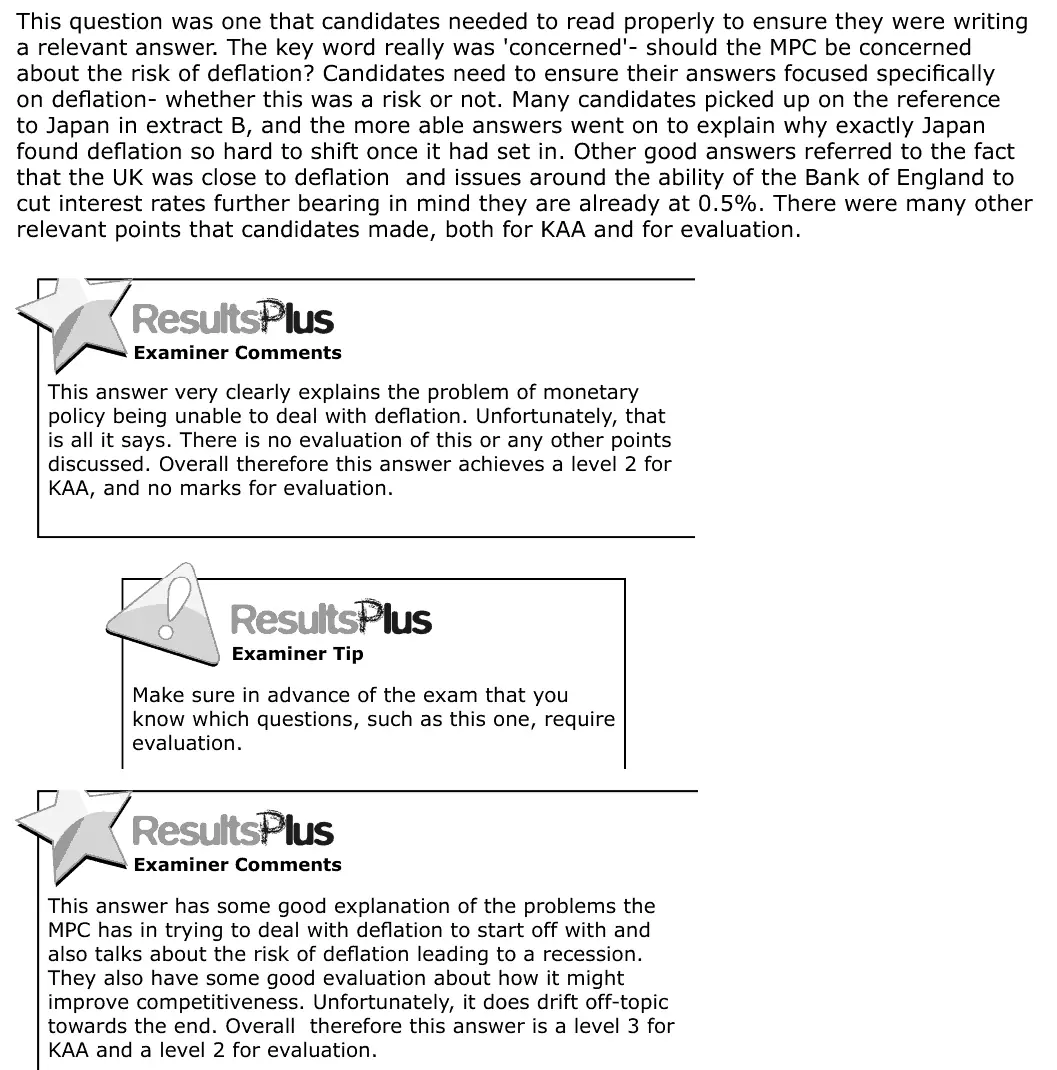
6(e) Inflation, Demand-side policies: fiscal and monetary policy 15AO1=3,AO2=3,AO3=3,AO4=6Extended response
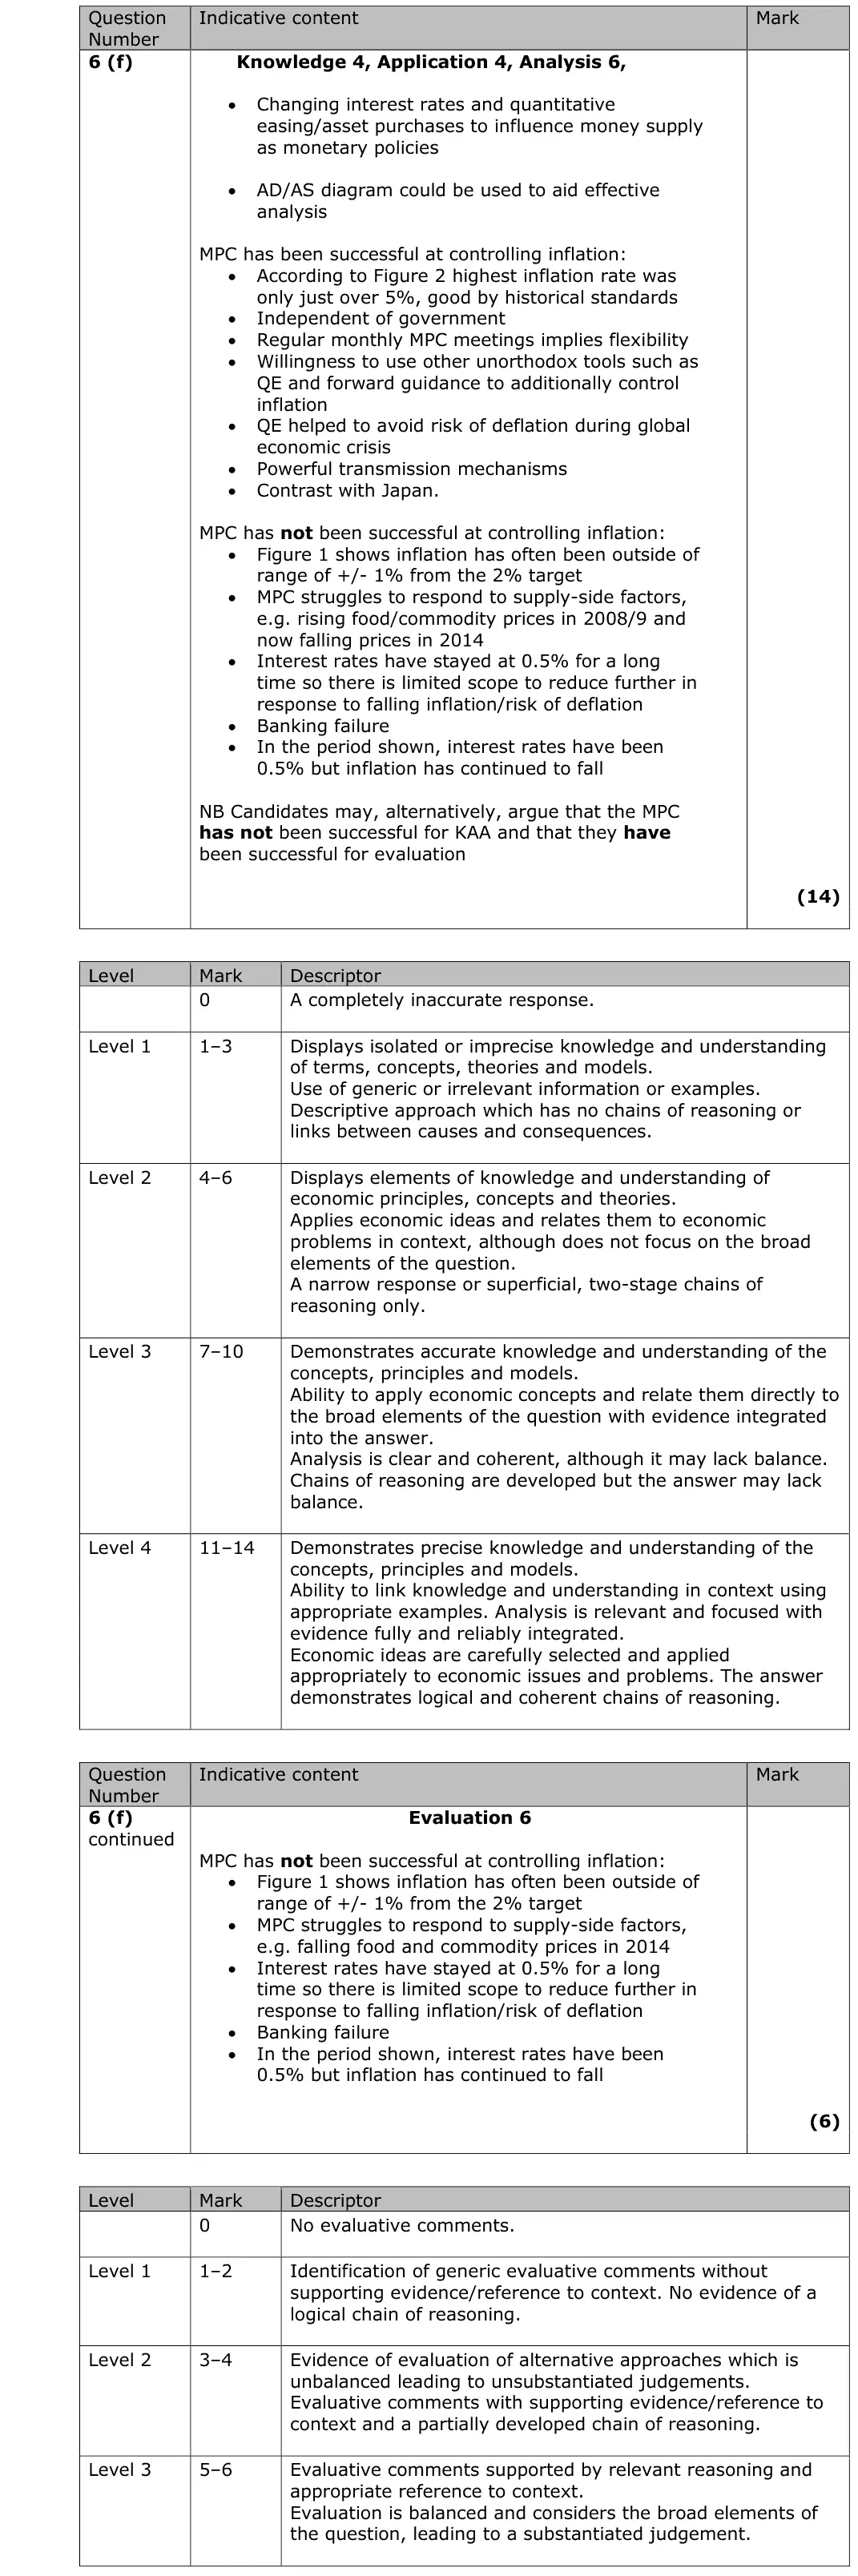
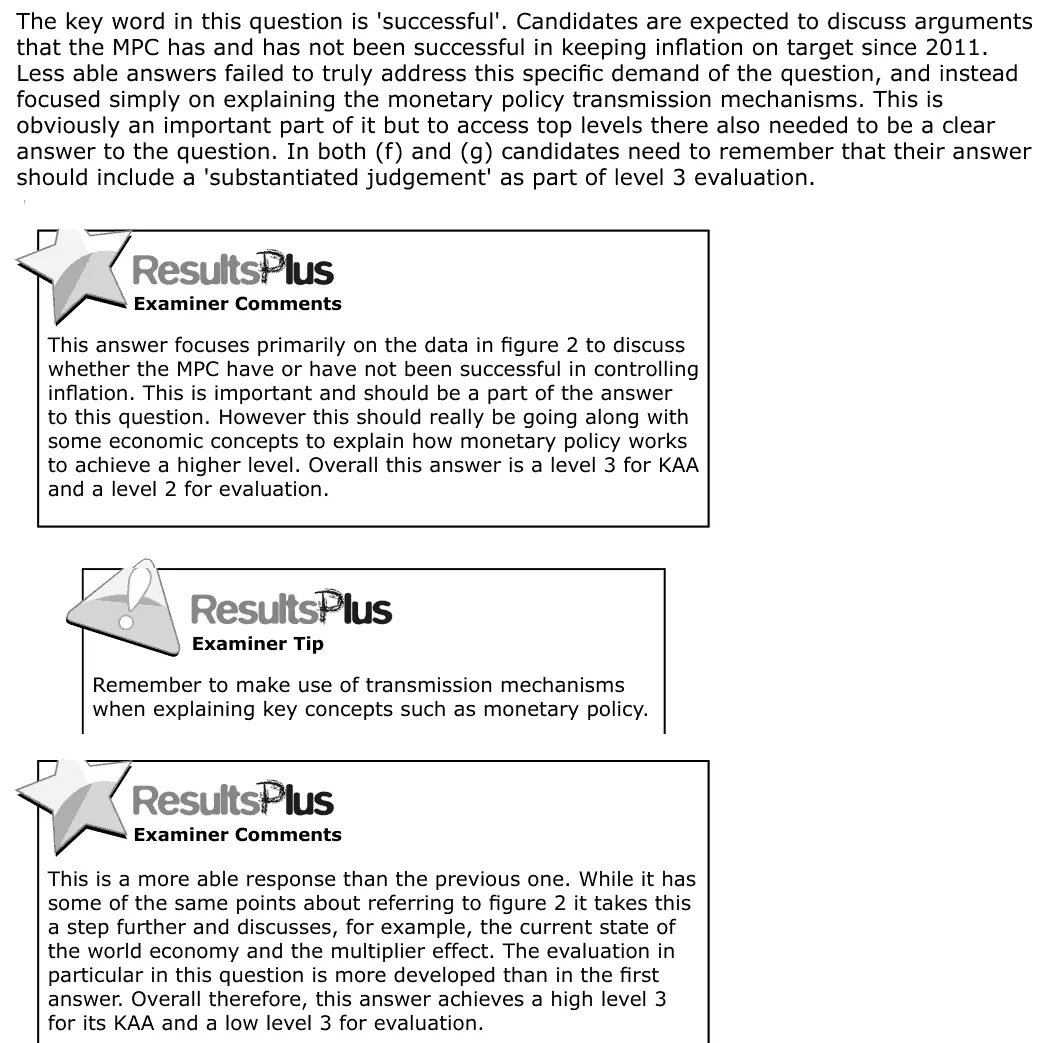
6(f) Demand-side policies: fiscal and monetary policy, Inflation 20AO1=4,AO2=4,AO3=6,AO4=6Essay
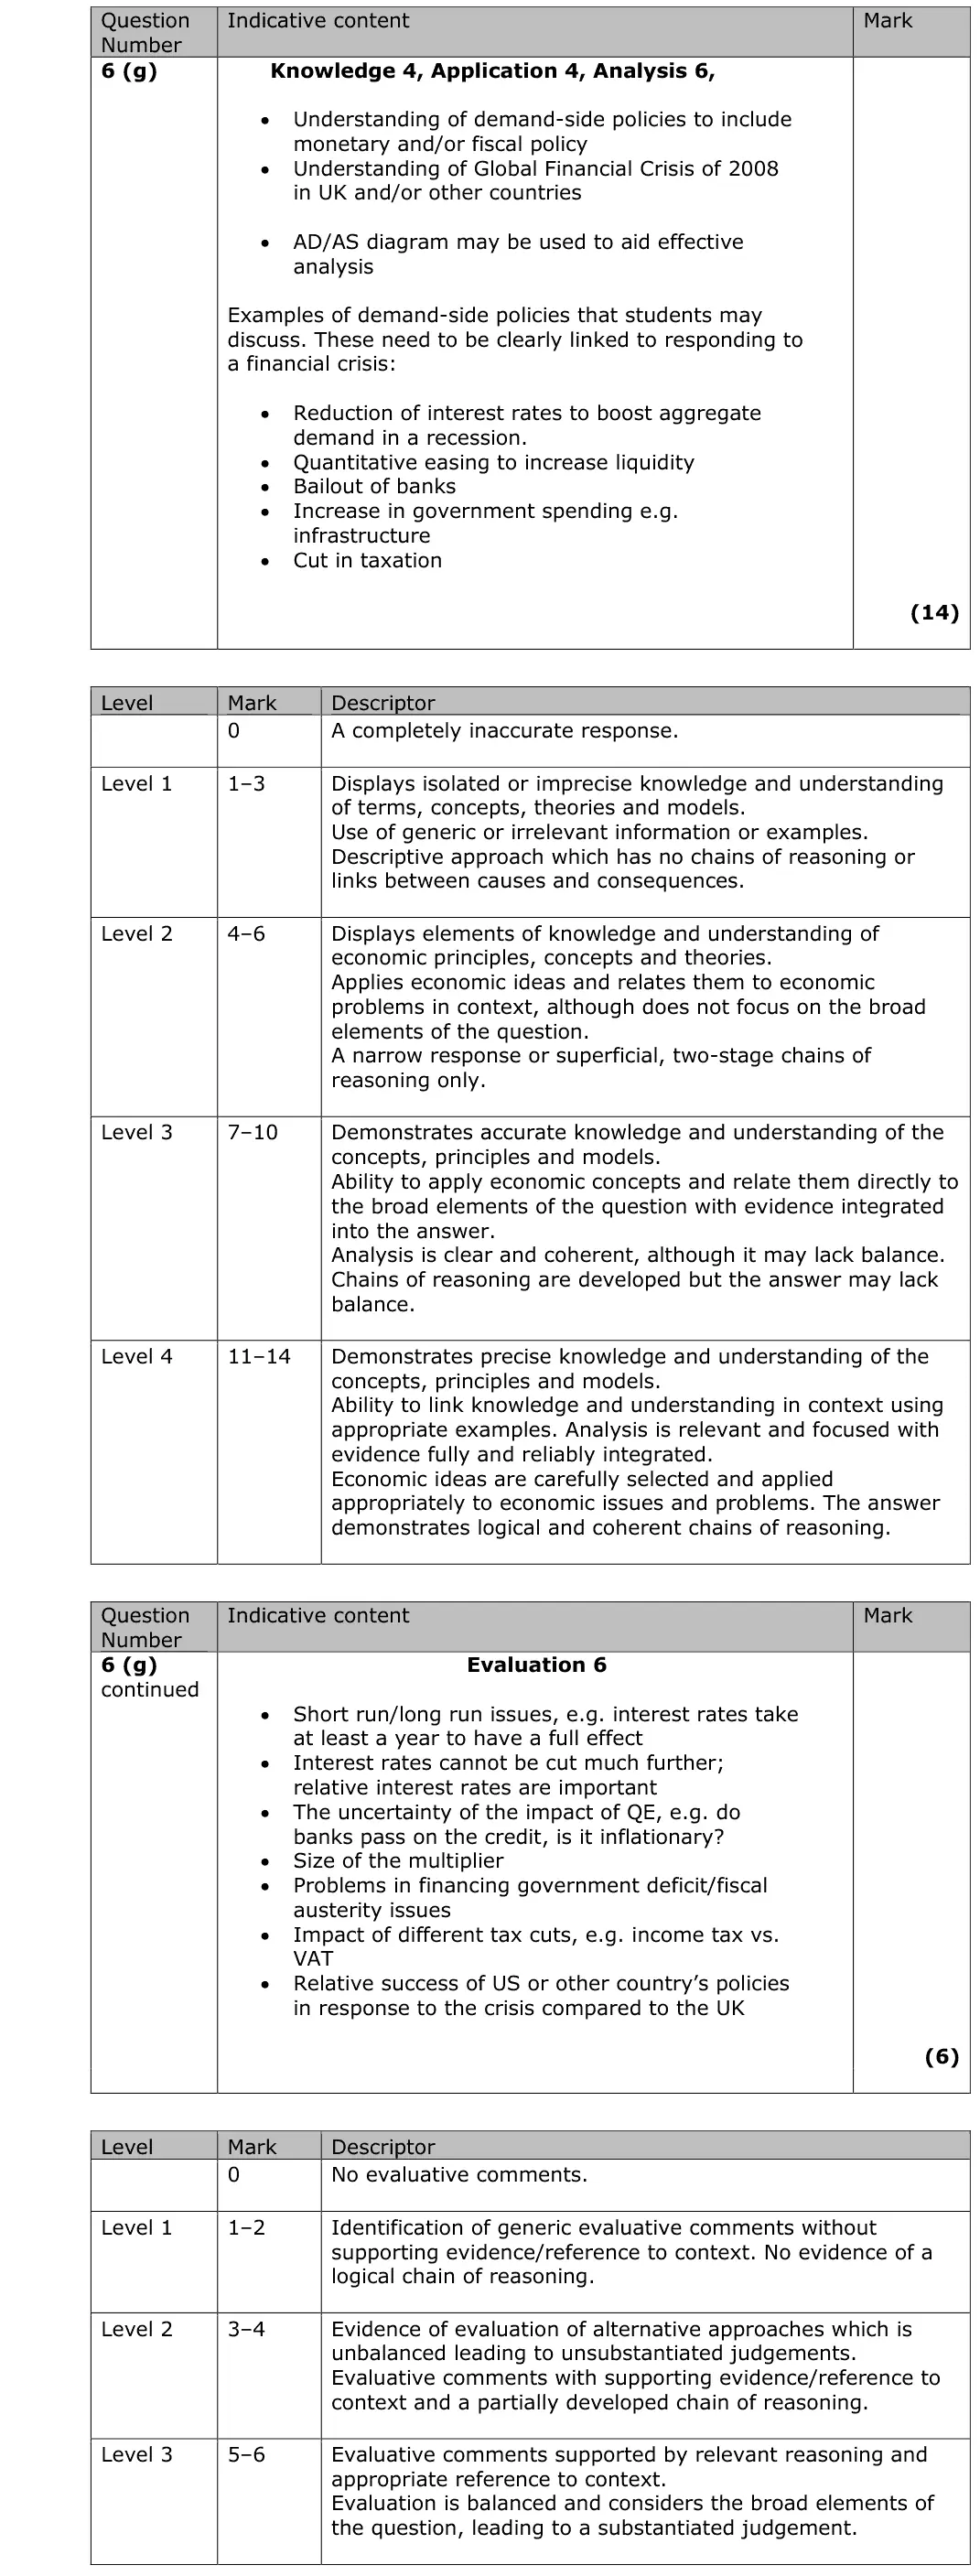
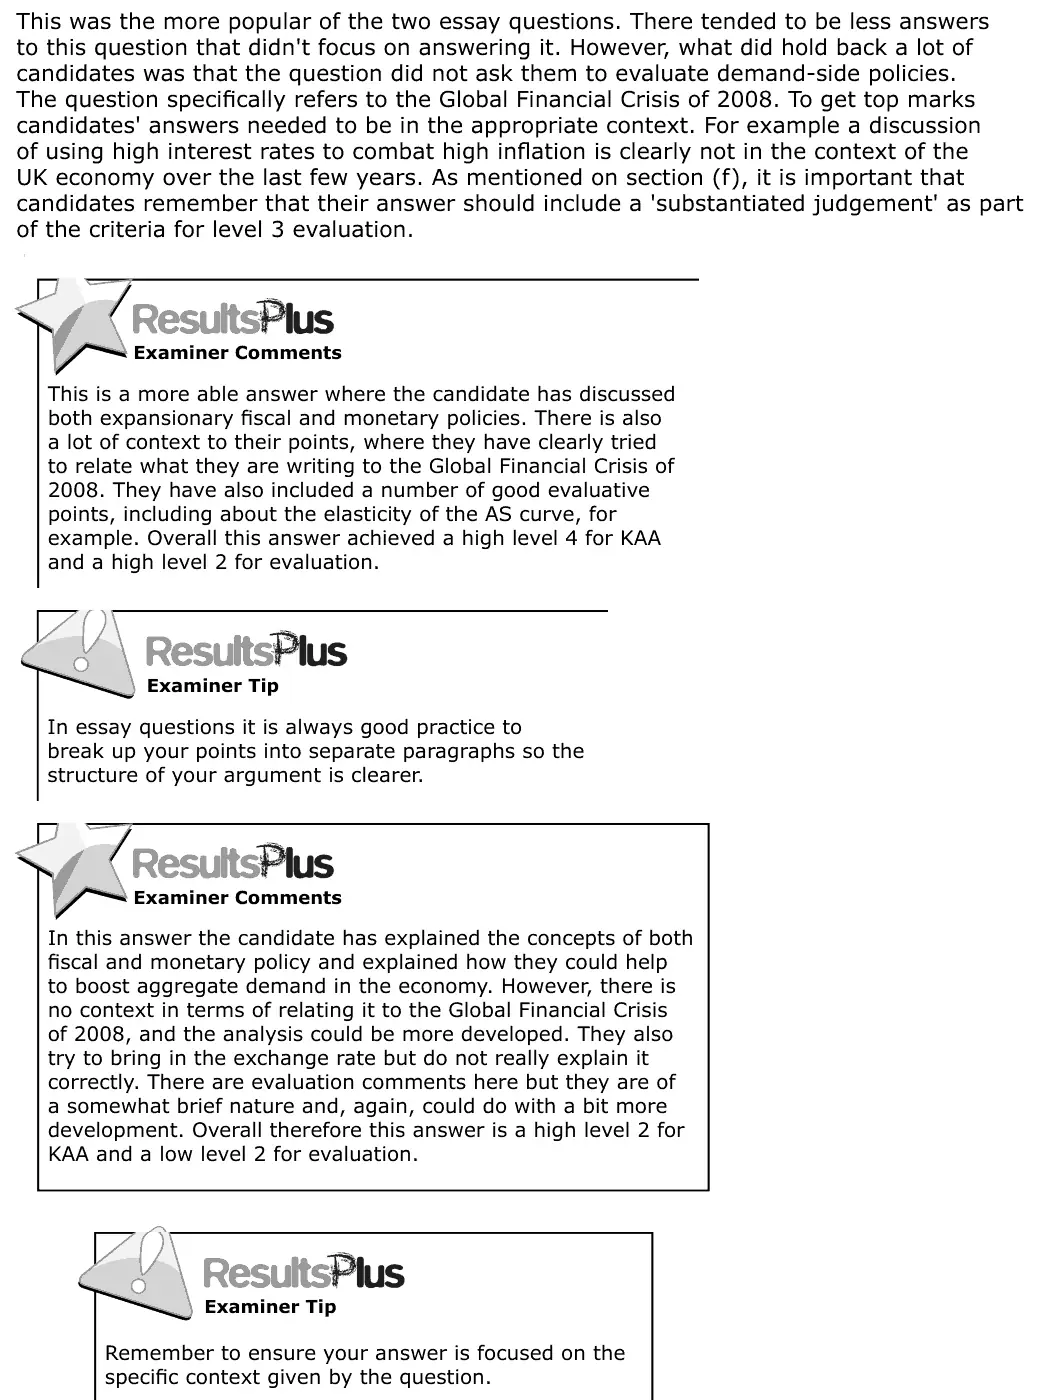
6(g) Demand-side policies: fiscal and monetary policy 20AO1=4,AO2=4,AO3=6,AO4=6Essay

The questions

1(a)1(b)1(c)2(a)2(b)2(c)3(a)3(b)3(c)4(a)4(b)5(a)5(b)6(a)6(b)6(c)6(d)6(e)6(f)6(g)
June 2016 · AS Paper 2 · Q1(a) 1 mark AO1=1 Definition national income and the multiplier
(a) Define the term ‘national income’. (1)
June 2016 · AS Paper 2 · Q1(b) 1 mark Multiple choice national income and the multiplier
(b) Which one of the following is an injection into the circular flow of income? (1) A Taxation B Imports C Investment D Saving
June 2016 · AS Paper 2 · Q1(c) 2 marks AO1=2 Definition national income and the multiplier
(c) Define the term ‘circular flow of income’. (2)
June 2016 · AS Paper 2 · Q2(a) 2 marks AO1=2 Definition Hard measuring economic growth
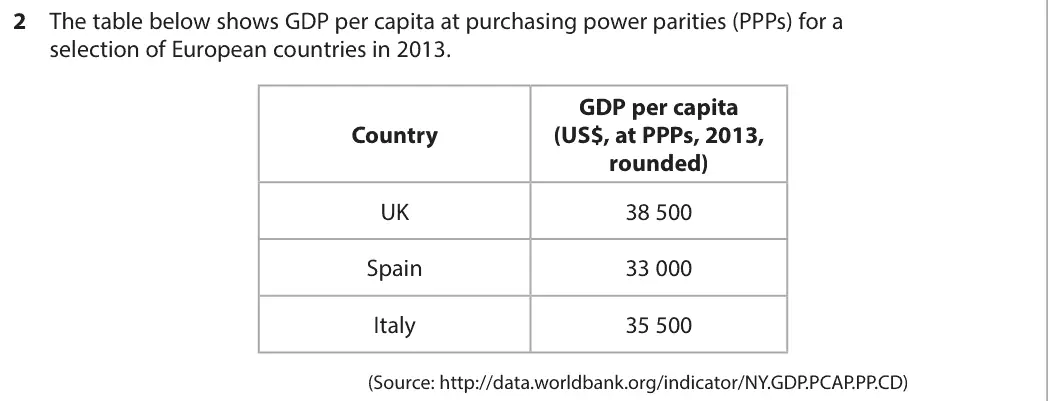
Data and extracts for question 22 The table below shows GDP per capita at purchasing power parities (PPPs) for a selection of European countries in 2013. GDP per capita Country (US$, at PPPs, 2013, rounded) UK 38 500 Spain 33 000 Italy 35 500 (Source: http://data.worldbank.org/indicator/NY.GDP.PCAP.PP.CD)
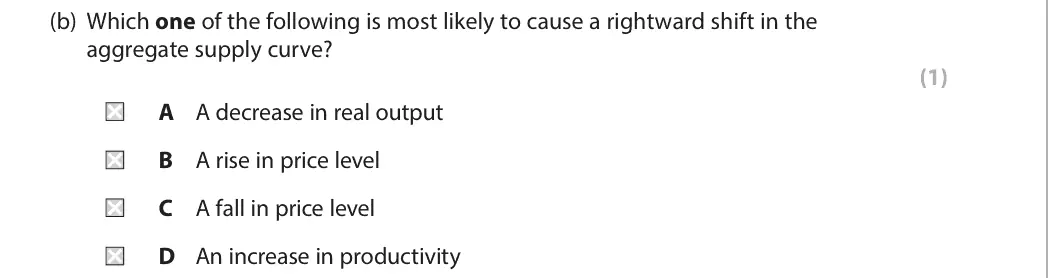
(a) Define the term ‘purchasing power parities’. (2)
June 2016 · AS Paper 2 · Q2(b) 1 mark Multiple choice measuring economic growth
Data and extracts for question 22 The table below shows GDP per capita at purchasing power parities (PPPs) for a selection of European countries in 2013. GDP per capita Country (US$, at PPPs, 2013, rounded) UK 38 500 Spain 33 000 Italy 35 500 (Source: http://data.worldbank.org/indicator/NY.GDP.PCAP.PP.CD)
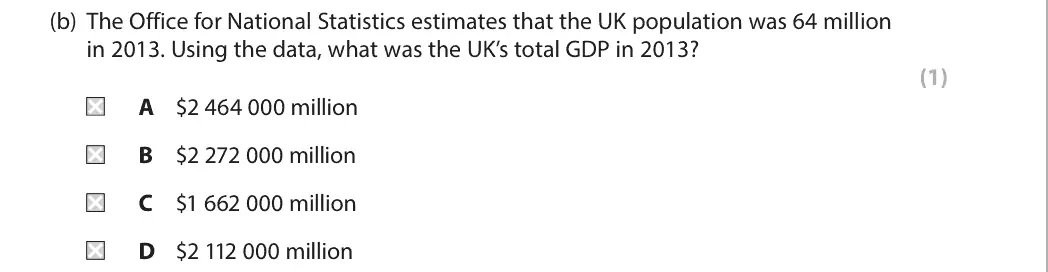
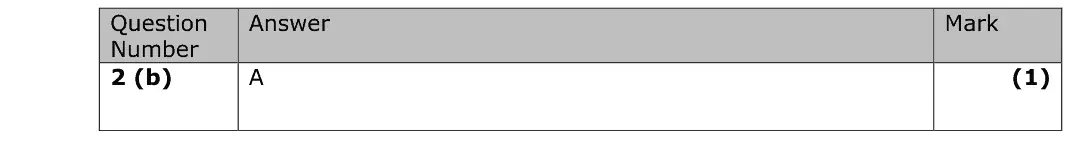
(b) The Office for National Statistics estimates that the UK population was 64 million in 2013. Using the data, what was the UK’s total GDP in 2013? (1) A $2 464 000 million B $2 272 000 million C $1 662 000 million D $2 112 000 million
June 2016 · AS Paper 2 · Q2(c) 1 mark AO1=1 Diagram economic growth and the trade cyclenational income and the multiplier
Data and extracts for question 22 The table below shows GDP per capita at purchasing power parities (PPPs) for a selection of European countries in 2013. GDP per capita Country (US$, at PPPs, 2013, rounded) UK 38 500 Spain 33 000 Italy 35 500 (Source: http://data.worldbank.org/indicator/NY.GDP.PCAP.PP.CD)
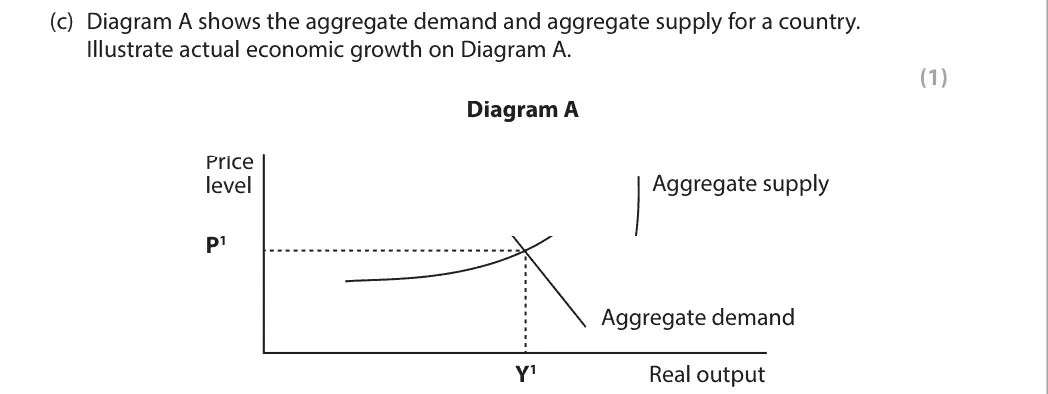
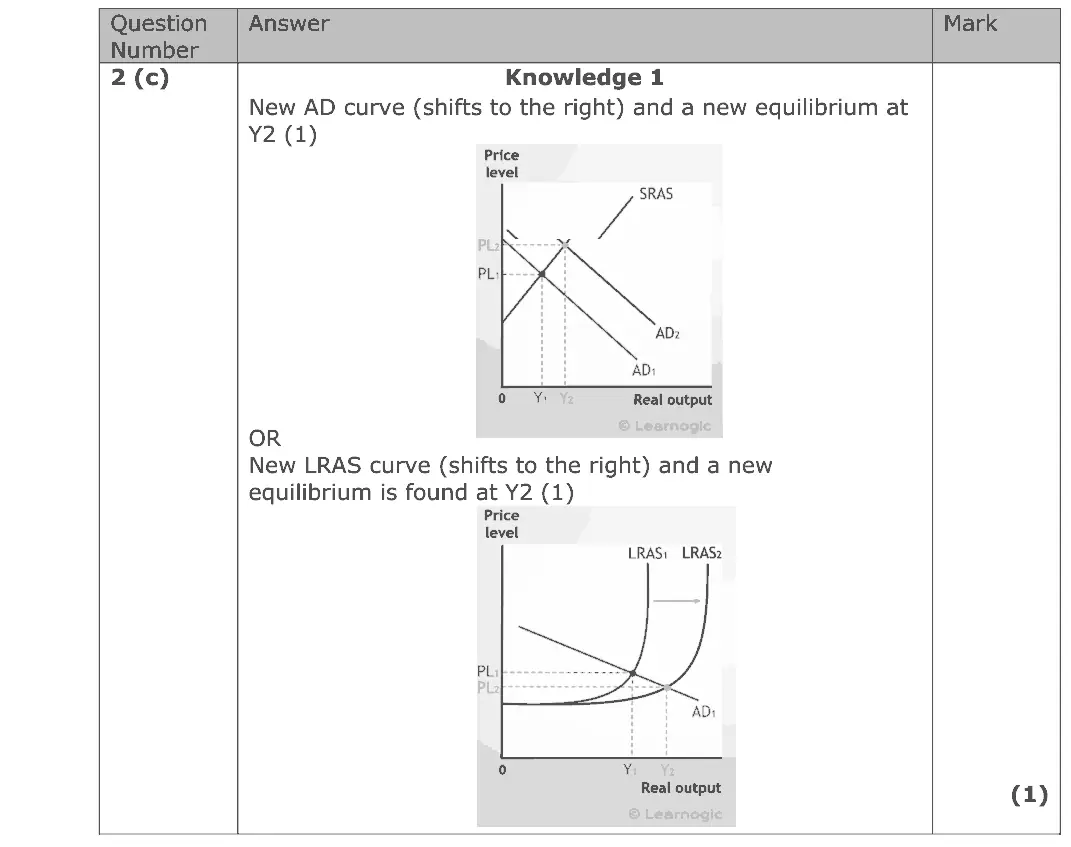
(c) Diagram A shows the aggregate demand and aggregate supply for a country. Illustrate actual economic growth on Diagram A. (1) Diagram A Price Aggregate supply level P1 Aggregate demand Y1 Real output
June 2016 · AS Paper 2 · Q3(a) 1 mark AO1=1 Definition unemployment
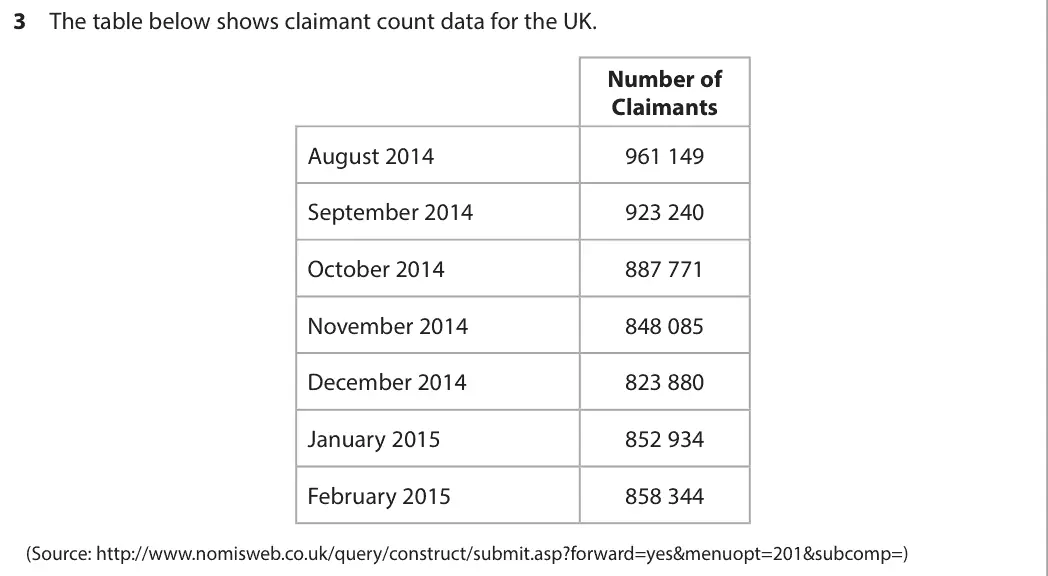
Data and extracts for question 33 The table below shows claimant count data for the UK. Number of Claimants August 2014 961 149 September 2014 923 240 October 2014 887 771 November 2014 848 085 December 2014 823 880 January 2015 852 934 February 2015 858 344 (Source: http://www.nomisweb.co.uk/query/construct/submit.asp?forward=yes&menuopt=201&subcomp=)
(a) Define the term ‘claimant count’. (1)
June 2016 · AS Paper 2 · Q3(b) 2 marks AO2=2 Calculation unemployment
Data and extracts for question 33 The table below shows claimant count data for the UK. Number of Claimants August 2014 961 149 September 2014 923 240 October 2014 887 771 November 2014 848 085 December 2014 823 880 January 2015 852 934 February 2015 858 344 (Source: http://www.nomisweb.co.uk/query/construct/submit.asp?forward=yes&menuopt=201&subcomp=)
(b) Calculate the percentage change in the claimant count from August 2014 to February 2015. (2)
June 2016 · AS Paper 2 · Q3(c) 1 mark Multiple choice unemployment
Data and extracts for question 33 The table below shows claimant count data for the UK. Number of Claimants August 2014 961 149 September 2014 923 240 October 2014 887 771 November 2014 848 085 December 2014 823 880 January 2015 852 934 February 2015 858 344 (Source: http://www.nomisweb.co.uk/query/construct/submit.asp?forward=yes&menuopt=201&subcomp=)
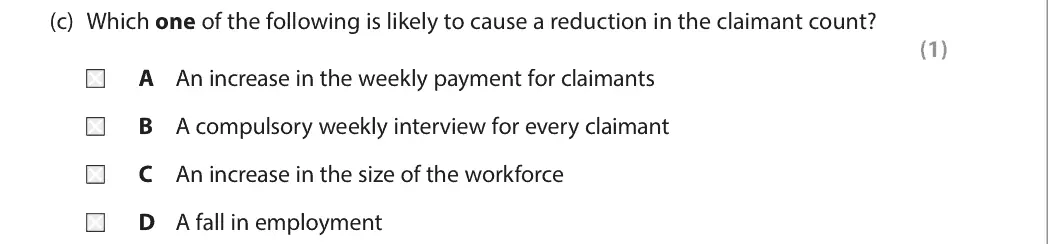
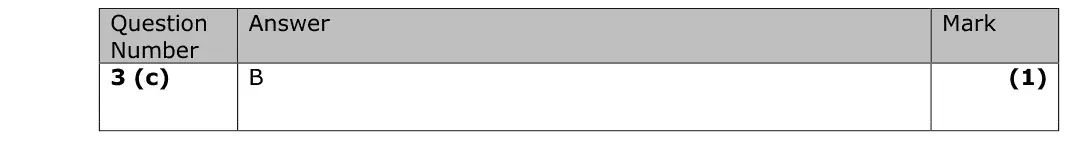
(c) Which one of the following is likely to cause a reduction in the claimant count? (1) A An increase in the weekly payment for claimants B A compulsory weekly interview for every claimant C An increase in the size of the workforce D A fall in employment
June 2016 · AS Paper 2 · Q4(a) 1 mark Multiple choice balance of payments
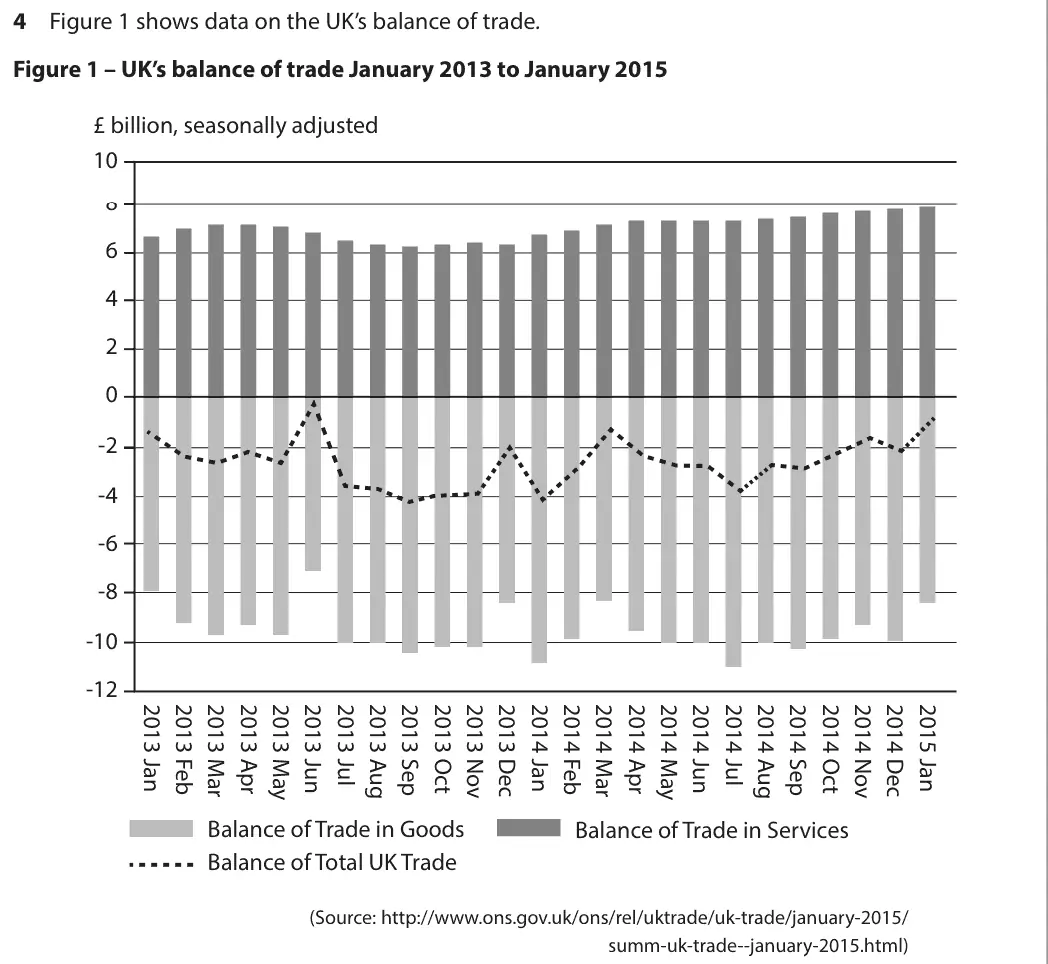
Data and extracts for question 44 Figure 1 shows data on the UK’s balance of trade. Figure 1 – UK’s balance of trade January 2013 to January 2015 £ billion, seasonally adjusted 10 8 6 4 2 0 -2 -4 -6 -8 -10 -12 Balance of Trade in Goods Balance of Trade in Services Balance of Total UK Trade (Source: http://www.ons.gov.uk/ons/rel/uktrade/uk-trade/january-2015/ summ-uk-trade--january-2015.html)
(a) Which one of the following can be inferred from Figure 1 in the period shown? (1) A The total UK trade deficit was the largest in June 2013 B The trade in goods was always in surplus between January 2013 and January 2015 C The total UK trade deficit was the smallest in January 2014 D The trade in goods deficit was the smallest in June 2013
June 2016 · AS Paper 2 · Q4(b) 3 marks AO1=1, AO2=1, AO3=1 Short answer balance of paymentsaggregate demand
Data and extracts for question 44 Figure 1 shows data on the UK’s balance of trade. Figure 1 – UK’s balance of trade January 2013 to January 2015 £ billion, seasonally adjusted 10 8 6 4 2 0 -2 -4 -6 -8 -10 -12 Balance of Trade in Goods Balance of Trade in Services Balance of Total UK Trade (Source: http://www.ons.gov.uk/ons/rel/uktrade/uk-trade/january-2015/ summ-uk-trade--january-2015.html)
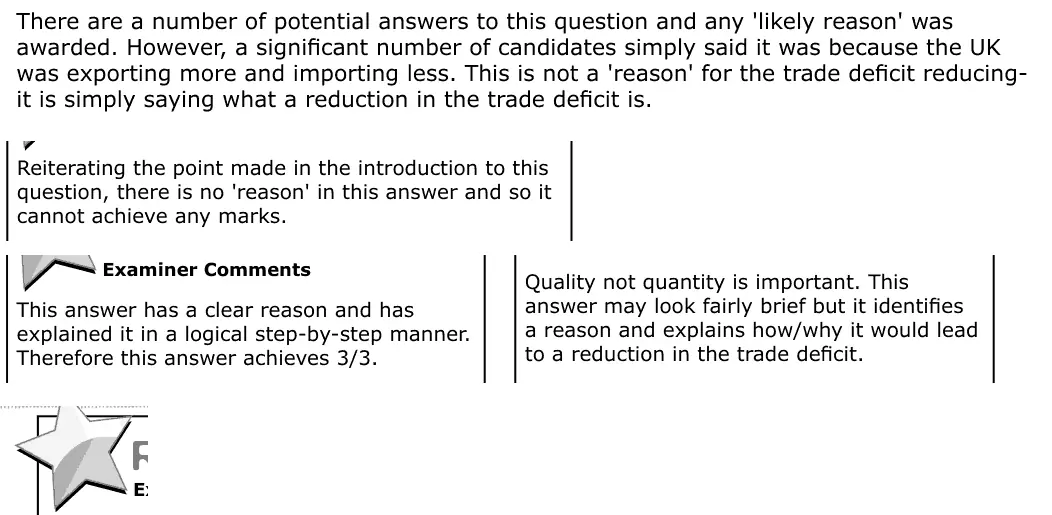
(b) Explain one likely reason for the reduction in the total UK trade deficit in January 2015. (3)
June 2016 · AS Paper 2 · Q5(a) 3 marks AO1=1, AO2=2 Calculation national income and the multiplier
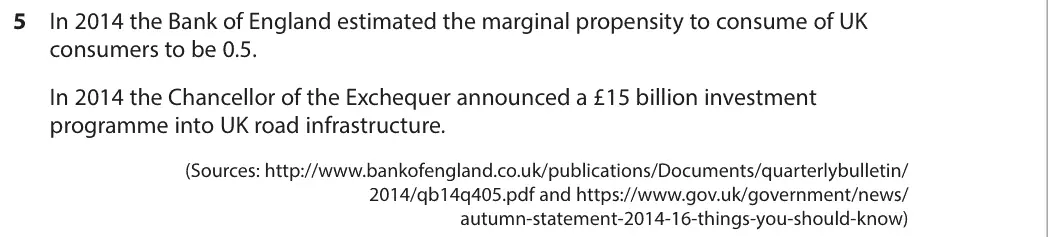
Data and extracts for question 55 In 2014 the Bank of England estimated the marginal propensity to consume of UK consumers to be 0.5. In 2014 the Chancellor of the Exchequer announced a £15 billion investment programme into UK road infrastructure. (Sources: http://www.bankofengland.co.uk/publications/Documents/quarterlybulletin/ 2014/qb14q405.pdf and https://www.gov.uk/government/news/ autumn-statement-2014-16-things-you-should-know)
(a) Using the information above, calculate the total increase in national income, resulting from the £15 billion investment. (3)
June 2016 · AS Paper 2 · Q5(b) 1 mark Multiple choice aggregate supply
Data and extracts for question 55 In 2014 the Bank of England estimated the marginal propensity to consume of UK consumers to be 0.5. In 2014 the Chancellor of the Exchequer announced a £15 billion investment programme into UK road infrastructure. (Sources: http://www.bankofengland.co.uk/publications/Documents/quarterlybulletin/ 2014/qb14q405.pdf and https://www.gov.uk/government/news/ autumn-statement-2014-16-things-you-should-know)
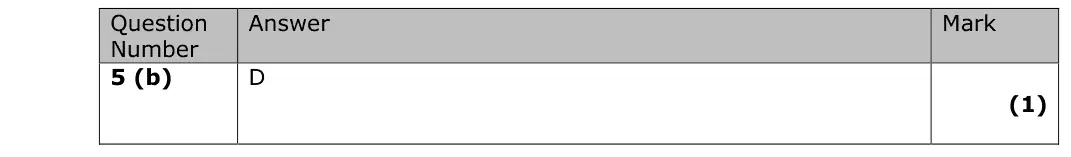
(b) Which one of the following is most likely to cause a rightward shift in the aggregate supply curve? (1) A A decrease in real output B A rise in price level C A fall in price level D An increase in productivity
June 2016 · AS Paper 2 · Q6(a) 4 marks AO1=2, AO2=2 Short answer measuring economic growth
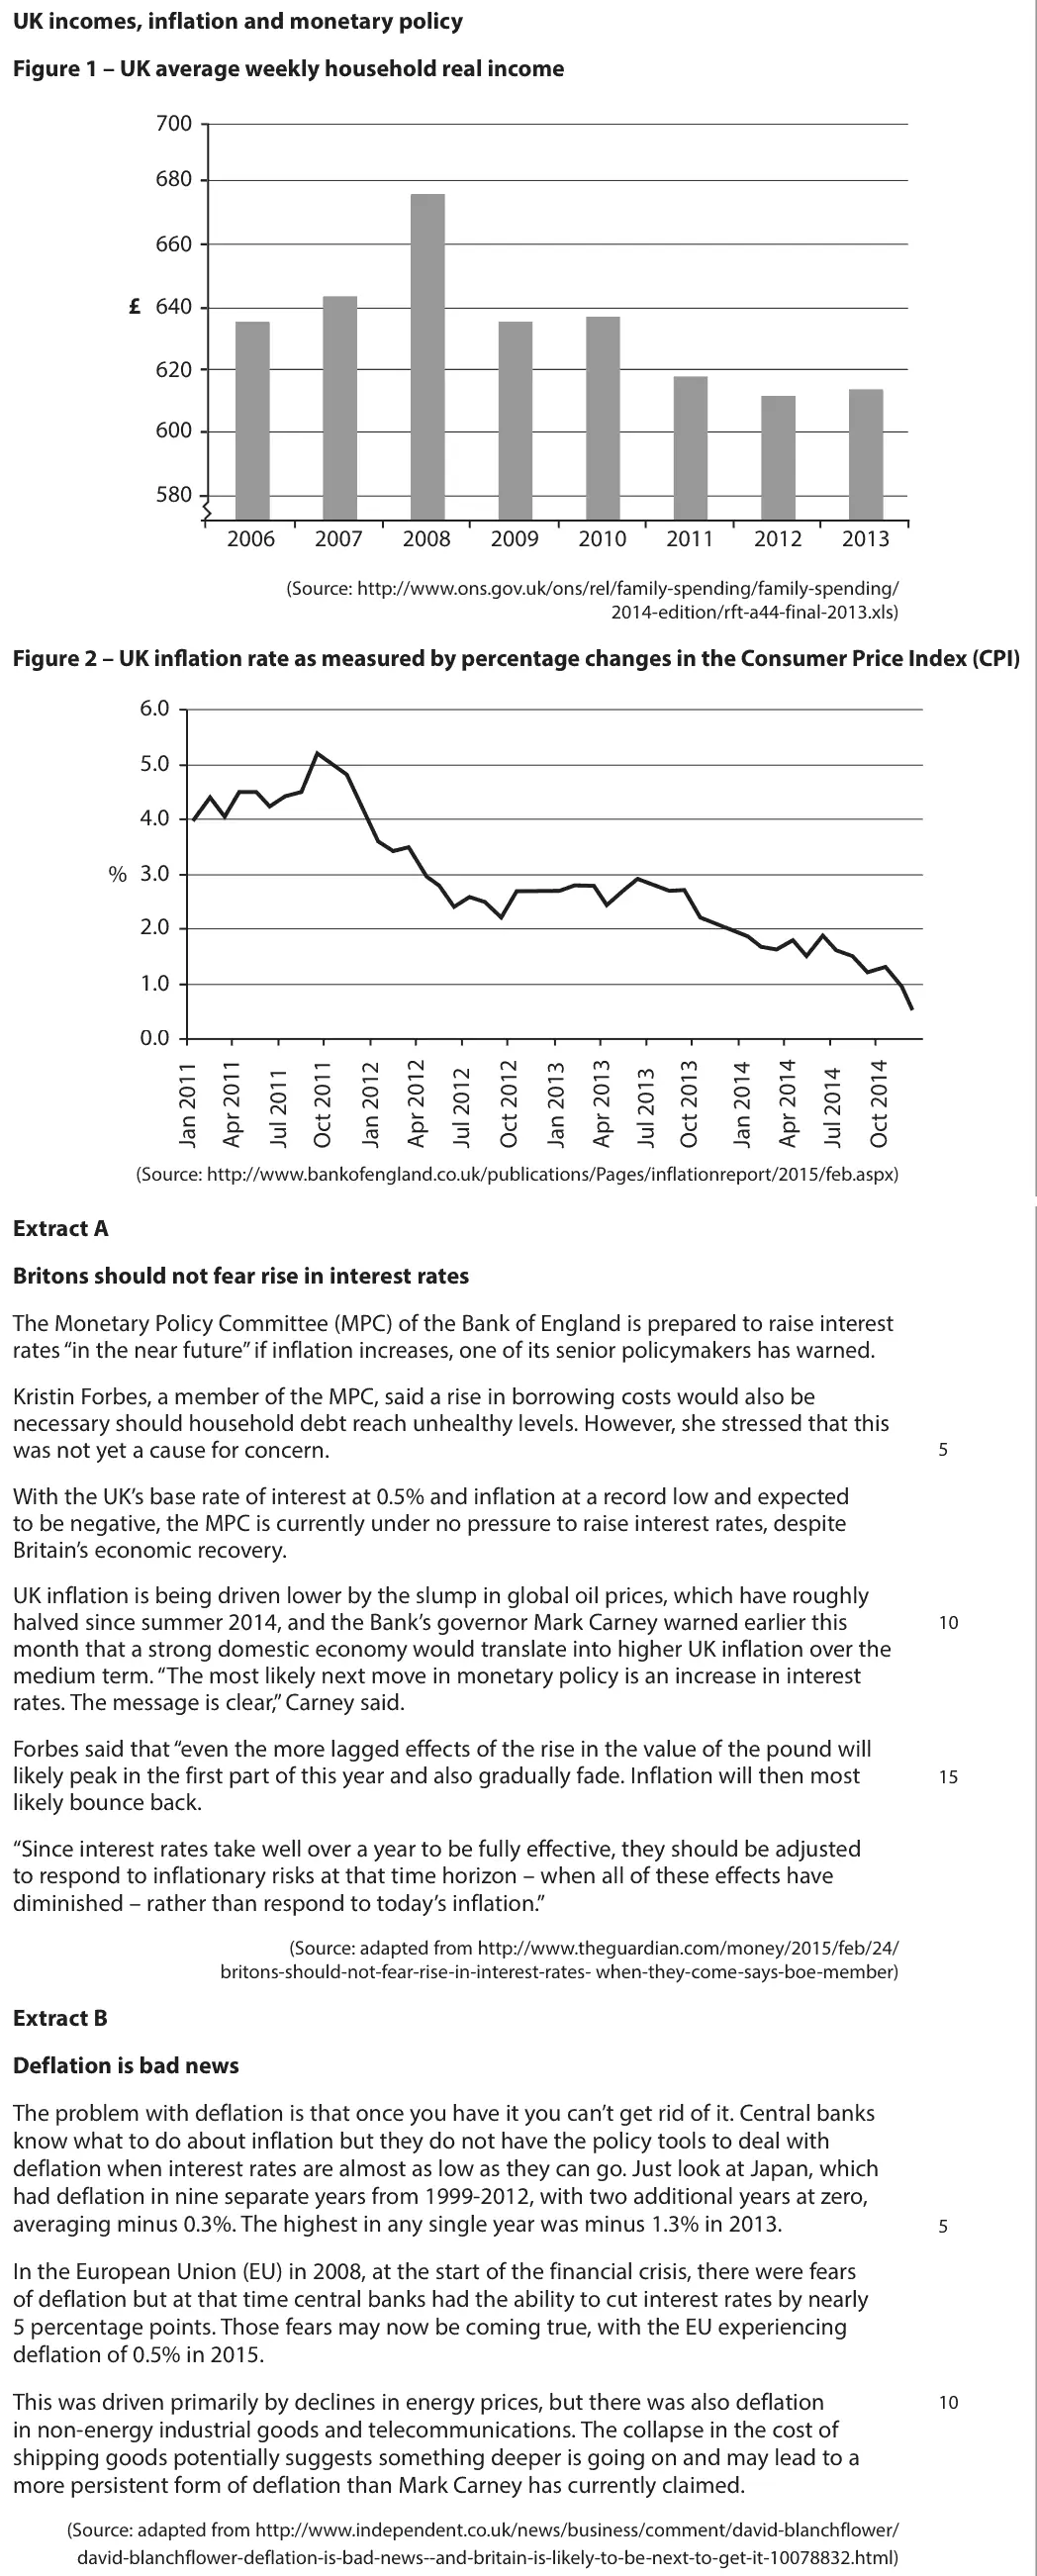
Data and extracts for question 6UK incomes, inflation and monetary policy Figure 1 – UK average weekly household real income 700 680 660 640 £ 620 600 580 2006 2007 2008 2009 2010 2011 2012 2013 (Source: http://www.ons.gov.uk/ons/rel/family-spending/family-spending/ 2014-edition/rft-a44-final-2013.xls) Figure 2 – UK inflation rate as measured by percentage changes in the Consumer Price Index (CPI) 6.0 5.0 4.0 % 3.0 2.0 1.0 0.0 (Source: http://www.bankofengland.co.uk/publications/Pages/inflationreport/2015/feb.aspx) Extract A Britons should not fear rise in interest rates The Monetary Policy Committee (MPC) of the Bank of England is prepared to raise interest rates “in the near future” if inflation increases, one of its senior policymakers has warned. Kristin Forbes, a member of the MPC, said a rise in borrowing costs would also be necessary should household debt reach unhealthy levels. However, she stressed that this was not yet a cause for concern. 5 With the UK’s base rate of interest at 0.5% and inflation at a record low and expected to be negative, the MPC is currently under no pressure to raise interest rates, despite Britain’s economic recovery. UK inflation is being driven lower by the slump in global oil prices, which have roughly halved since summer 2014, and the Bank’s governor Mark Carney warned earlier this 10 month that a strong domestic economy would translate into higher UK inflation over the medium term. “The most likely next move in monetary policy is an increase in interest rates. The message is clear,” Carney said. Forbes said that “even the more lagged effects of the rise in the value of the pound will likely peak in the first part of this year and also gradually fade. Inflation will then most 15 likely bounce back. “Since interest rates take well over a year to be fully effective, they should be adjusted to respond to inflationary risks at that time horizon – when all of these effects have diminished – rather than respond to today’s inflation.” (Source: adapted from http://www.theguardian.com/money/2015/feb/24/ britons-should-not-fear-rise-in-interest-rates- when-they-come-says-boe-member) Extract B Deflation is bad news The problem with deflation is that once you have it you can’t get rid of it. Central banks know what to do about inflation but they do not have the policy tools to deal with deflation when interest rates are almost as low as they can go. Just look at Japan, which had deflation in nine separate years from 1999-2012, with two additional years at zero, averaging minus 0.3%. The highest in any single year was minus 1.3% in 2013. 5 In the European Union (EU) in 2008, at the start of the financial crisis, there were fears of deflation but at that time central banks had the ability to cut interest rates by nearly 5 percentage points. Those fears may now be coming true, with the EU experiencing deflation of 0.5% in 2015. This was driven primarily by declines in energy prices, but there was also deflation 10 in non-energy industrial goods and telecommunications. The collapse in the cost of shipping goods potentially suggests something deeper is going on and may lead to a more persistent form of deflation than Mark Carney has currently claimed. (Source: adapted from http://www.independent.co.uk/news/business/comment/david-blanchflower/ david-blanchflower-deflation-is-bad-news--and-britain-is-likely-to-be-next-to-get-it-10078832.html)
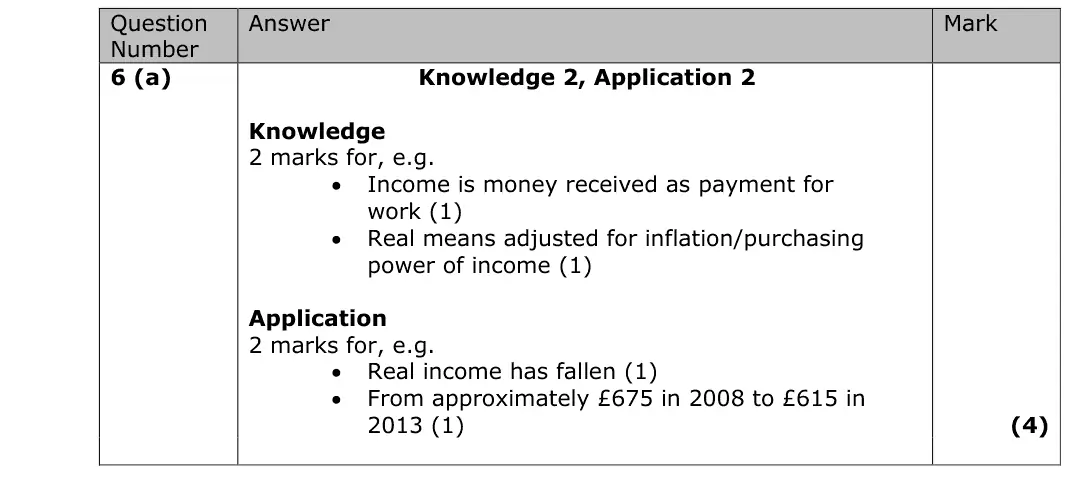
(a) With reference to Figure 1, explain the term ‘real income’. (4)
June 2016 · AS Paper 2 · Q6(b) 10 marks AO1=2, AO2=2, AO3=2, AO4=4 10-mark response aggregate demand
Data and extracts for question 6UK incomes, inflation and monetary policy Figure 1 – UK average weekly household real income 700 680 660 640 £ 620 600 580 2006 2007 2008 2009 2010 2011 2012 2013 (Source: http://www.ons.gov.uk/ons/rel/family-spending/family-spending/ 2014-edition/rft-a44-final-2013.xls) Figure 2 – UK inflation rate as measured by percentage changes in the Consumer Price Index (CPI) 6.0 5.0 4.0 % 3.0 2.0 1.0 0.0 (Source: http://www.bankofengland.co.uk/publications/Pages/inflationreport/2015/feb.aspx) Extract A Britons should not fear rise in interest rates The Monetary Policy Committee (MPC) of the Bank of England is prepared to raise interest rates “in the near future” if inflation increases, one of its senior policymakers has warned. Kristin Forbes, a member of the MPC, said a rise in borrowing costs would also be necessary should household debt reach unhealthy levels. However, she stressed that this was not yet a cause for concern. 5 With the UK’s base rate of interest at 0.5% and inflation at a record low and expected to be negative, the MPC is currently under no pressure to raise interest rates, despite Britain’s economic recovery. UK inflation is being driven lower by the slump in global oil prices, which have roughly halved since summer 2014, and the Bank’s governor Mark Carney warned earlier this 10 month that a strong domestic economy would translate into higher UK inflation over the medium term. “The most likely next move in monetary policy is an increase in interest rates. The message is clear,” Carney said. Forbes said that “even the more lagged effects of the rise in the value of the pound will likely peak in the first part of this year and also gradually fade. Inflation will then most 15 likely bounce back. “Since interest rates take well over a year to be fully effective, they should be adjusted to respond to inflationary risks at that time horizon – when all of these effects have diminished – rather than respond to today’s inflation.” (Source: adapted from http://www.theguardian.com/money/2015/feb/24/ britons-should-not-fear-rise-in-interest-rates- when-they-come-says-boe-member) Extract B Deflation is bad news The problem with deflation is that once you have it you can’t get rid of it. Central banks know what to do about inflation but they do not have the policy tools to deal with deflation when interest rates are almost as low as they can go. Just look at Japan, which had deflation in nine separate years from 1999-2012, with two additional years at zero, averaging minus 0.3%. The highest in any single year was minus 1.3% in 2013. 5 In the European Union (EU) in 2008, at the start of the financial crisis, there were fears of deflation but at that time central banks had the ability to cut interest rates by nearly 5 percentage points. Those fears may now be coming true, with the EU experiencing deflation of 0.5% in 2015. This was driven primarily by declines in energy prices, but there was also deflation 10 in non-energy industrial goods and telecommunications. The collapse in the cost of shipping goods potentially suggests something deeper is going on and may lead to a more persistent form of deflation than Mark Carney has currently claimed. (Source: adapted from http://www.independent.co.uk/news/business/comment/david-blanchflower/ david-blanchflower-deflation-is-bad-news--and-britain-is-likely-to-be-next-to-get-it-10078832.html)
(b) Assess the likely impact of falling real incomes on UK consumers. (10)
June 2016 · AS Paper 2 · Q6(c) 5 marks AO1=1, AO2=2, AO3=2 Short answer aggregate demand
Data and extracts for question 6UK incomes, inflation and monetary policy Figure 1 – UK average weekly household real income 700 680 660 640 £ 620 600 580 2006 2007 2008 2009 2010 2011 2012 2013 (Source: http://www.ons.gov.uk/ons/rel/family-spending/family-spending/ 2014-edition/rft-a44-final-2013.xls) Figure 2 – UK inflation rate as measured by percentage changes in the Consumer Price Index (CPI) 6.0 5.0 4.0 % 3.0 2.0 1.0 0.0 (Source: http://www.bankofengland.co.uk/publications/Pages/inflationreport/2015/feb.aspx) Extract A Britons should not fear rise in interest rates The Monetary Policy Committee (MPC) of the Bank of England is prepared to raise interest rates “in the near future” if inflation increases, one of its senior policymakers has warned. Kristin Forbes, a member of the MPC, said a rise in borrowing costs would also be necessary should household debt reach unhealthy levels. However, she stressed that this was not yet a cause for concern. 5 With the UK’s base rate of interest at 0.5% and inflation at a record low and expected to be negative, the MPC is currently under no pressure to raise interest rates, despite Britain’s economic recovery. UK inflation is being driven lower by the slump in global oil prices, which have roughly halved since summer 2014, and the Bank’s governor Mark Carney warned earlier this 10 month that a strong domestic economy would translate into higher UK inflation over the medium term. “The most likely next move in monetary policy is an increase in interest rates. The message is clear,” Carney said. Forbes said that “even the more lagged effects of the rise in the value of the pound will likely peak in the first part of this year and also gradually fade. Inflation will then most 15 likely bounce back. “Since interest rates take well over a year to be fully effective, they should be adjusted to respond to inflationary risks at that time horizon – when all of these effects have diminished – rather than respond to today’s inflation.” (Source: adapted from http://www.theguardian.com/money/2015/feb/24/ britons-should-not-fear-rise-in-interest-rates- when-they-come-says-boe-member) Extract B Deflation is bad news The problem with deflation is that once you have it you can’t get rid of it. Central banks know what to do about inflation but they do not have the policy tools to deal with deflation when interest rates are almost as low as they can go. Just look at Japan, which had deflation in nine separate years from 1999-2012, with two additional years at zero, averaging minus 0.3%. The highest in any single year was minus 1.3% in 2013. 5 In the European Union (EU) in 2008, at the start of the financial crisis, there were fears of deflation but at that time central banks had the ability to cut interest rates by nearly 5 percentage points. Those fears may now be coming true, with the EU experiencing deflation of 0.5% in 2015. This was driven primarily by declines in energy prices, but there was also deflation 10 in non-energy industrial goods and telecommunications. The collapse in the cost of shipping goods potentially suggests something deeper is going on and may lead to a more persistent form of deflation than Mark Carney has currently claimed. (Source: adapted from http://www.independent.co.uk/news/business/comment/david-blanchflower/ david-blanchflower-deflation-is-bad-news--and-britain-is-likely-to-be-next-to-get-it-10078832.html)
(c) With reference to Extract A, explain the likely effect of a rise in the value of the pound on aggregate demand. (5)
June 2016 · AS Paper 2 · Q6(d) 6 marks AO1=2, AO2=2, AO3=2 Short answer inflation
Data and extracts for question 6UK incomes, inflation and monetary policy Figure 1 – UK average weekly household real income 700 680 660 640 £ 620 600 580 2006 2007 2008 2009 2010 2011 2012 2013 (Source: http://www.ons.gov.uk/ons/rel/family-spending/family-spending/ 2014-edition/rft-a44-final-2013.xls) Figure 2 – UK inflation rate as measured by percentage changes in the Consumer Price Index (CPI) 6.0 5.0 4.0 % 3.0 2.0 1.0 0.0 (Source: http://www.bankofengland.co.uk/publications/Pages/inflationreport/2015/feb.aspx) Extract A Britons should not fear rise in interest rates The Monetary Policy Committee (MPC) of the Bank of England is prepared to raise interest rates “in the near future” if inflation increases, one of its senior policymakers has warned. Kristin Forbes, a member of the MPC, said a rise in borrowing costs would also be necessary should household debt reach unhealthy levels. However, she stressed that this was not yet a cause for concern. 5 With the UK’s base rate of interest at 0.5% and inflation at a record low and expected to be negative, the MPC is currently under no pressure to raise interest rates, despite Britain’s economic recovery. UK inflation is being driven lower by the slump in global oil prices, which have roughly halved since summer 2014, and the Bank’s governor Mark Carney warned earlier this 10 month that a strong domestic economy would translate into higher UK inflation over the medium term. “The most likely next move in monetary policy is an increase in interest rates. The message is clear,” Carney said. Forbes said that “even the more lagged effects of the rise in the value of the pound will likely peak in the first part of this year and also gradually fade. Inflation will then most 15 likely bounce back. “Since interest rates take well over a year to be fully effective, they should be adjusted to respond to inflationary risks at that time horizon – when all of these effects have diminished – rather than respond to today’s inflation.” (Source: adapted from http://www.theguardian.com/money/2015/feb/24/ britons-should-not-fear-rise-in-interest-rates- when-they-come-says-boe-member) Extract B Deflation is bad news The problem with deflation is that once you have it you can’t get rid of it. Central banks know what to do about inflation but they do not have the policy tools to deal with deflation when interest rates are almost as low as they can go. Just look at Japan, which had deflation in nine separate years from 1999-2012, with two additional years at zero, averaging minus 0.3%. The highest in any single year was minus 1.3% in 2013. 5 In the European Union (EU) in 2008, at the start of the financial crisis, there were fears of deflation but at that time central banks had the ability to cut interest rates by nearly 5 percentage points. Those fears may now be coming true, with the EU experiencing deflation of 0.5% in 2015. This was driven primarily by declines in energy prices, but there was also deflation 10 in non-energy industrial goods and telecommunications. The collapse in the cost of shipping goods potentially suggests something deeper is going on and may lead to a more persistent form of deflation than Mark Carney has currently claimed. (Source: adapted from http://www.independent.co.uk/news/business/comment/david-blanchflower/ david-blanchflower-deflation-is-bad-news--and-britain-is-likely-to-be-next-to-get-it-10078832.html)
(d) With reference to the data, explain two likely reasons for the UK’s falling inflation rate. (6)
June 2016 · AS Paper 2 · Q6(e) 15 marks AO1=3, AO2=3, AO3=3, AO4=6 15-mark response inflationfiscal and monetary policy
Data and extracts for question 6UK incomes, inflation and monetary policy Figure 1 – UK average weekly household real income 700 680 660 640 £ 620 600 580 2006 2007 2008 2009 2010 2011 2012 2013 (Source: http://www.ons.gov.uk/ons/rel/family-spending/family-spending/ 2014-edition/rft-a44-final-2013.xls) Figure 2 – UK inflation rate as measured by percentage changes in the Consumer Price Index (CPI) 6.0 5.0 4.0 % 3.0 2.0 1.0 0.0 (Source: http://www.bankofengland.co.uk/publications/Pages/inflationreport/2015/feb.aspx) Extract A Britons should not fear rise in interest rates The Monetary Policy Committee (MPC) of the Bank of England is prepared to raise interest rates “in the near future” if inflation increases, one of its senior policymakers has warned. Kristin Forbes, a member of the MPC, said a rise in borrowing costs would also be necessary should household debt reach unhealthy levels. However, she stressed that this was not yet a cause for concern. 5 With the UK’s base rate of interest at 0.5% and inflation at a record low and expected to be negative, the MPC is currently under no pressure to raise interest rates, despite Britain’s economic recovery. UK inflation is being driven lower by the slump in global oil prices, which have roughly halved since summer 2014, and the Bank’s governor Mark Carney warned earlier this 10 month that a strong domestic economy would translate into higher UK inflation over the medium term. “The most likely next move in monetary policy is an increase in interest rates. The message is clear,” Carney said. Forbes said that “even the more lagged effects of the rise in the value of the pound will likely peak in the first part of this year and also gradually fade. Inflation will then most 15 likely bounce back. “Since interest rates take well over a year to be fully effective, they should be adjusted to respond to inflationary risks at that time horizon – when all of these effects have diminished – rather than respond to today’s inflation.” (Source: adapted from http://www.theguardian.com/money/2015/feb/24/ britons-should-not-fear-rise-in-interest-rates- when-they-come-says-boe-member) Extract B Deflation is bad news The problem with deflation is that once you have it you can’t get rid of it. Central banks know what to do about inflation but they do not have the policy tools to deal with deflation when interest rates are almost as low as they can go. Just look at Japan, which had deflation in nine separate years from 1999-2012, with two additional years at zero, averaging minus 0.3%. The highest in any single year was minus 1.3% in 2013. 5 In the European Union (EU) in 2008, at the start of the financial crisis, there were fears of deflation but at that time central banks had the ability to cut interest rates by nearly 5 percentage points. Those fears may now be coming true, with the EU experiencing deflation of 0.5% in 2015. This was driven primarily by declines in energy prices, but there was also deflation 10 in non-energy industrial goods and telecommunications. The collapse in the cost of shipping goods potentially suggests something deeper is going on and may lead to a more persistent form of deflation than Mark Carney has currently claimed. (Source: adapted from http://www.independent.co.uk/news/business/comment/david-blanchflower/ david-blanchflower-deflation-is-bad-news--and-britain-is-likely-to-be-next-to-get-it-10078832.html)
(e) With reference to Extracts A and B and your own knowledge, discuss whether the MPC should be concerned about the risk of deflation in the UK economy. (15)
June 2016 · AS Paper 2 · Q6(f) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or fiscal and monetary policyinflation
Data and extracts for question 6UK incomes, inflation and monetary policy Figure 1 – UK average weekly household real income 700 680 660 640 £ 620 600 580 2006 2007 2008 2009 2010 2011 2012 2013 (Source: http://www.ons.gov.uk/ons/rel/family-spending/family-spending/ 2014-edition/rft-a44-final-2013.xls) Figure 2 – UK inflation rate as measured by percentage changes in the Consumer Price Index (CPI) 6.0 5.0 4.0 % 3.0 2.0 1.0 0.0 (Source: http://www.bankofengland.co.uk/publications/Pages/inflationreport/2015/feb.aspx) Extract A Britons should not fear rise in interest rates The Monetary Policy Committee (MPC) of the Bank of England is prepared to raise interest rates “in the near future” if inflation increases, one of its senior policymakers has warned. Kristin Forbes, a member of the MPC, said a rise in borrowing costs would also be necessary should household debt reach unhealthy levels. However, she stressed that this was not yet a cause for concern. 5 With the UK’s base rate of interest at 0.5% and inflation at a record low and expected to be negative, the MPC is currently under no pressure to raise interest rates, despite Britain’s economic recovery. UK inflation is being driven lower by the slump in global oil prices, which have roughly halved since summer 2014, and the Bank’s governor Mark Carney warned earlier this 10 month that a strong domestic economy would translate into higher UK inflation over the medium term. “The most likely next move in monetary policy is an increase in interest rates. The message is clear,” Carney said. Forbes said that “even the more lagged effects of the rise in the value of the pound will likely peak in the first part of this year and also gradually fade. Inflation will then most 15 likely bounce back. “Since interest rates take well over a year to be fully effective, they should be adjusted to respond to inflationary risks at that time horizon – when all of these effects have diminished – rather than respond to today’s inflation.” (Source: adapted from http://www.theguardian.com/money/2015/feb/24/ britons-should-not-fear-rise-in-interest-rates- when-they-come-says-boe-member) Extract B Deflation is bad news The problem with deflation is that once you have it you can’t get rid of it. Central banks know what to do about inflation but they do not have the policy tools to deal with deflation when interest rates are almost as low as they can go. Just look at Japan, which had deflation in nine separate years from 1999-2012, with two additional years at zero, averaging minus 0.3%. The highest in any single year was minus 1.3% in 2013. 5 In the European Union (EU) in 2008, at the start of the financial crisis, there were fears of deflation but at that time central banks had the ability to cut interest rates by nearly 5 percentage points. Those fears may now be coming true, with the EU experiencing deflation of 0.5% in 2015. This was driven primarily by declines in energy prices, but there was also deflation 10 in non-energy industrial goods and telecommunications. The collapse in the cost of shipping goods potentially suggests something deeper is going on and may lead to a more persistent form of deflation than Mark Carney has currently claimed. (Source: adapted from http://www.independent.co.uk/news/business/comment/david-blanchflower/ david-blanchflower-deflation-is-bad-news--and-britain-is-likely-to-be-next-to-get-it-10078832.html)
(f) Evaluate whether the MPC has been successful in controlling the UK’s inflation rate since 2011. (20)
June 2016 · AS Paper 2 · Q6(g) 20 marks AO1=4, AO2=4, AO3=6, AO4=6 20-mark essay Either/or fiscal and monetary policy
Data and extracts for question 6UK incomes, inflation and monetary policy Figure 1 – UK average weekly household real income 700 680 660 640 £ 620 600 580 2006 2007 2008 2009 2010 2011 2012 2013 (Source: http://www.ons.gov.uk/ons/rel/family-spending/family-spending/ 2014-edition/rft-a44-final-2013.xls) Figure 2 – UK inflation rate as measured by percentage changes in the Consumer Price Index (CPI) 6.0 5.0 4.0 % 3.0 2.0 1.0 0.0 (Source: http://www.bankofengland.co.uk/publications/Pages/inflationreport/2015/feb.aspx) Extract A Britons should not fear rise in interest rates The Monetary Policy Committee (MPC) of the Bank of England is prepared to raise interest rates “in the near future” if inflation increases, one of its senior policymakers has warned. Kristin Forbes, a member of the MPC, said a rise in borrowing costs would also be necessary should household debt reach unhealthy levels. However, she stressed that this was not yet a cause for concern. 5 With the UK’s base rate of interest at 0.5% and inflation at a record low and expected to be negative, the MPC is currently under no pressure to raise interest rates, despite Britain’s economic recovery. UK inflation is being driven lower by the slump in global oil prices, which have roughly halved since summer 2014, and the Bank’s governor Mark Carney warned earlier this 10 month that a strong domestic economy would translate into higher UK inflation over the medium term. “The most likely next move in monetary policy is an increase in interest rates. The message is clear,” Carney said. Forbes said that “even the more lagged effects of the rise in the value of the pound will likely peak in the first part of this year and also gradually fade. Inflation will then most 15 likely bounce back. “Since interest rates take well over a year to be fully effective, they should be adjusted to respond to inflationary risks at that time horizon – when all of these effects have diminished – rather than respond to today’s inflation.” (Source: adapted from http://www.theguardian.com/money/2015/feb/24/ britons-should-not-fear-rise-in-interest-rates- when-they-come-says-boe-member) Extract B Deflation is bad news The problem with deflation is that once you have it you can’t get rid of it. Central banks know what to do about inflation but they do not have the policy tools to deal with deflation when interest rates are almost as low as they can go. Just look at Japan, which had deflation in nine separate years from 1999-2012, with two additional years at zero, averaging minus 0.3%. The highest in any single year was minus 1.3% in 2013. 5 In the European Union (EU) in 2008, at the start of the financial crisis, there were fears of deflation but at that time central banks had the ability to cut interest rates by nearly 5 percentage points. Those fears may now be coming true, with the EU experiencing deflation of 0.5% in 2015. This was driven primarily by declines in energy prices, but there was also deflation 10 in non-energy industrial goods and telecommunications. The collapse in the cost of shipping goods potentially suggests something deeper is going on and may lead to a more persistent form of deflation than Mark Carney has currently claimed. (Source: adapted from http://www.independent.co.uk/news/business/comment/david-blanchflower/ david-blanchflower-deflation-is-bad-news--and-britain-is-likely-to-be-next-to-get-it-10078832.html)
(g) Evaluate demand-side policy responses to the Global Financial Crisis of 2008. (20)

Work with an Edexcel economics tutor

Want a paper marked and gone through with you? Message us.

Prefer email? Send an enquiry

If you are under 18, please include a parent's contact details. Enquiries go to enquiries@economicsaleveltutor.com and are deleted once handled. All tutoring is online.